Fed Chairman Warsh says inflation is running too high, offers first assessment of the economy
Key Takeaways
- •Warsh said inflation is still too elevated and that the Fed must ensure it is moving toward its 2% objective fast enough.
- •He indicated that broad financial conditions may not be restrictive, suggesting interest rates could be less of a drag on the economy than some expect.
- •Warsh described U.S. growth as firm, citing a 9% increase in capital expenditures over the past four quarters, much of it tied to AI-related investment.
- •He said consumer spending has remained healthy, S&P 500 profit margins are elevated, and the labor market is consistent with full employment.
- •Warsh did not give forward guidance and said the July decision to keep rates unchanged reflected a desire to wait for more information before the September FOMC meeting.
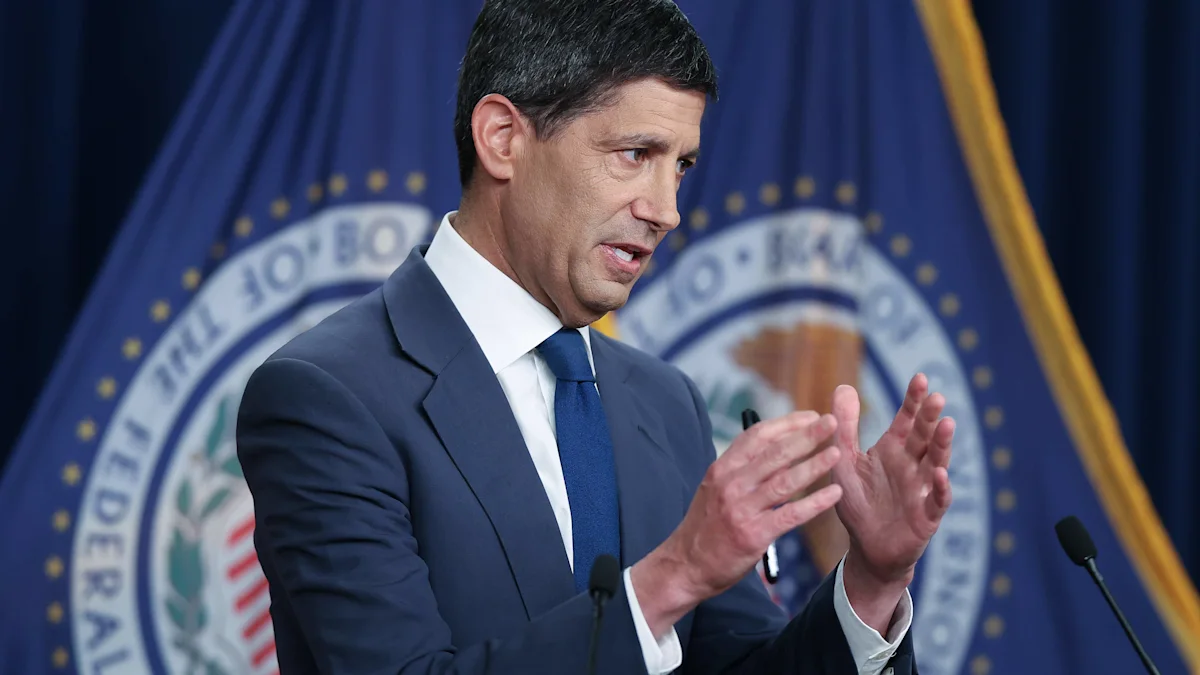
Federal Reserve Chairman Kevin Warsh, in a closely watched speech Friday, said inflation is running too high and should be the focus for the central bank, while laying out a strong assessment of the economy for the first time. But he held to his pledge not to provide forward guidance.
"We must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do," Warsh said in his first speech as chairman, delivered in Jackson Hole, Wyo. "It is the Fed's job to deliver stable prices."
While Warsh did not offer forward guidance, he hinted that interest rates may not be holding back the economy much, saying, "I would be hard-pressed to describe broad financial conditions as restrictive."
The stakes were heightened by the setting. The speech came at the Kansas City Fed's annual economic policy symposium, the Wyoming retreat where Fed chairs have historically delivered some of their most consequential addresses — Jerome Powell used the platform in 2020 to unveil a new policy framework and in 2022 to signal a sustained fight against inflation. Markets had clamored for clarity on whether the Fed has a credible strategy to bring down inflation and whether the chairman would offer an assessment of the economic picture. He came through on the latter; whether markets are satisfied on the strategy question will become clear in the reaction to the speech.
Inflation remains the focus
Pointing to the Personal Consumption Expenditures index, Warsh noted that "the numbers are more concerning." He cited market measures of inflation expectations and stressed the importance of those signals reverberating back to the Fed.
"It is a credit to the Fed as an institution — and consistent with the best of the Fed's traditions — that market prices show confidence that we will deliver price stability. And I can assure you … they're right," he said.
Warsh noted that broad inflation measures have fallen significantly from their 2022 heights, but that progress over the past two years has been modest. He said that while this summer's PCE and Consumer Price Index readings were better than expected, "they do not tell me that underlying trends have meaningfully improved."
His reference to the PCE index also carried weight beyond the data. Questions had persisted over whether PCE would remain the central bank's preferred inflation gauge, given the doubt Warsh cast on it during his press conference in July. Warsh's mention of PCE on Friday seemed to suggest it will. That gauge has anchored the Fed's price-stability goal since January 2012, when the central bank formally defined its objective as 2% inflation over the long run as measured by PCE — one half of the dual mandate Congress assigned it, alongside maximum employment.
Soaring profits, stable labor market
Warsh painted a robust picture of the US economy, noting that economic growth appears to have strengthened, citing "rapidly rising" capital expenditures, which he estimates grew by 9% over the past four quarters. He noted that more than half of this year's capital expenditure growth is likely attributable to the artificial intelligence build-out — a nod to the surge in data-center and computing-infrastructure spending by the country's largest technology companies.
Consumer spending adjusted for inflation has been healthy despite the surge in oil prices, tariffs, and other shocks, increasing by more than 2% over the past four quarters, he said. He also pointed to firms' profits in the S&P 500, noting that profit margins are "quite elevated relative to history."
Warsh doubled down on the fact that the Fed is closely watching markets for signals on the economy. "We're staying keenly focused on market internals, watching performance across sectors," he said, adding that he will continue to monitor changes in the growth rates of corporate earnings and capital spending, as well as the follow-on effects on asset prices, business confidence, consumer income, and spending.
On employment, Warsh characterized the job market as "quite stable," saying it is consistent with full employment. He noted that low turnover is a result of the significant rematching between employers and employees that happened at scale after the pandemic.
'Just don't call it forward guidance'
Warsh stuck to his pledge not to offer guidance about the path forward for monetary policy. Early in the speech, as he provided an overview of the topics he would cover, he quipped, "You can call it an outline . . . you can call it a trail map . . . just don't call it forward guidance."
Later, he struck a more sober tone as he returned to his long-held skepticism about overcommunicating. "Transparency in communications about future policy decisions is not a virtue unto itself," he said. "Communications must be in service to the Fed's paramount responsibility: getting monetary policy right."
His position departs from the practice of recent decades, in which forward guidance became a Fed staple after the 2008 financial crisis as officials, with rates near zero, sought to support the economy by shaping expectations about the path of policy. Warsh, who served as a Fed governor from 2006 to 2011, has questioned the value of that approach for years.
He did, however, explain why officials decided to hold interest rates steady in July, pointing to the minutes from that meeting. Warsh noted that "a good majority of my colleagues and I thought the wiser course was to await new information in the intermeeting period — especially given possible developments in supply chains, investment flows, and geopolitics — before deciding whether a change in interest rate policy was advisable."
The next scheduled Federal Open Market Committee meeting, set for September, along with the inflation and jobs data due before it, offers the next formal checkpoints for a committee that, by Warsh's account, chose in July to wait for more information.
Reporting by Jennifer Schonberger for Yahoo Finance.

