Nigeria's DisCos Revenue Surges 450% to ₦1.2 Trillion as Electricity Supply Grows Just 4.8%
Key Takeaways
- •Nigeria's distribution companies increased revenue collections by 450% to ₦1.2 trillion in the first half of 2026, while the electricity actually delivered to consumers grew only 4.8% over the same eight years.
- •Average available generation capacity dropped 41% between early 2018 and mid-2026, from 7,565.5 MW to 4,456 MW, despite more than 13,000 MW of installed capacity existing on paper.
- •National metering stood at 57.27% in late 2025, leaving more than 5.19 million active customers on estimated billing, and DisCos recorded a ₦700 billion gap between energy billed and revenue collected in the first half of 2026.
- •President Tinubu's administration approved a ₦3.3 trillion settlement in 2026 to address up to ₦6 trillion in legacy sector debts, while 15 states have assumed regulatory control of their intrastate electricity markets under the Electricity Act 2023.
- •Power unreliability is straining Nigeria's technology sector, with over 60% of startup hubs citing erratic electricity as their primary operational threat and captive power systems consuming 30-40% of data centre construction budgets.
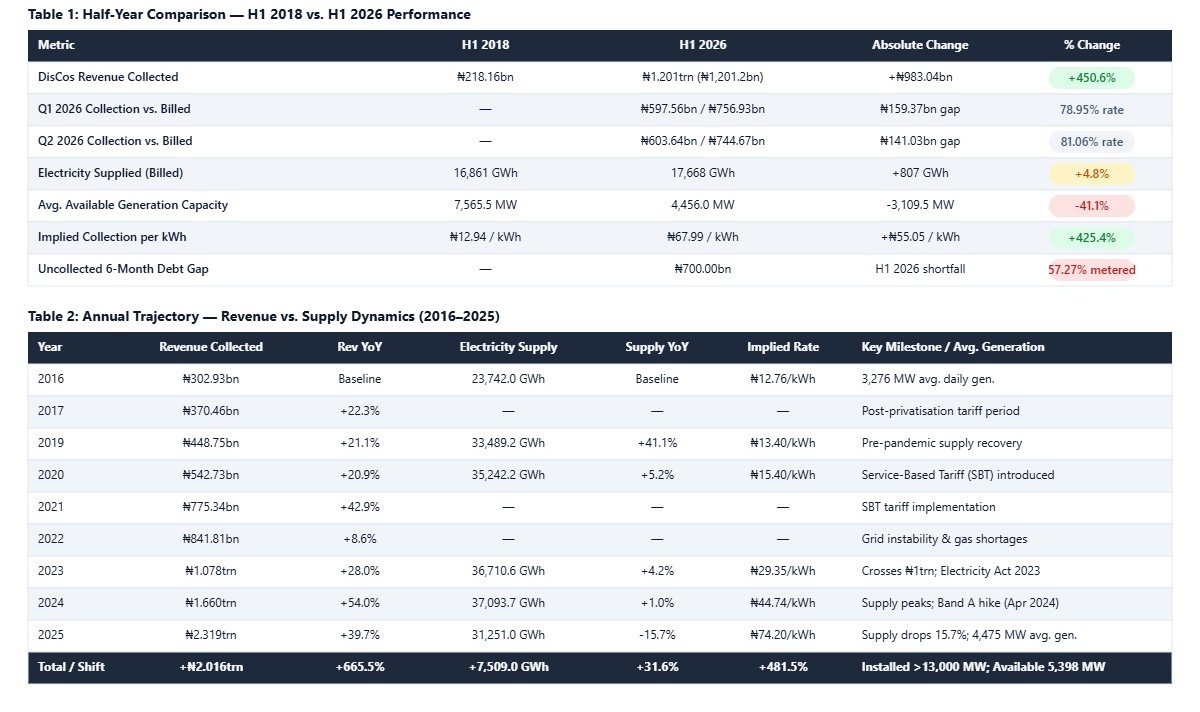
Nigeria's electricity distribution companies (DisCos) have posted sharply rising revenues over the past eight years even as the power actually delivered to consumers has barely grown, according to financial filings from the Nigerian Electricity Regulatory Commission (NERC). The regulator's second-quarter 2026 filings lay out a widening disconnect between what Africa's most populous nation pays for electricity and what its national grid physically supplies.
Between the first six months of 2018 and the first half of 2026, revenue collected by Nigeria's 11 DisCos surged by 450%, climbing from ₦218.16 billion to ₦1.2 trillion, according to the NERC's 2026 Q2 report. Over that exact eight-year window, electricity supplied to consumers rose by just 4.8%, moving from 16,861 gigawatt-hours (GWh) to 17,668 GWh. Average available generation capacity fell by 41% over the same period, dropping from 7,565.5 megawatts (MW) in early 2018 to 4,456 MW in the first half of 2026.
In effect, Nigerians are not buying more electricity; they are paying drastically more for the same rationed megawatts.
Collections outpace delivery
The gap between revenue collection and energy delivery widened most sharply between 2024 and 2026. Following the introduction of the Service-Based Tariff adjustments and steep Band A rate increases in 2024 — Band A being NERC's top tariff tier, reserved for customers guaranteed a minimum of 20 hours of supply per day — annual DisCo revenues jumped from ₦1.66 trillion in 2024 to ₦2.32 trillion in 2025. Across that same twelve-month stretch, total annual electricity supply contracted by 15.7%, falling from a peak of 37,093.70 GWh in 2024 to 31,251 GWh in 2025.
Even with collections hitting record nominal highs in 2026, billing shortfalls persist. DisCos recorded a ₦700 billion shortfall between energy billed and revenue collected in the first six months of 2026 alone. NERC's fourth-quarter 2025 disclosures show that national metering reached 57.27%, with 6.97 million metered accounts out of 12.16 million active customers, while more than 5.19 million active consumers remain on estimated billing — charges based on projected rather than metered consumption. The regulator issued monthly energy caps in May 2026 to curb arbitrary overcharging, and has also approved ₦28bn for DisCos' free meters, as previously reported. How quickly that ₦28bn allocation converts into installed meters — and lifts the 57.27% national metering rate — is the sector's most direct near-term gauge of whether estimated billing recedes.
The broken promises of the 2010 Power Roadmap
The origins of the current situation date to August 2010, when the federal government unveiled the Roadmap for Power Sector Reform. Building on the Electric Power Sector Reform Act of 2005, the blueprint promised to end chronic blackouts by unbundling the state-owned Power Holding Company of Nigeria (PHCN) into 18 successor entities: six generation companies (GenCos), 11 DisCos, and the state-retained Transmission Company of Nigeria (TCN). The Roadmap projected attracting $3.5 billion annually in private investment to push generation capacity toward 40,000 MW by 2020.
When core investors took over the privatised assets in November 2013, the sales were hailed as a watershed moment. In practice, the transaction transferred public monopolies to heavily leveraged consortiums that lacked both the technical expertise and the equity capital to upgrade decaying substations. Because the new owners borrowed heavily from local banks to fund the acquisitions, their balance sheets buckled when the naira weakened and gas shortages hit.
Thirteen years after privatisation, Nigeria has more than 13,000 MW of installed capacity on paper, yet average daily generation stands at about 4,475 MW — far short of the 40,000 MW projected for 2020, some 16 years after the Power Roadmap was launched.
Each link in the value chain blames the next. DisCos reject power or fail to remit funds in full; GenCos are starved of gas as vandalism and dollar-denominated pricing disputes cripple pipelines; and TCN's fragile grid has repeatedly tripped, recording more than 100 collapses in the last ten years.
Rather than weaning the treasury off subsidies, the privatised market has accumulated up to ₦6 trillion in legacy sector debts, compelling President Bola Tinubu's administration in 2026 to approve a ₦3.3 trillion settlement plan backed by hundreds of billions of naira in cash and non-cash bonds. While the Electricity Act 2023 has allowed 15 states to assume regulatory control of their intrastate markets as of 2026, decentralisation has yet to translate into additional electricity on the grid. The disbursement of that ₦3.3 trillion settlement, and how many more of Nigeria's 36 states follow the initial 15 into market control, are the structural items to watch as the reform enters its next phase.
The toll on the wider economy and the tech ecosystem
The Rural Electrification Agency estimates that 85 million Nigerians still lack grid access, and across the broader economy the dysfunction acts as a heavy tax on productivity. Manufacturers and small businesses burn trillions of naira annually on diesel and petrol generators just to stay open.
The burden falls hardest on the technology ecosystem, where modern digital infrastructure runs on uninterrupted, high-density electricity. In May 2026, a landmark survey by the Innovation Support Network (ISN) warned that Nigeria's digital and startup hubs face an existential survival crisis, with more than 60% of hubs citing erratic power and punishing utility costs as their primary operational threat. Early-stage startups that would otherwise deploy venture capital into software engineering and product growth are instead diverting runway into Band A electricity bills, diesel supply contracts, and solar-inverter arrays.
At the infrastructure layer, the penalty is steeper still. According to a January 2026 market analysis by Mordor Intelligence, captive power and redundancy systems — including dual generator banks, uninterruptible power supplies, harmonic filters, and voltage-conditioning transformers — swallow between 30% and 40% of total data centre construction budgets in Nigeria. Grid unreliability and diesel volatility shave nearly five percentage points off the projected compound annual growth rate of Nigeria's data centre power market, which reached $120.38 million in 2026.
The International Monetary Fund estimates that artificial intelligence could boost sub-Saharan Africa's economic output by 4% over the next decade, but explicitly warns that power shortages threaten to erase those gains. Against that backdrop, Nigeria's average available generation of 4,456 MW in the first half of 2026 underscores the scale of the challenge facing the country's bid to build a globally competitive twenty-first-century cloud and AI economy.

