CashAfrica's Chicken Republic Rollout Highlights the Hurdles Facing Contactless Payments in Nigeria
Key Takeaways
- •CashAfrica has partnered with Food Concepts to introduce mobile tap-to-pay at more than 350 Chicken Republic outlets across Nigeria.
- •Earlier contactless initiatives, including Unified Payments' PayAttitude in 2015 and Access Bank's Tap to Phone with Visa in March 2025, expanded merchant acceptance without changing consumer payment behavior at scale.
- •Central Bank of Nigeria guidelines from 2023 permit contactless transactions of up to ₦15,000 without additional verification, subject to a cumulative daily limit of ₦50,000.
- •Cash transactions in Nigeria fell 59% between 2014 and 2024, while POS terminals processed 1.38 billion transactions worth ₦18.32 trillion ($13.5 billion) in 2024.
- •Tap-to-pay adoption could leverage Nigeria's 8.3 million registered POS terminals, some of which already support NFC, but success depends on customers choosing taps over familiar bank transfers.
CashAfrica announced on October 13 a partnership with Food Concepts, the quick-service restaurant company, to introduce mobile tap-to-pay across Chicken Republic's more than 350 outlets, as part of its effort to drive wider adoption of contactless payments in Nigeria.
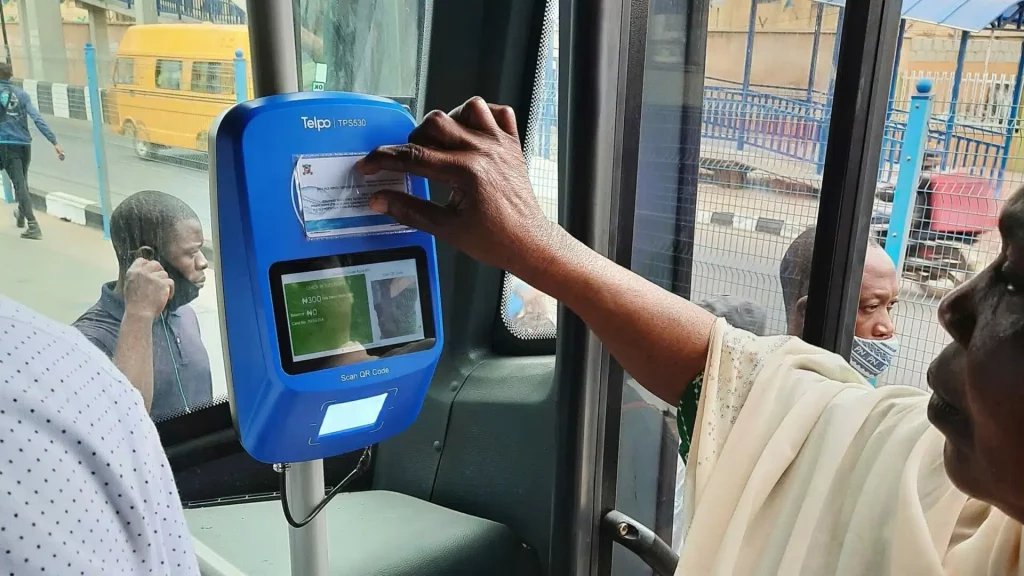
Many Lagos commuters have already encountered the technology. The blue Cowry card, operated by Touch and Pay Technologies (TAP) for Lagos' transport authority, works across the city's road, rail, and ferry networks. TAP says it has more than 300,000 active users and has processed over 56 million transactions across its operations. The system works because the card and technology are purpose-built for paying for transportation, and the contactless payment process is integrated into the journey itself: commuters are required to tap to pay before boarding the bus.
That integration offers a starting point for understanding the challenge facing contactless payments in Nigeria. The technology is not new. A contactless payment requires a customer with a contactless card or near-field communication (NFC)-enabled device, a merchant with a compatible terminal, and payment infrastructure that connects the transaction to the customer's bank or payment provider.
Data from the Nigeria Inter-Bank Settlement System (NIBSS) shows that POS terminals processed 1.38 billion transactions worth ₦18.32 trillion ($13.5 billion) in 2024. Cash has historically dominated how Nigerians pay, but its share has been shrinking. Between 2014 and 2024, cash transactions in Nigeria fell by 59%, and electronic payments took their place. This means Nigerians do not need to be convinced that they can pay digitally—they already do. What they are not yet convinced of is why they should pay this particular way.
Nigeria Has Been Here Before
The CashAfrica partnership with Chicken Republic is not the first attempt to make contactless payment a normal part of the payment process in Nigeria. In 2015, Unified Payments, a Nigerian payments infrastructure company, launched PayAttitude with six banks, including Access Bank, UBA, Zenith Bank, Skye Bank, Diamond Bank, andBank. The NFC-based service allowed customers to pay by tapping an NFC-enabled tag against a compatible POS terminal. The tag could be attached to a phone or carried separately, and transactions were linked to a prepaid wallet.
In March 2025, Access Bank launched Tap to Phone with Visa, allowing merchants to accept contactless card and device payments directly on NFC-enabled Android phones without a traditional POS terminal.
Each attempt solved part of the supply problem, either by making compatible devices easier to distribute or by making merchant acceptance points easier to deploy. Still, none created a compelling enough reason for consumers and merchants to change payment behaviour at scale. The Chicken Republic deal works the supply side from a different direction: a single agreement puts acceptance in place across more than 350 locations at once, leaving the harder half of the problem—whether customers actually use it—on the demand side.
There is also a trust problem. In a low-trust market like Nigeria, where consumers are wary of payment fraud, removing the familiar security step of PIN authentication can create friction over whether tapping is safe. Nigeria's contactless rules now put some boundaries around that risk. In 2023, the Central Bank of Nigeria issued guidelines covering the authentication and risk management requirements for contactless payments. The rules allow transactions of up to ₦15,000 ($11.28) without additional verification and a cumulative daily limit of ₦50,000 ($37.60). For a restaurant rollout, those limits define the practical zone of the technology: quick-service purchases are small and frequent, so a tap at a Chicken Republic counter would typically fall within the verification-free range rather than trigger extra authentication.
Tap-to-pay is also competing with transfers, which have become a familiar payment method in parts of the country. By February 2023, due to the naira redesign policy and the resulting cash shortage, currency in circulation fell from ₦3.29 trillion ($2.47 billion) in October 2022 to ₦982.09 billion ($738 million). As Nigerians struggled to access physical cash, electronic payments surged to an all-time high of ₦600 trillion ($451 billion) in 2023, a 55% increase from the previous year.
The cash shortage forced Nigerians to find another way to pay. Circumstances made the alternative necessary, and repeated use made it familiar. Tap-to-pay has no equivalent forcing function. Other payment options remain available, so being faster alone is not enough. The technology has to offer an advantage that transfers, cards, and cash do not—and make that difference obvious enough that consumers and merchants have a reason to switch.
What Tap-to-Pay Unlocks
Tap-to-pay can gain ground within the already existing POS network. NIBSS counted 8.3 million registered POS terminals as of March 2025, some of which already support NFC. NIBSS is also responsible for certifying payment terminals and applications deployed in Nigeria, which creates a common infrastructure layer across the industry. The POS agent who currently handles transfers, processes card transactions, or dispenses cash could become part of the tap-to-pay distribution network. The catch is that a terminal can accept tap-to-pay and still have customers who would rather make transfers.
Tap-to-pay also fits into Nigeria's cashless policy agenda. When the Central Bank of Nigeria introduced the policy, it argued that the country's heavy reliance on cash was costly to manage, increased the risk of robbery and cash-related losses, kept money outside the formal financial system, and limited the effectiveness of monetary policy. If tap-to-pay can make electronic payments easier at the point of purchase, it could help shift more transactions from cash to the formal digital economy, reducing cash-handling costs and revenue leakage.
The payment method could also normalise more advanced forms of authentication during payments, including biometric authentication. Nigerian companies have already experimented in this area. Access Bank announced a facial biometric payment system in 2020, while Accelerex, a Nigerian fintech, launched Pay with Fingerprint on NIBSS-certified biometric POS devices in 2024. However, like earlier contactless attempts, these systems have had few places where consumers could use them. If tap-to-pay can make contactless authentication part of everyday transactions, it could help build consumer trust in the payment method.
The Chicken Republic rollout is the latest test of whether contactless payments can move beyond pilots and partial coverage in Nigeria. Based on the track record of previous attempts, true scale will demand moving beyond surface-level integrations to robust execution. How the test goes will be readable in ordinary indicators: whether diners tap at the counter instead of reaching for a transfer, whether usage holds after the launch period across the more than 350 outlets, and whether other merchants see reason to switch on the NFC capability that some of Nigeria's 8.3 million registered POS terminals already carry.

