Why investors shouldn’t rush to buy the next blockbuster IPO
Key Takeaways
- •US IPOs have averaged first-day returns of roughly 18% to 19% since 1980, but those gains mainly accrue to investors allocated shares at the offer price.
- •Investors who buy after trading begins may capture far less than the headline IPO pop because allocations in strong deals are limited and weaker deals are easier to access.
- •Newly listed companies have tended to underperform comparable firms in the first few years after listing, with the weakness concentrated in smaller, unprofitable issuers.
- •Lock-up expiries can be a useful point to reassess newly listed stocks because additional shares entering the market can pressure prices if demand does not rise.
- •The article says private-market exposure is not automatically better than public-market investing, since venture returns are heavily skewed toward the earliest and riskiest funding rounds.
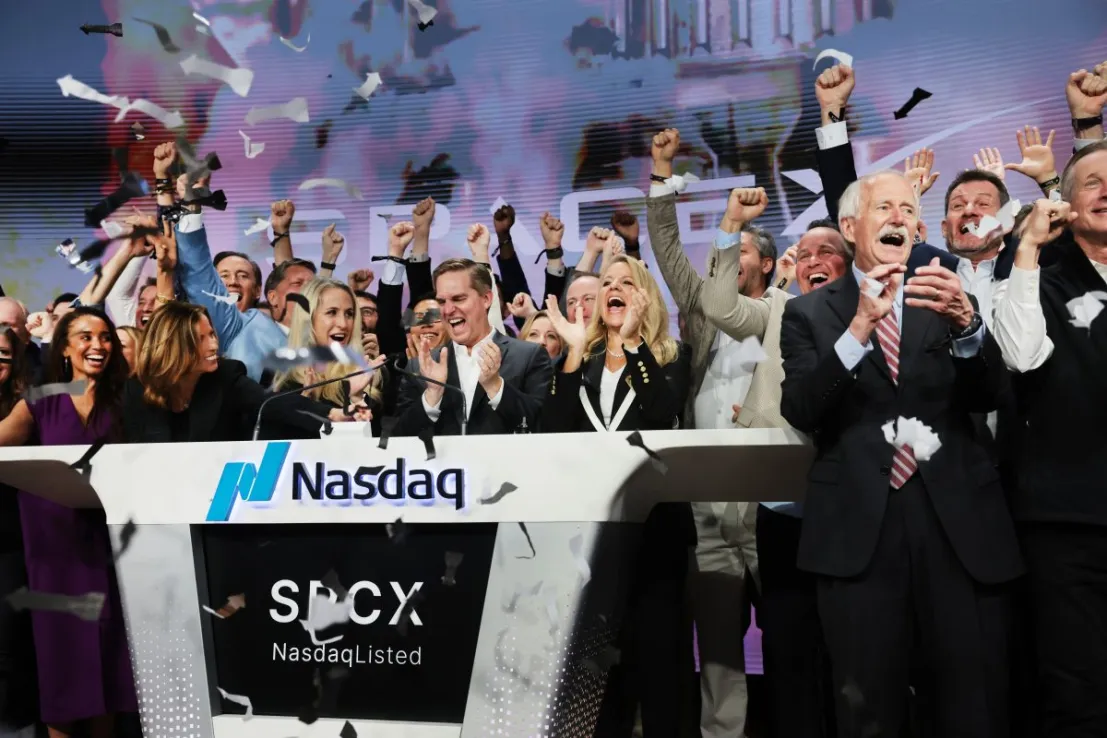
IPOs get investors frothing at the mouth, yet the evidence suggests they should be viewed with greater caution, writes Yves Bonzon
There are very few financial events that generate as much excitement as initial public offerings (IPOs). Yet history shows they should be viewed with caution. When stepping back and looking at what decades of empirical research say about investing in IPOs, the evidence is remarkably consistent and sobering.
The first well-known stylized fact is IPO underpricing. On average, US IPOs have delivered a first-day return of roughly 18 to 19 per cent since 1980, according to the latest data compiled by Jay Ritter of the University of Florida. But this “money left on the table” accrues largely to those who receive an allocation at the offer price — typically institutional investors linked to the underwriting syndicate — rather than to those buying once shares begin trading.
Securing an allocation is also no guarantee of investment success. Allocations in blockbuster deals are heavily rationed, while weak deals are typically readily available — the classic winner’s curse. As a result, an investment strategy that indiscriminately subscribes to IPOs is bound to earn far less than the headline first-day pops reported in IPO studies. For investors watching the market from the sidelines, that distinction matters because the most visible returns are not necessarily the ones available to the average buyer.
Patience is a virtue
Newly listed companies can also struggle to maintain their early momentum. Ritter found that IPOs significantly underperformed comparable firms in the first few years after listing, although much of this underperformance is concentrated among smaller, unprofitable companies. The pattern appears to be closely linked to market timing. Companies are skilled at issuing shares when investor enthusiasm, and valuations, are close to their peak. This aligns with one of our longest-standing investment convictions that valuation levels only matter in rare moments when they reach extremes, changing the reaction function of corporate issuers.
All in all, the empirical record suggests that patient investors are usually offered better entry points in the quarters following a listing than in the euphoric opening days. This does not mean investors should avoid IPOs altogether. Every great public company was once an IPO, and some of tomorrow’s biggest winners are undoubtedly listing today. The lesson is one of patience and discipline. Lock-up expiries can offer a useful moment to reassess sentiment toward newly listed companies. As insider selling restrictions are lifted and more shares become available for trading, the market must absorb the additional equity supply. Without a corresponding increase in demand, that incremental supply can exert additional mechanical downward pressure on share prices.
Private vs public
If the average public market investor is structurally late to the party, why not simply join it earlier and participate while these companies are still private? While history shows that each generation of founders and venture capitalists has learned to stay private longer and harvest more of the value-creation curve before an IPO, this does not automatically make private market investments more attractive. In fact, venture capital returns are extraordinarily skewed toward the earliest funding rounds. The steepest part of the value-creation curve accrues to investors willing to bear the highest mortality risk, at a stage where access is limited and identifying the eventual outliers with any meaningful degree of certainty is exceedingly difficult.
For most investors, the key is therefore not to choose between private and public markets. One should remain disciplined in both. Private markets can offer attractive opportunities, particularly through experienced managers with access to promising companies at earlier stages of development. But a pre-IPO label does not automatically translate into superior returns; access, manager selection and valuation matter just as much as they do in public markets.
Ultimately, investors cannot afford to miss the big winners in public markets. The objective is to participate in the long-term growth of exceptional businesses, not to gain access to them at the earliest possible stage. There is no need to secure a pre-IPO or IPO allocation at any price. Instead, investors can afford to be patient and build positions once the initial IPO volatility has subsided, while much of the company’s long-term compounding potential remains unrealized.
Yves Bonzon is group chief investment officer at Julius Baer

