Stablecoins Are Moving Billions Across Africa—Stakeholders Outline What Full Adoption Requires
Key Takeaways
- •Panelists said African importers increasingly use dollar-backed stablecoins to pay suppliers in China, bypassing weekend bank closures and slow wire corridors.
- •Nigeria recorded roughly $59 billion in crypto-asset inflows between July 2023 and June 2024, and Chainalysis data shows it accounted for 60 percent of stablecoin inflows into Sub-Saharan Africa.
- •World Bank data shows sending $200 to Sub-Saharan Africa cost an average of 8.46 percent in late 2025, the highest rate globally, which panelists cited as an opening for stablecoin builders.
- •Adoption barriers include user distrust fueled by platform hacks, heavy regulatory compliance burdens, fragmented on-chain liquidity, and Nigerian banks that still do not process crypto-linked transactions.
- •Hyperbridge CEO Seun Lanlege endorsed direct on-chain swaps between African local-currency stablecoins, such as Nigeria's cNGN, to reduce value lost to foreign correspondent banking intermediaries.
On Nigerian tech X (Twitter) during conference week, one gripe recurs with clockwork regularity: African founders are building far too many payment applications. But step into a trading plaza in Lagos or Onitsha on a Friday night—when a merchant must settle a factory invoice in Guangzhou before an 11 p.m. cut-off—and the talk of oversaturation evaporates. Commercial bank branches are shut for the weekend, dollar liquidity at the teller window is thin, and traditional wire corridors crawl at a snail's pace.
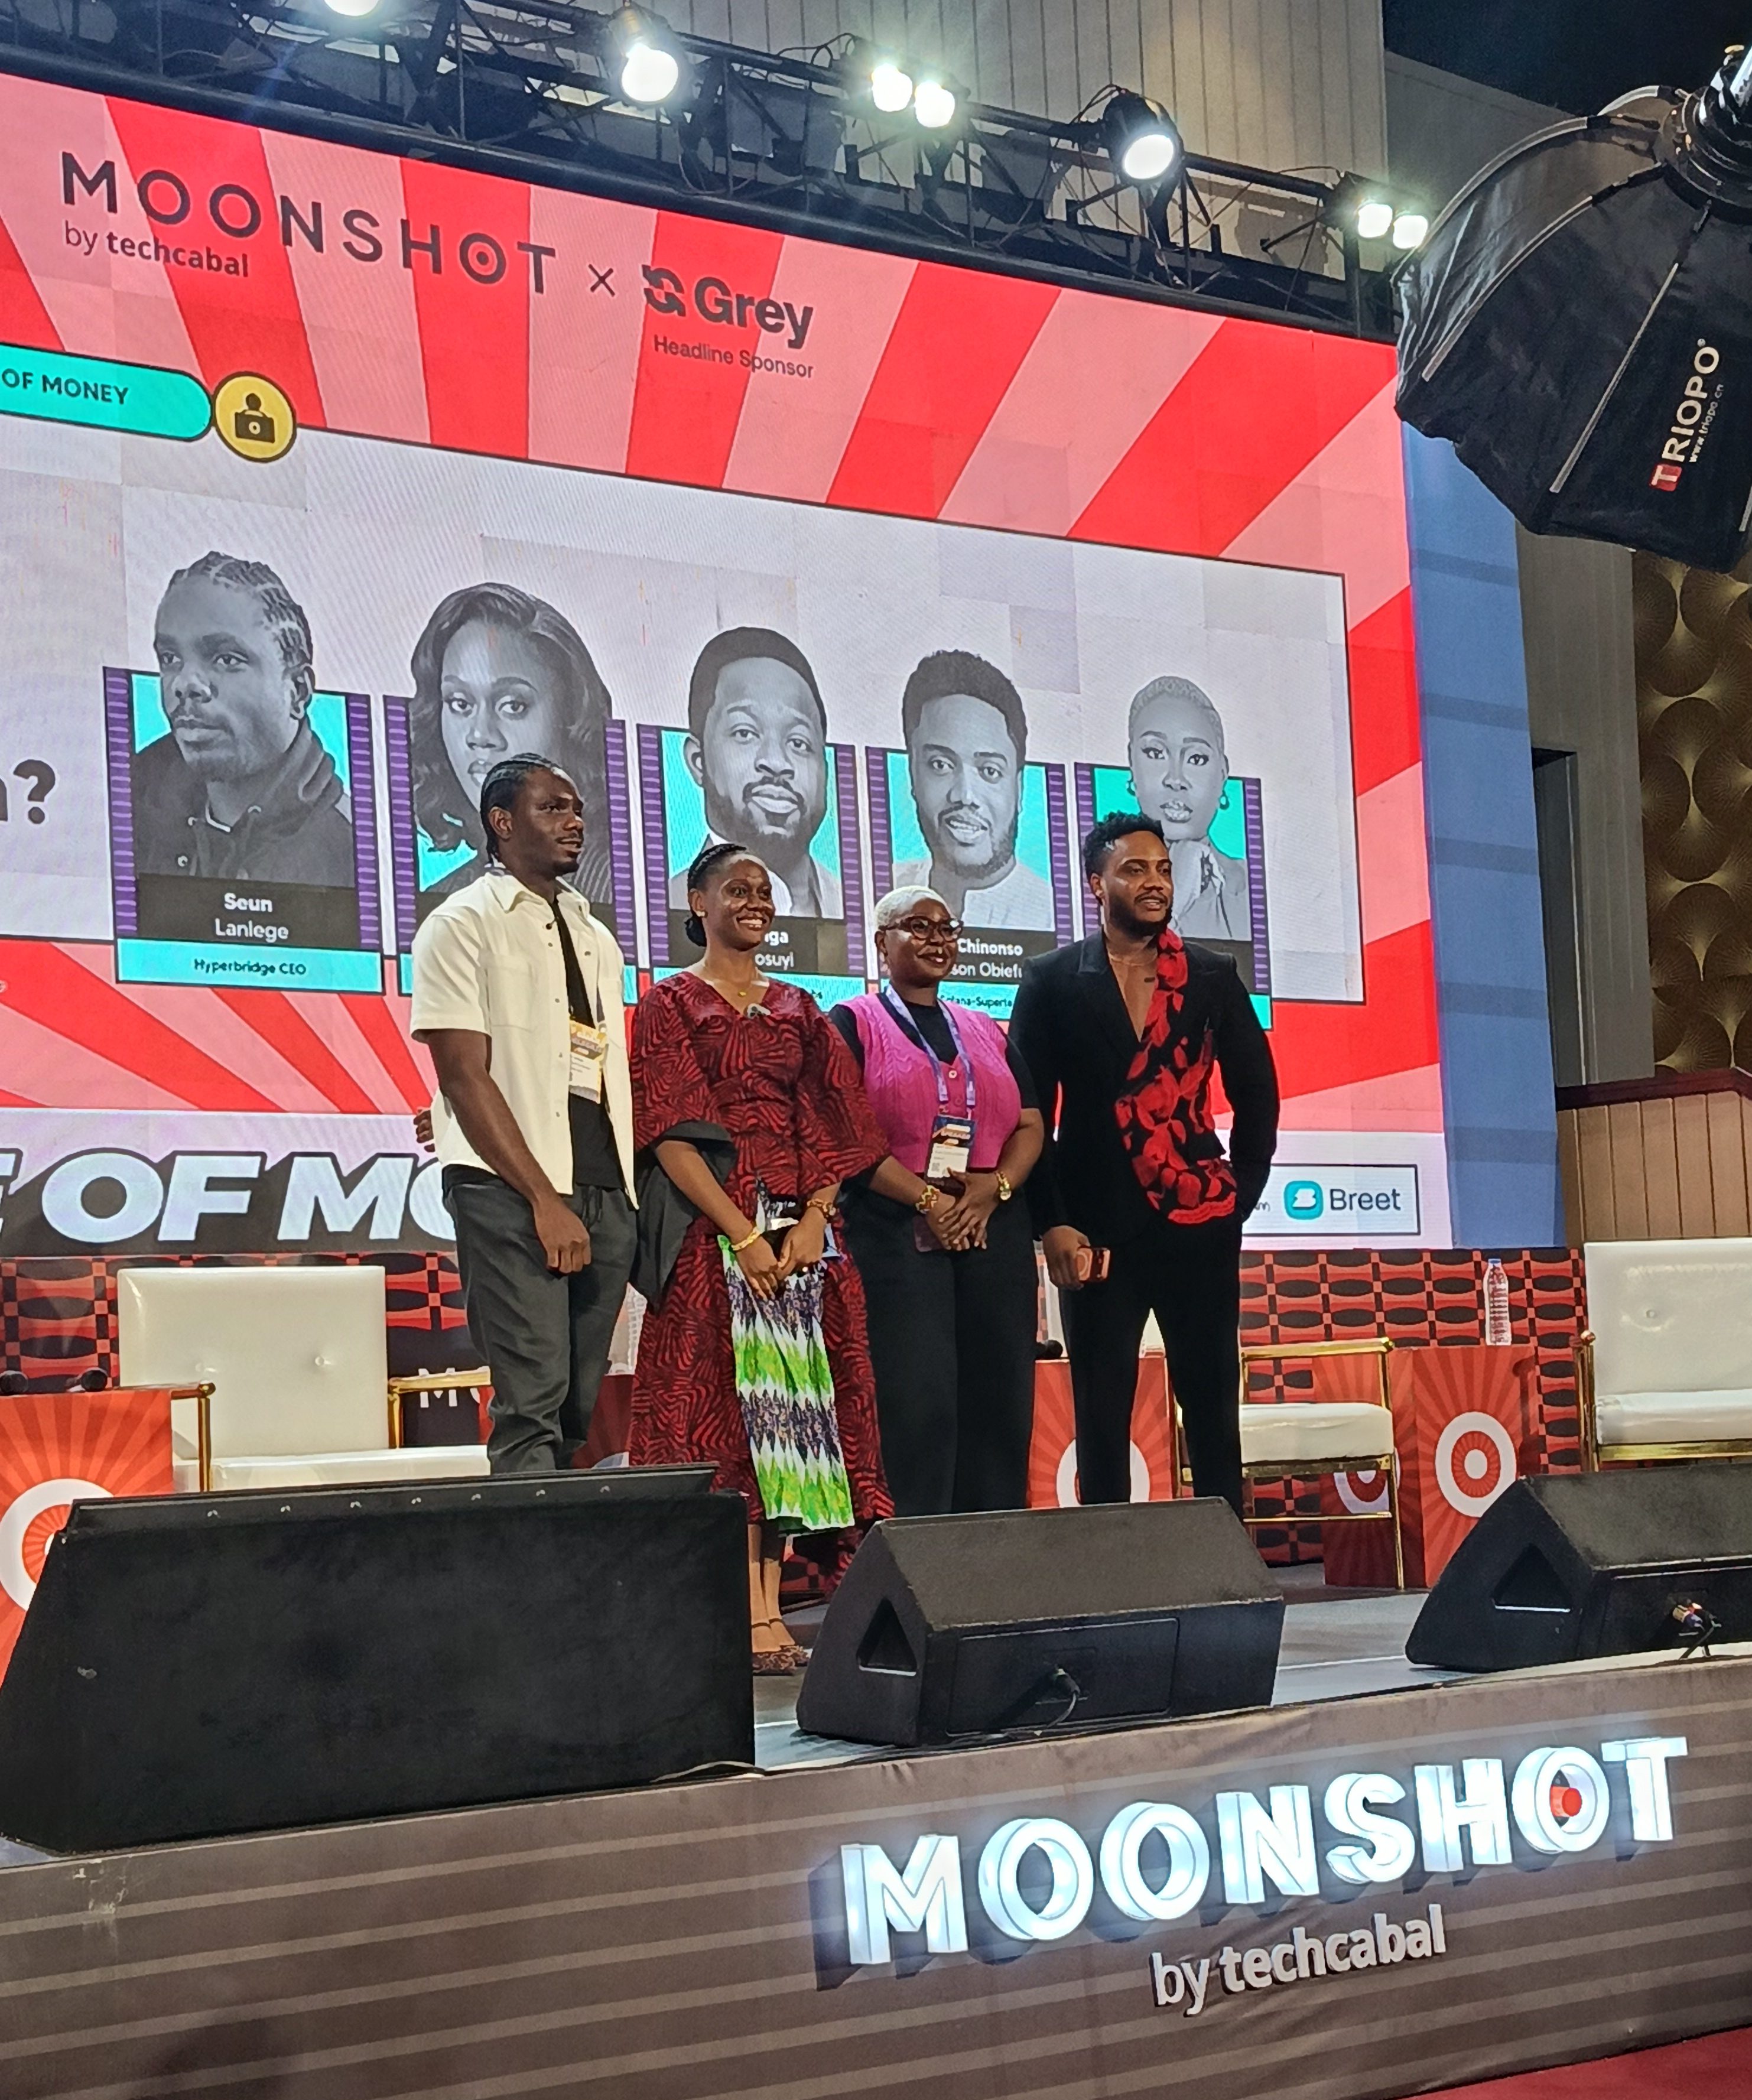
That disconnect between modern payment instruments such as stablecoins—digital tokens designed to hold their value against fiat currencies like the US dollar—and everyday commercial necessity framed a packed panel session on Day 2 of Moonshot 2026, organized by TechCabal at the National Theatre in Lagos on Thursday. Held under the theme "Where Are Stablecoins Creating Real Value in Africa?", the discussion brought together Dr. Chinonso Harrison Obiefule, Lead at Superteam Nigeria; Seun Lanlege, founder and CEO of blockchain interoperability protocol Hyperbridge; and Odinaka Esiagu, Head of Customer Success and Operations at digital asset platform Obiex. The panelists set aside speculative crypto jargon to examine where digital dollars and local stablecoins are doing the heavy lifting across the continent.
Physical trade, not speculation
For Obiefule, the most durable use case in 2026 has nothing to do with token speculation and everything to do with physical trade. Because accessing US dollars through formal banking channels remains difficult for small and medium-sized importers, merchants have turned to dollar-backed tokens out of sheer pragmatism.
"I am seeing a lot of my Igbo brothers; they're paying their suppliers in China via stablecoin," Obiefule told the audience. "That is why, as techies, when we start to have these fancy conversations about stablecoins being the future on Twitter, I tend to laugh because our Igbo brothers have been using stablecoins for five or ten years ago, right? They've been using it to pay their suppliers in China."
Macroeconomic figures back up that street-level observation. The International Monetary Fund (IMF) highlighted in June 2026 that Nigeria recorded roughly $59 billion in crypto-asset inflows between July 2023 and June 2024. Independent data from Chainalysis shows those flows placed Nigeria second globally in grassroots crypto adoption and accounted for 60 percent of all stablecoin inflows into Sub-Saharan Africa.
Remittances and B2B settlement drive volume
At Obiex, which provides liquidity and settlement rails for remittance and payment firms, Esiagu sees two forces driving that volume: B2B supplier settlements and the "japa" emigration wave, named for the Yoruba word meaning "to flee." With millions of Nigerians relocating abroad and sending money home to relatives, remittance startups are plugging into Obiex's backend to bridge foreign corridors faster than legacy money transfer operators allow. For businesses, she argued, the decisive advantage is round-the-clock settlement speed.
"If I cannot get my money immediately when I'm making a payment, I would just probably close the deal because you see customers say, 'Oh, this deal is going to be closed in so-and-so amount of time, maybe 11 p.m.,'" Esiagu explained. "And if it was a bank, definitely 11 p.m. will not be what you'll be discussing. But with stablecoins, you know that transactions are moving at any time of the day."
Why African payments are still unsolved
If stablecoins settle in seconds, why does cross-border money movement in Africa still feel broken? Obiefule pushed back directly against critics who claim the continent already has enough payment startups.
"Builders get a lot of smoke for building payment products. But the truth is we haven't solved payments. Who wants to argue?" he challenged. "We haven't. It costs an average of eight point something per cent to make cross-border, for example, payments in Africa. I think if you're sending $200, on average, it costs about $17, right? So that is an avenue where builders that are building in the stablecoin space can come in."
World Bank Remittance Prices Worldwide data confirms his arithmetic: sending $200 to Sub-Saharan Africa cost an average of 8.46 percent ($16.92) in late 2025, making it the most expensive region in the world for diaspora transfers.
Obiefule noted that many existing local swap tools remain either too expensive, inefficient, or reliant on peer-to-peer (P2P) desks plagued by fraud risks. To close those gaps, Superteam Nigeria operates as what he called Solana's "SEAL Team Six," funding local founders with grants and training to build on Solana's low-cost network, where transaction fees sit around a fraction of a cent. According to Hashed Emergent's developer reports, Nigeria now accounts for 66 percent of all Solana developers in Africa.
Trust and complexity still hold back everyday users
For Esiagu, however, low gas fees—the variable costs charged to process transactions on a blockchain network—alone will not win over small businesses or retail users. Everyday adoption lags because of a persistent trust deficit fueled by news of platform hacks, alongside the heavy burden of regulatory compliance.
"Stablecoins will still maybe be a mystery until maybe the market women can use them," Esiagu said.
To strip away that complexity, she revealed that Obiex is building a white-label infrastructure product that handles engineering, security, and compliance on behalf of businesses. Using the example of a founder launching a payment service for University of Lagos (UNILAG) students, she noted that the merchant can run entirely on stablecoin rails at the backend without students ever needing to know that crypto is involved.
Fragmentation traps liquidity
Beneath the user interface lies a deeper structural headache: blockchain fragmentation. Lanlege pointed out that stablecoins succeeded initially because they offered "permissionless movement of money," echoing Circle CEO Jeremy Allaire—whose company issues the USDC stablecoin—in his description of stablecoins as "zero gravity for money." Yet as tokens proliferate across networks, liquidity gets trapped in silos.
"On HyperFX today, all of our cNGN is on Base, and all of our USDT providers are on BNB Chain," Lanlege said, referring to the compliant Nigerian naira stablecoin. "So if there were no Hyperbridge, which is the underlying infrastructure for HyperFX, then these two people would not be able to trade with each other."
Lanlege likened building cross-chain bridges to laying railway tracks. Early crypto bridges relied on centralized middlemen that frequently got compromised—a vulnerability that led his company, Polytope Labs, to build Hyperbridge using decentralized cryptographic proofs.
The last mile: Nigeria's banks
Even with better on-chain rails, the last mile into Nigeria's banking system remains hostile. Looking ahead three to five years, Obiefule warned that B2B cross-border payments will not reach full scale until local fiat off-ramps—the points where digital dollars convert back into spendable naira—match regulatory rhetoric.
"Nigerian banks still do not process crypto transactions," Obiefule said. "I know we speak a lot of English around crypto is no longer illegal, and this and that, but if you want to try it now, you can send me 5,000 naira and in a narration put 'stablecoin' or 'crypto'. You know what's going to happen."
On-chain intra-African foreign exchange
While Esiagu hopes the next five years will see stablecoins rescue Nigerian creatives and freelancers—who routinely lose international gigs because foreign clients cannot easily pay them—Lanlege is betting on direct, intra-African foreign exchange executed on-chain. Today, moving value between African countries requires routing through foreign correspondent banks—the third-country intermediaries that clear cross-border transfers—or converting into US dollar stablecoins first.
"Once you start to have these local stablecoins come on-chain, then you can actually just swap them directly," Lanlege said, envisioning instant swaps between Nigeria's cNGN and Ghanaian or South African stablecoins. "Because then we kind of stop evaporating value to all these foreign systems, and we get to keep more of that value on the continent and, you know, in the pockets of businesses and individuals that are trading with each other across borders."
Between that vision and today sits the checklist the panelists themselves sketched: banks willing to process a transfer narrated as crypto, interfaces simple enough for the "market women" Esiagu described, and local currency tokens able to meet one another on the same chain. Until those align, the heavy lifting stays where it already is—in trading plazas, settlement desks, and the bridges connecting Africa's fragmented liquidity.

