Stablecoins in 2026: Key Data on Market Size, Usage and Payments
Key Takeaways
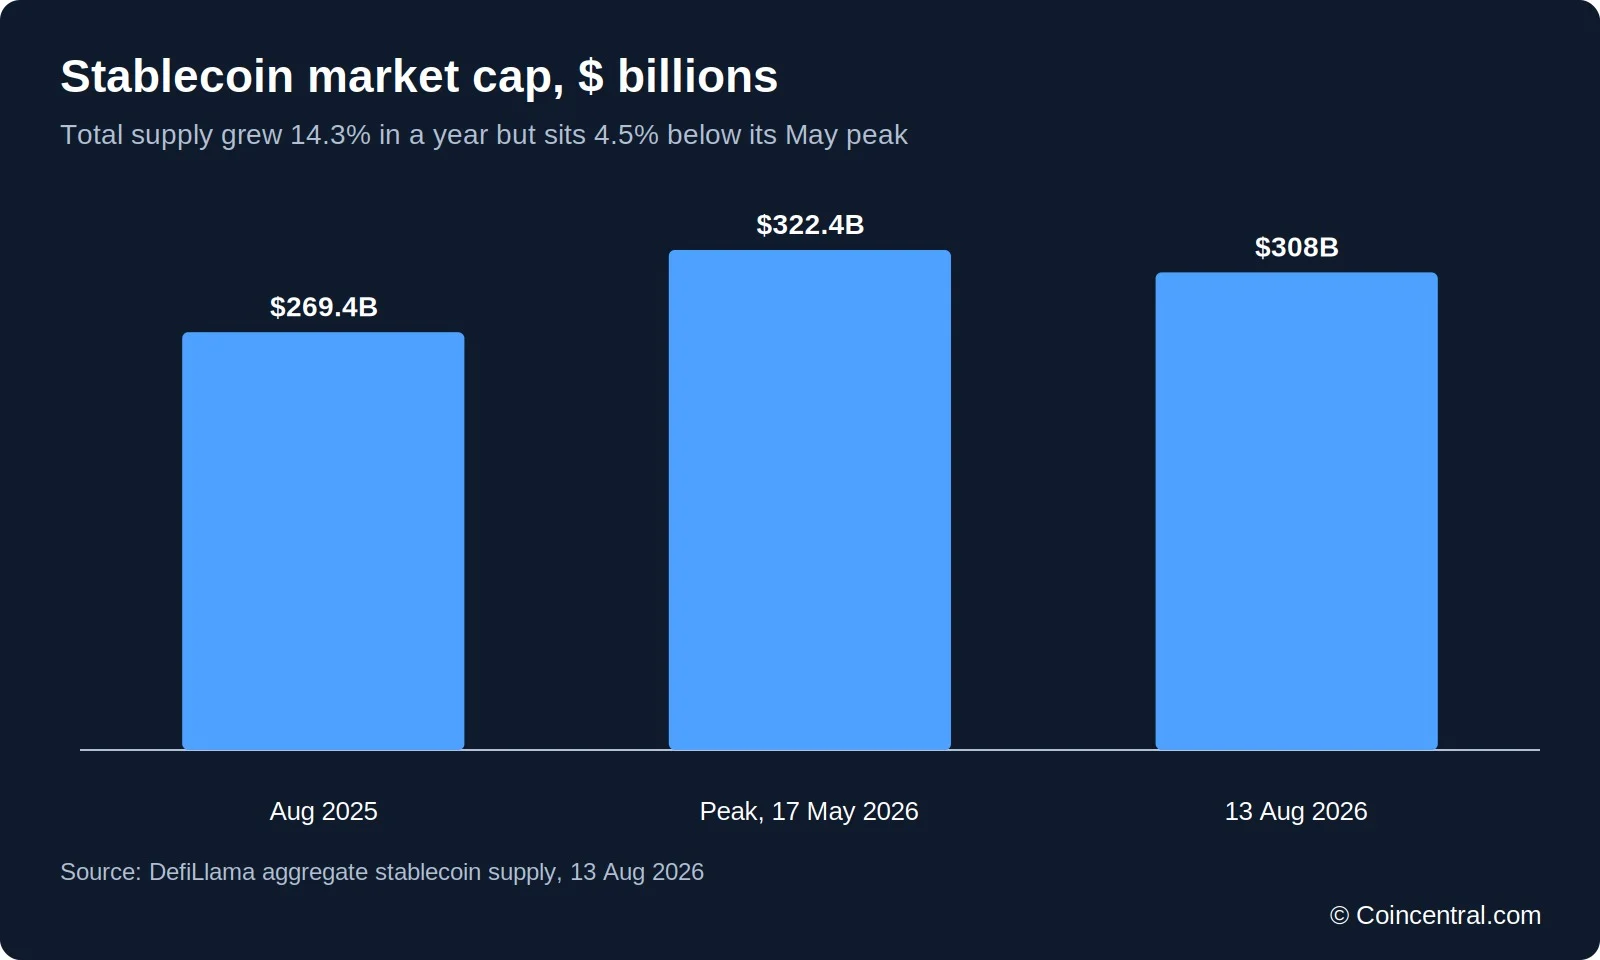
- •Total stablecoin supply stood at $308.0 billion as of 13 August 2026, a 14.3% year-over-year increase but 4.5% below the May 2026 peak after a June and July pullback.
- •Tether's USDT and Circle's USDC together hold roughly 82% of stablecoin supply, and dollar-denominated tokens account for about .5% of the market.
- •Genuine payments for goods and services were estimated at $350 billion to $550 billion in 2025, a small fraction of gross on-chain transfers that ranged up to more than $62 trillion.
- •The US GENIUS Act cut the value of listed incumbent payment firms by about 18%, or roughly $300 billion, with cross-border payment firms falling the most at about 27%.
- •Forecasts project the stablecoin market to reach $1.9 trillion to $4 trillion by 2030, with business-to-business use expected to drive about 85% of future value.
Stablecoins are digital tokens engineered to hold a steady value, most often pegged to one US dollar. Conceived as tools for crypto traders, by 2026 they have become plumbing for businesses, banks and payment firms moving money around the world. This article gathers the key numbers on the market. Figures are as of 13 August 2026 unless stated otherwise, and where sources disagree, both figures are shown. Aggregate supply data is from DefiLlama as of 13 August 2026.
1. Market Size and Growth
Total stablecoin supply stood at $308.0 billion on 13 August 2026, according to DefiLlama, up from $269.4 billion a year earlier — growth of 14.3% over twelve months. Supply peaked at $322.4 billion on 17 May 2026 and now sits 4.5% below that high, flat for the year to date after a pullback concentrated in June and July.
Other trackers report slightly different totals because of timing and counting conventions. One report put the market at $312 billion in October 2025, while Statista listed $292.75 billion for July 2026. Stablecoins represent about 13% of the crypto market by value in one source's figures and roughly 10% in Statista's count. About 269 million on-chain addresses hold a stablecoin balance, according to rwa.xyz.
Stablecoin supply has decoupled from crypto prices. It fell more than 30% in the last bear market but has held near record levels through the 2026 downturn.
2. Tether and USDC Lead the Market
Tether's USDT holds about 59% of stablecoin supply and USD Coin (USDC) is second at about 23%, giving the pair roughly 82% of the market combined, according to DefiLlama. With more than four-fifths of supply concentrated in two tokens, the reserve disclosures in section 7 function as a stability check for the whole market. The picture shifts when volume is the yardstick: USDT accounts for about 74% of stablecoin trading volume on centralised exchanges, yet USDC led on adjusted transaction volume in 2025 at $18.3 trillion against $13.3 trillion for USDT, per Artemis data reported by Bloomberg.
Statista counts 213 stablecoins worldwide, and only two have passed $10 billion in market value — the rest of the field is small.
The US dollar dominates denominations. About 99.5% of supply is dollar-denominated, a figure the BIS puts at 99.4%. Non-dollar stablecoins reached a record of only about $2 billion, up roughly 42% in 2026. Euro stablecoins total about 450 million to 500 million euros, with issuers including Circle (EURC), Societe Generale Forge (EURCV) and Banking Circle (EURI), all authorised under the EU's MiCA rules, according to the ECB.
3. Which Blockchains and Regions Carry Stablecoins
Ethereum carries the most stablecoin supply at about 49%, with Tron second at about 31%; together they hold roughly 79% of all supply. Solana has about 5% and BNB Chain about 4%, Hyperliquid about 2%, while Base, Arbitrum and Polygon hold about 1% each.
Payments tell a different story. Tron carries 60% to 80% of real-economy flows, though its share fell from about 74% in January 2025 to about 60% by the end of the year as regulated volume moved Ethereum, Solana, BNB Chain and Polygon.
Asia is the largest region for stablecoin flows at $12.5 trillion in 2025, up 67% from a year earlier, according to CoinDesk. Latin America is the fastest-growing region for real-world use, driven by inflation protection and remittances, and most stablecoin flows happen outside the United States. In South Asia, stablecoin-driven crypto volumes rose 80% to $300 billion between January and July 2025, according to a Hinkal report citing industry data.
Statista shows 60.72 million monthly active addresses, up 5.98% in 30 days, and 295.65 million holders, up 2.75%, with monthly transfer volume of $6.28 trillion, down 25.19% over the same period. Wallet counts vary by method: rwa.xyz counts about 269 million addresses holding a balance, while Hinkal cites more than 500 million unique wallet addresses by Q3 2025, up from 350 million in 2023.
4. Transaction Volume: How Much Is Real Payments?
Raw on-chain volume looks enormous. Estimates of gross stablecoin transfers in 2025 range from about $28 trillion (BIS) to $33 trillion (Artemis) to more than $62 trillion (BCG and Allium), with the gap explained by different rules on what to count.
Most of that volume is not spending but trading, bot activity and funds moving between wallets and exchanges. BCG estimates only about 7% of transfers, or $4.2 trillion, was genuine economic activity. Real payments for goods and services were far smaller: BCG puts them at $350 billion to $550 billion in 2025, up about 60% from the year before, while McKinsey and Artemis estimate about $390 billion — under 1% of total transfer volume. Statista reports annualised stablecoin payment volume of $390 billion at the end of 2025, of which business-to-business payments were $226 billion, or 58%.
Some monthly totals remain striking. Stablecoins settled $7.2 trillion in February 2026, passing the US ACH network — the batch system that moves much of America's everyday payment traffic, from payroll to direct deposits — at $6.8 trillion for the first time, and March reached $7.5 trillion. Estimates differ because blockchains record how value moves, not why, forcing researchers to infer the purpose of each transfer.
5. Net Inflows and Outflows
Net flows measure new tokens minted minus tokens redeemed: rising supply means money is entering the stablecoin system, while falling supply means it is leaving. Supply shrank in June and July 2026, then steadied in August. June was the weakest month with an outflow of $8.04 billion, and the monthly figures net out to roughly zero for the year so far.
The total masks issuer-level divergence. Over the 30 days to 13 August, Global Dollar (USDG) grew fastest among the ten largest tokens at 17.2%, while World Liberty Financial USD (USD1) fell the most, by 9.0%. USDT lost 0.7% and USDC lost 1.2%.
Traders also watch the Stablecoin Supply Ratio (SSR), which compares Bitcoin's market value with stablecoin supply; a lower number means more stablecoin buying power relative to Bitcoin. SSR was about 4.16 on 13 August 2026, calculated from a Bitcoin value of about $1,281.7 billion (CoinGecko) and stablecoin supply of $308.0 billion — a derived figure, not one taken from a single source.
6. Payments, Cards and Business Adoption
Spending on stablecoin-linked cards reached about $18 billion on an annualised basis in late 2025 and early 2026, close to peer-to-peer transfers at about $19 billion. Card spending has grown about 106% a year since January 2023. Other sources use different definitions: Statista reports $4.5 billion in stablecoin-linked card spending for 2025, up 673% from $582 million in 2024, while Visa reported annualised stablecoin figures of $3.5 billion in late 2025 and $4.5 billion in settlement volume in January 2026.
Business-to-business payments grew from under $100 million a month in early 2023 to over $6 billion a month by mid-2025, and consumer-to-business payments grew 131% in 2025. The average stablecoin peer-to-peer transfer was $47, compared with $250 for a traditional remittance.
Cost and speed drive much of the interest. Sending money across borders still costs 6.49% on average (World Bank, Q1 2025), well above the G20 target of 3%, while stablecoin transfers run about 40% cheaper once total costs are counted, according to BVNK. Only 35% of retail cross-border payments reach the recipient within an hour, against a G20 target of 75%; stablecoin transfers usually settle in minutes or seconds.
An EY-Parthenon survey of 350 corporate and financial-institution leaders gives a view of business use. Run in mid-2025 before the GENIUS Act was signed, it is a snapshot rather than live market share.
7. Reserves and Stability
What backs a stablecoin differs by issuer. Tether reported about $141 billion in direct and indirect US Treasury bill exposure at 31 March 2026, which it says makes it the 17th largest holder of US Treasuries. Circle holds about one-third of USDC reserves in Treasuries, with the rest in overnight repo and cash, while Gemini's GUSD is backed fully by bank deposits. Circle holds USDC reserves in the Circle Reserve Fund, an SEC-registered money market fund managed by BlackRock with BNY Mellon as custodian; Deloitte & Touche is Circle's independent auditor.
Tether's cushion has shrunk. At 31 March 2026 it had $191.77 billion in assets against $183.54 billion in liabilities, leaving $8.23 billion in excess reserves; by 30 June, assets were $187.75 billion against $183.64 billion, leaving $4.11 billion. Excess reserves — the gap between what an issuer holds and what it owes holders — are the buffer that absorbs losses if reserve assets fall in value.
Issuers as a group now rank among the top 20 foreign holders of short-term US Treasuries. Hinkal reports that Tether and Circle together held $177.6 billion in Treasury exposure at the end of Q2 2025, and tokenized Treasury funds add more: Circle USYC holds about $3.0 billion and BlackRock BUIDL about $2.7 billion.
Stability is not guaranteed. In March 2026, the stablecoin ResolvUSD (USR) was exploited for about $80 million, fell as low as $0.14 and saw its market value drop 55.9% to about $49 million. Regulators note that stablecoins often act more like exchange-traded fund shares than cash: they can drift from par, and redemption can be slow.
8. Regulation and the Market Reaction
Investors treated the US GENIUS Act — the federal stablecoin law signed in 2025 — as a real threat to payment firms. An IMF study found the law cut the value of listed incumbent payment firms by about 18%, or roughly $300 billion, with cross-border payment firms falling the most at about 27%, while card networks and crypto-focused firms were largely shielded.
The hit was larger than earlier rule changes. The Durbin Amendment cut firm values by 5.3%, and an expected digital euro was linked to an 11.6% drop for US firms For scale, the 35 listed US payment firms in the study were worth about $1.5 trillion in 2024 — about 77% of the market value of all listed US commercial banks.
Other markets are moving too. Singapore's framework is live with 6 to 8 issuers. Japan passed rules first, and JPYC launched in October 2025. South Korea has a framework but no dedicated stablecoin law, and China keeps a full private ban. Major regimes share three themes: full reserve backing, redemption at par and a ban on paying interest to holders. In the US, reserves must be held one-to-one in cash and short-term Treasuries, with monthly audited disclosures.
Regulators are paying attention. Mentions of "stablecoin" in US SEC filings rose to 2,298 in 2025 from 586 in 2024. In early 2026, 44% of market participants named regulation and compliance as the main bottleneck for scaling tokenized assets.
9. Tokenized Real-World Assets
Stablecoins sit beside a growing set of tokenized real-world assets. Total on-chain value was about $25 billion by DefiLlama's count and $29 billion to $31 billion by rwa.xyz in mid-2026, with the difference coming from what each tracker includes. Roughly 50% to 55% of tokenized assets are US Treasuries, commodities make up about 34% and stocks about 7%, according to CoinDesk Data. Holders reached about 949,000, up about 13% in 30 days (rwa.xyz).
Tokenized Treasuries grew to about $12 billion to $15 billion in 2026, from $8.9 billion at the start of the year. Circle USYC and BlackRock BUIDL are the two largest funds, each at about $2.4 billion to $3.0 billion, and USYC passed BUIDL for the top spot in early 2026. Tokenized gold reached about $3.2 billion for Tether Gold (XAUt) and $2.3 billion for Paxos Gold (PAXG). Tokenized equities remain small at about $1.1 billion, up about 46% in March 2026, led by xStocks. Deutsche Bank Research describes three forms of digital money emerging side by side.
10. The Outlook: Forecasts to 2035
Forecasts point to steady growth but vary widely. Financial institutions expect stablecoins to handle 5% to 10% of global payments by 2030, equal to about $2.1 trillion to $4.2 trillion a year. Citi projects the total stablecoin market at $2 trillion to $4 trillion by 2030, while Hinkal cites a base case of $1.9 trillion and an aggressive case of $4 trillion; today's market is $308 billion.
About 85% of future stablecoin value is expected to come from business-to-business use, building on today's B2B base of about $226 billion a year, according to McKinsey. Stablecoins still make up less than 1% of global cross-border payments.
Established firms are building their own rails. Visa, Mastercard, Stripe and Coinbase are backing a new stablecoin platform, and Japan's three megabanks plan a joint yen stablecoin by 2027. Speed is one draw: FXC Intelligence says stablecoins can settle up to 500 times faster than traditional systems on some routes. Privacy is a concern, since every transfer on a public blockchain shows the sender, recipient and amount.
What the Numbers Show
The data depicts a market that is large, concentrated and still growing. Supply is above $300 billion, two issuers hold most of it, and the dollar is almost the only currency in use. It also shows a gap between volume and use: trillions of dollars move on chains, but real payments amount to a few hundred billion. Regulation, reserves and business adoption will decide how fast that gap closes. Signals worth tracking from here include monthly net flows, issuer-level shifts among the largest tokens and the monthly reserve disclosures US law now requires.
Readers should treat forecasts with care. Sources use different definitions, dates and methods, so the same topic can produce several figures. Checking how each number was built is the best way to use this data.
Sources
- DefiLlama, Stablecoins dashboard (supply, chains, flows)
- Bank for International Settlements (BIS), stablecoin research
- International Monetary Fund (IMF), Stablecoins and the Future of Payments: Evidence from Financial Markets
- Artemis Analytics, stablecoin transaction data
- Bloomberg, reporting on Artemis stablecoin volume
- Boston Consulting Group (BCG) and Allium, stablecoin payments analysis
- McKinsey & Company, stablecoin payments research
- CoinDesk Data, Global Digital Asset Adoption Index and tokenized asset data
- rwa.xyz, tokenized real-world asset data
- Tether, transparency and attestation reports (BDO)
- Circle, USDC transparency and reserve reports
- Gemini, GUSD attestation reports
- World Bank, Remittance Prices Worldwide
- EY-Parthenon, 2025 stablecoin adoption survey
- European Central Bank (ECB), euro stablecoin research
- Visa, stablecoin settlement updates
- Statista, Stablecoin statistics and facts
- Hinkal, 15 Cross-Border Stablecoin Statistics 2026 (April 2026)
- FXC Intelligence, cross-border payments market data
- Deutsche Bank Research, digital money research
- CoinGecko, Bitcoin market capitalisation
- Citi, stablecoin market forecast
This article is based on reporting first published on CoinCentral: Stablecoin Statistics 2026: Market Size, Usage and Payments.

