Swiss National Bank Board Member Sees Large Stablecoins as a Burden on Monetary Policy
Key Takeaways
- •SNB Governing Board member Petra Tschudin said in late September 2026 that large stablecoins detached from the two-tier financial system would hamper monetary policy transmission and raise the burden on central banks.
- •The mechanism runs through bank deposits: shifts into stablecoins reduce commercial banks' funding and lending, making the SNB's policy rate less effective at steering borrowing costs.
- •Tschudin argued that a stablecoin franc is not automatically worth the same as a real franc, because its value depends on the issuer rather than the central bank.
- •The SNB's 2026 Financial Stability Report currently classifies stablecoins in Switzerland as a niche phenomenon posing no risk to financial stability, while flagging volatile backing and possible deposit outflows as weaknesses.
- •Switzerland still lacks a framework for franc stablecoins: under the FINIG revision draft, only FINMA-licensed payment instrument institutions may issue them, with the Federal Council's dispatch expected in the second half of 2026 at the earliest.
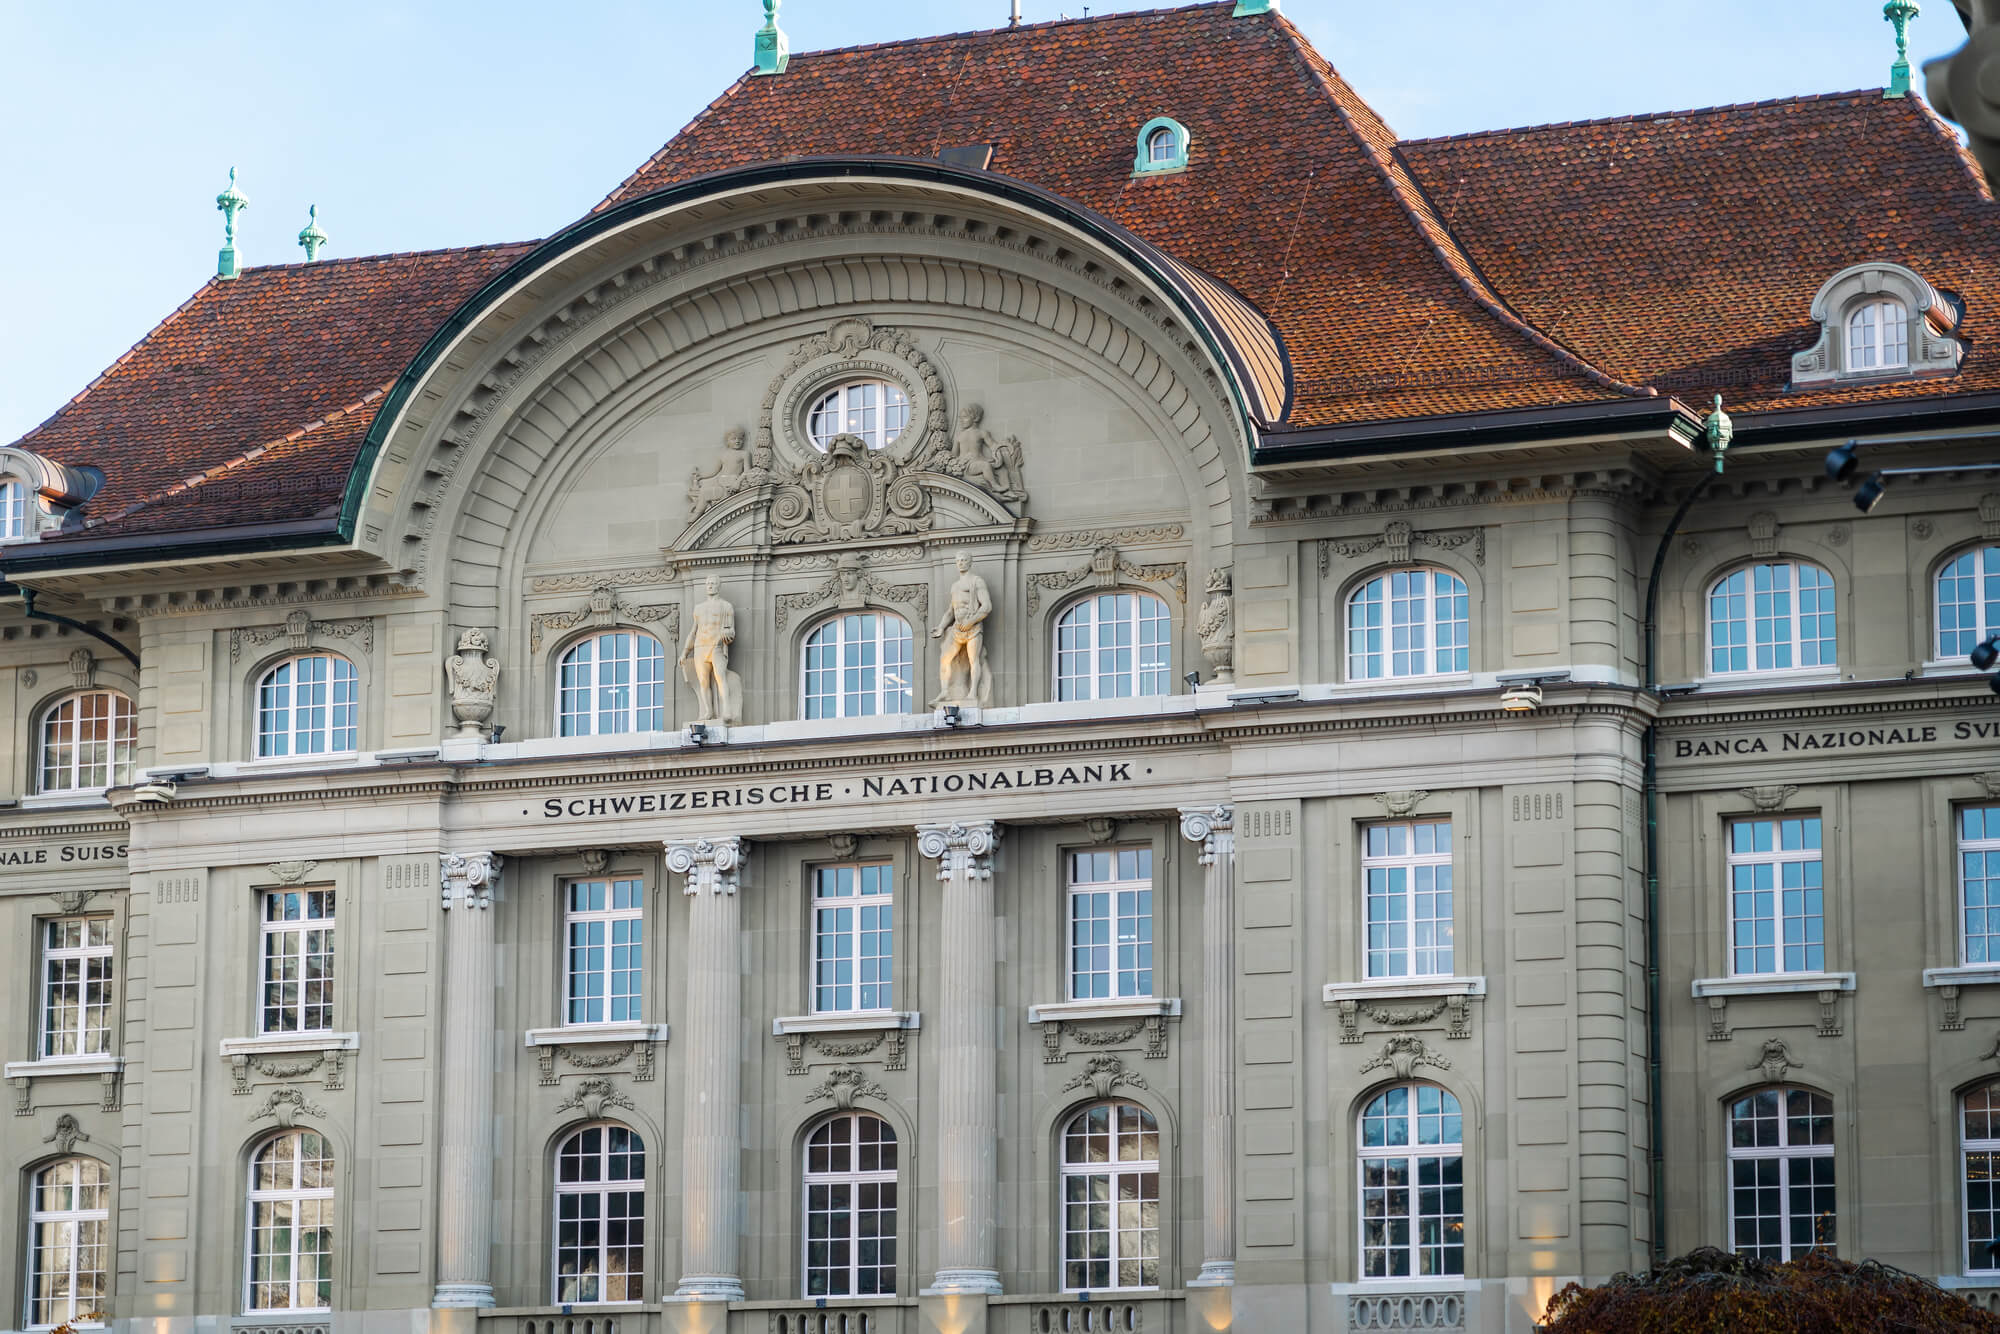
Petra Tschudin, a member of the Governing Board of the Swiss National Bank (SNB), views large stablecoins as a burden on monetary policy. In her assessment, stablecoins that lack a link to the two-tier financial system make monetary transmission harder and increase the burden on central banks.
The SNB is Switzerland's central bank, and its mandate is to ensure price stability. To achieve this, it steers the money market through its policy rate, an impulse that then reaches the economy through bank loans and interest rates. Economists refer to this path as transmission. Under the two-tier system, the central bank first issues central bank money, and commercial banks then pass it on to households and companies. Stablecoins, by contrast, are private tokens — usually pegged to the US dollar or the Swiss franc — that circulate outside this system.
Tschudin presented her analysis in late September 2026 at the forecasting conference of KOF, the economic research institute of ETH Zurich. The appearance followed the central bank's decision to devote a special topic to stablecoins in its 2026 Financial Stability Report.
How stablecoins weaken the SNB's interest rate channel
The mechanism behind the warning starts with bank deposits. If households and companies move money from their bank accounts into stablecoins, commercial banks lose part of their funding. As a result, bank lending volumes fall, and interest rates are affected as well. If the central bank later changes its policy rate, the move works less directly, because it steers borrowing costs less effectively. The strength of monetary policy therefore depends on deposits that stay in the banking system. That is why the SNB's warning targets scale: not stablecoins as such, but large ones circulating far from the two-tier system.
Tschudin's presentation slides address large stablecoins and their missing link to the two-tier financial system. According to the slides, both hamper "among other things, the transmission of monetary policy."
The board member is describing a scenario, however, not a current disruption. In her account, the burden on central banks rises only if large stablecoins emerge far removed from the existing system. At the same time, the SNB does not reject new developments: it welcomes innovation in payments if it makes them safer and more efficient, and it considers modernizing the two-tier system sensible. "When we introduce innovations, we really need to ask what consequences they have, and how they should be regulated," Tschudin said. In her view, design and regulation are therefore decisive, and private forms of digital money must not jeopardize the SNB's ability to fulfill its mandate.
Why a stablecoin franc is not automatically a franc
The SNB's second objection concerns the uniformity of money. Because stablecoins operate outside the central bank system, a stablecoin franc is, following Tschudin's argument, not automatically worth the same as a real franc. This puts pressure on the principle that money is uniform everywhere, and it means the value of such a token depends on the issuer rather than on the central bank.
"If we end up with big stablecoins that are really far removed from the existing two-tier financial system, then that's a situation which increases the burden on central banks in fulfilling their mandate," said Petra Tschudin, member of the SNB Governing Board.
The quote refers to tokens that move far away from the existing system, so Tschudin is setting a narrow condition. In addition, the SNB worries about settlement between banks: commercial banks settle their claims with each other in risk-free central bank money, and large stablecoins could affect this foundation. Notably, the central bank frames its criticism around integration and regulation rather than calling for a ban. For future franc stablecoins, this sets clear standards: close integration with the two-tier system and effective regulation.
In its own report, the SNB calls stablecoins a niche phenomenon
The central bank's assessment of the current situation is comparatively sober. In its 2026 Financial Stability Report from the summer, the SNB describes stablecoins in Switzerland as a "niche phenomenon" that currently poses no risk to financial stability. The tokens are "typically pegged to established currencies such as the US dollar or the Swiss franc," the report says, and so far they play only a minor role in Swiss payments. Several banks and financial companies are working on a project for a digital franc, which — according to the news agency AWP — is still only in the testing phase.
Nevertheless, chapter 5.1 of the report names specific weaknesses. These include volatile backing, which can make redemption at par harder, and interconnection with the rest of the financial system. Moreover, a large outflow of bank deposits into stablecoins could amplify instability in the banking sector during a crisis — precisely the outflow that forms the starting point of Tschudin's transmission chain. The report thus describes the current state, while speech outlines the scenario of wider adoption.
Furthermore, the SNB considers international coordination of regulation important, since issuers could launch stablecoins in less regulated jurisdictions that then see wide use in Switzerland. The United States shows how differently the timelines can run: the US President signed the GENIUS Act — short for Guiding and Establishing National Innovation for U.S. Stablecoins Act — in July 2025, but the law only takes effect 120 days after the final implementing rules, and no later than January 18, 2027. As of spring 2026, those rules still existed only as drafts.
Helvetia and the FINIG revision set the Swiss framework
The central bank offers its own alternative to the private tokens. Since December 2023, it has been testing a central bank digital currency in Project Helvetia Phase III. The test targets financial institutions and runs on SIX Digital (SDX). Six banks originally took part: Commerzbank, BCV, Basler Kantonalbank, Hypothekarbank Lenzburg, UBS and ZKB. At the end of June 2025, the SNB extended the project until at least mid-2027 and added an RTGS (real-time gross settlement) link, which allows tokenized assets to settle in SNB money via the SIC payment system, Switzerland's interbank clearing system. BX Digital is also getting a production connection to SIC. According to the SNB, however, the extension is not a commitment to introduce wholesale CBDC permanently.
Meanwhile, the federal government is working on the legal framework. In October 2025, the Federal Council opened the consultation on the revision of the Financial Institutions Act (FINIG), which ended in early February 2026. The draft provides for two new license categories: the payment instrument institution and the crypto institution. The payment instrument institution replaces the existing fintech license. Under the new rules, client funds can be segregated in bankruptcy, and the CHF 100 million limit no longer applies. In the future, only a payment instrument institution licensed by FINMA — Switzerland's financial market supervisory authority — may issue Swiss stablecoins.
Yet it will take time before this framework applies. The Federal Council's dispatch will come in the second half of 2026 at the earliest, and no publication is known so far. After that, parliament still has to debate the bill, and a possible referendum period follows. The SNB board member is thus issuing her warning at a time when Switzerland still lacks a framework for franc stablecoins. The dates to watch are already on the record: the Federal Council's dispatch, due in the second half of 2026 at the earliest; the final US implementing rules that start the GENIUS Act's clock, with the law taking force no later than January 18, 2027; and Project Helvetia, extended until at least mid-2027.

