Six Years After Stripe Acquisition, Paystack Is Learning to Keep Money
Key Takeaways
- •Stripe acquired Lagos-based Paystack for $200 million in October 2020, the largest acquisition of a Nigerian startup at the time, when the company had 60,000 customers.
- •Paystack led the purchase of struggling business banking startup Brass in May 2024, launched its first consumer app Zap in March 2025, and was fined ₦250 million by the Central Bank of Nigeria in April 2025 for running Zap as a wallet under a payments-only licence.
- •In January 2026, Paystack bought Ladder Microfinance Bank and created holding company The Stack Group, giving it the ability to take deposits, lend, and earn interest income beyond transaction fees.
- •Paystack says its payment volume has grown more than twelvefold since 2020 and that the group is profitable.
- •Unlike agent-network rivals such as Moniepoint, which serves more than 6 million active businesses in person, Paystack lacks a physical footprint and is counting on migrations of Brass and Allawee customers to Paystack MFB to build its deposit base.
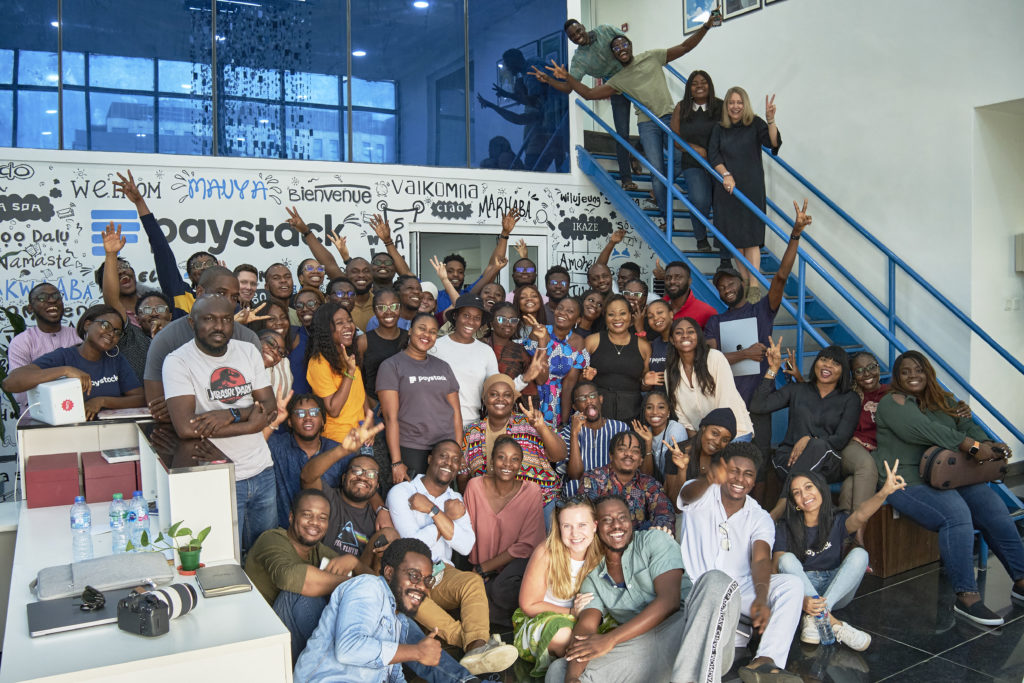
In October 2020, Stripe agreed to acquire Paystack, a Lagos-based startup that helps businesses accept payments online, for $200 million—at the time the largest acquisition of a Nigerian startup. Paystack had 60,000 customers when the deal was announced.
Stripe said the acquisition would fund new products and help pull together Africa's fragmented payments market, and that Paystack would continue operating independently. Shola Akinlade, the company's chief executive, promised more countries, more payment channels, and more services. Six years after the acquisition, he has delivered on that promise.
At the time, Paystack made money by taking a cut of every online payment a business collected—a model that depends on scale. It charges 1.5% plus ₦100 per transaction, capped at ₦2,000, meaning a ₦10,000 order earns it ₦250, roughly 19 cents.
That model generates income only while money is moving. A bank that holds customers' money works differently: it can lend or invest those balances at a higher rate than it pays for them, and that income continues for as long as the balances stay—whether or not transactions occur.
Brazil's Nubank shows how powerful that can be. It ended 2025 with $41.9 billion in deposits, funded itself at 87% of the interbank rate, and made $2.9 billion. Worldwide, interest accounted for 46% of payments revenue in 2024, according to McKinsey.
Six years on, the company Stripe bought has changed shape. It now owns a microfinance bank and a consumer app. Its path illustrates why African fintechs keep turning into banks—and how hard the final step is.
Paystack first became bigger and more exposed
Paystack spent Stripe's backing on reach. It now serves businesses in Côte d'Ivoire, Ghana, Kenya, Nigeria, and South Africa, with approvals in Egypt and Rwanda, and it hired wherever talent was available, including an engineering hub in Dubai.
Over time, that reach brought more payment volume, but also costs in dollars set against income in weaker African currencies. By November 2023, the naira had lost more than half its value since June of that year, and the Kenyan shilling had fallen almost 20% over twelve months. What Paystack earned from moving money fell sharply in dollar terms even as it grew in local currencies. In response, it laid off 33 employees in Europe and the UAE.
That same year, bank transfers accounted for 34% of the company's payments in Nigeria, its biggest market, up from 12% in 2021. Paystack had added a pay-with-transfer option in 2020, and the growth showed customers had come to prefer transfers because they were cheap and reliable.
Paystack followed the money. By 2023, it had launched Virtual Terminal, which gives a shop a Paystack-Titan bank account for customers to transfer into. That put large sums into accounts carrying Paystack's name—but the interest on those balances went to Titan Trust Bank.
Brass shows Paystack the value of deposits
In May 2024, Paystack led a group that bought Brass, a business banking startup. Brass had struggled to pay out withdrawals since October 2023, and two people said it had a ₦2 billion ($1.5 million) hole in its books. The buyers stepped in because they feared a collapse would send customers running from other fintechs.
It was Paystack's first known stake in a business that held other people's money. Along with Brass's business customers, it offered a close view of what happens when deposits run short.
Ten months later, in March 2025, Paystack launched Zap, its first consumer app, with deposits held at Titan.
By the end of April, the Central Bank of Nigeria had fined Paystack ₦250 million. A with knowledge of the matter said the regulator found that Zap was being run as a wallet, which Paystack's licence did not cover. The company held only a payments licence, which allows it to move money between other people's accounts. Holding that money—even briefly, in a balance a customer can spend later—requires a different licence. Zap looked like a wallet; Paystack had permission for payments.
Paystack had already decided it wanted to hold customers' money. The fine showed it could not do so on a payments licence in the way Zap first worked. Zap later won regulatory approval, and in January 2026, Paystack bought a bank.
Paystack turns into a group
In January 2026, Paystack bought Ladder Microfinance Bank and said Paystack MFB would lend to businesses first, then to individuals. Days later, it created a holding company, The Stack Group, a structure that keeps separately licensed businesses under one owner. Paystack said its payment volume had grown more than twelvefold since 2020 and that the group was profitable.
In June, Brass said it would close as a standalone business and move its customers into Paystack MFB. In August, Allawee, a card company Paystack quietly bought in 2025, told customers their accounts would close on 1 December and that they must open new ones with Paystack.
The microfinance licence lets Paystack take deposits, lend, and earn interest, so it depends less on fees.
Against incumbents, though, Paystack starts with a deficit. Moniepoint says it serves more than 6 million active businesses in person. OPay and PalmPay were built the same way, through agent networks that put a physical point of contact in markets, shops, and streets across Nigeria. An agent signs up a trader, handles their cash, and becomes the reason that trader keeps a balance with a fintech instead of a bank.
Paystack has no comparable footprint. Its strength was always online checkout, where a business integrates once and the relationship runs entirely online. Its card machine never matched the agency banking networks, so the daily, in-person habit that turns a payments customer into a depositor was never built.
That is why Paystack MFB has to win deposits one account at a time, and why it bought Brass and Allawee. Each acquisition brings business accounts that already exist, which is faster than recruiting them. Both migrations are already scheduled: Brass's customers are due to move into Paystack MFB, and Allawee's must open new Paystack accounts before their old ones close on 1 December—making them the first visible measure of whether acquired accounts become staying deposits.
In 2020, Stripe bought a company that moved money quickly. Paystack's next test is how much of that money it can persuade to stay.
Source: TechCabal

