Grey Launches Paycheck Salary Account for Remote Workers as Cross-Border Fintech Nears $5 Billion Lifetime Volume
Key Takeaways
- •Grey launched Paycheck, a salary account for professionals earning in US dollars, British pounds, and euros, at TechCabal's Moonshot 2026 conference.
- •The company has processed nearly $5 billion in lifetime total payment volume across more than 40 million transactions for over 3 million users in 70 countries.
- •Paycheck salary account holders receive an introductory 3% annual savings interest rate, alongside perks such as 1% cashback on card spend, eSIM data packages, and upcoming physical USD cards.
- •Grey underwrites credit based on the regularity of customer earnings and carries no balance-sheet risk, partnering with licensed lenders for phased, jurisdiction-specific rollouts.
- •Grey Business, launched in early 2026, surpassed $100 million in processed volume and helped drive overall TPV growth of 170% to 175% year-on-year.
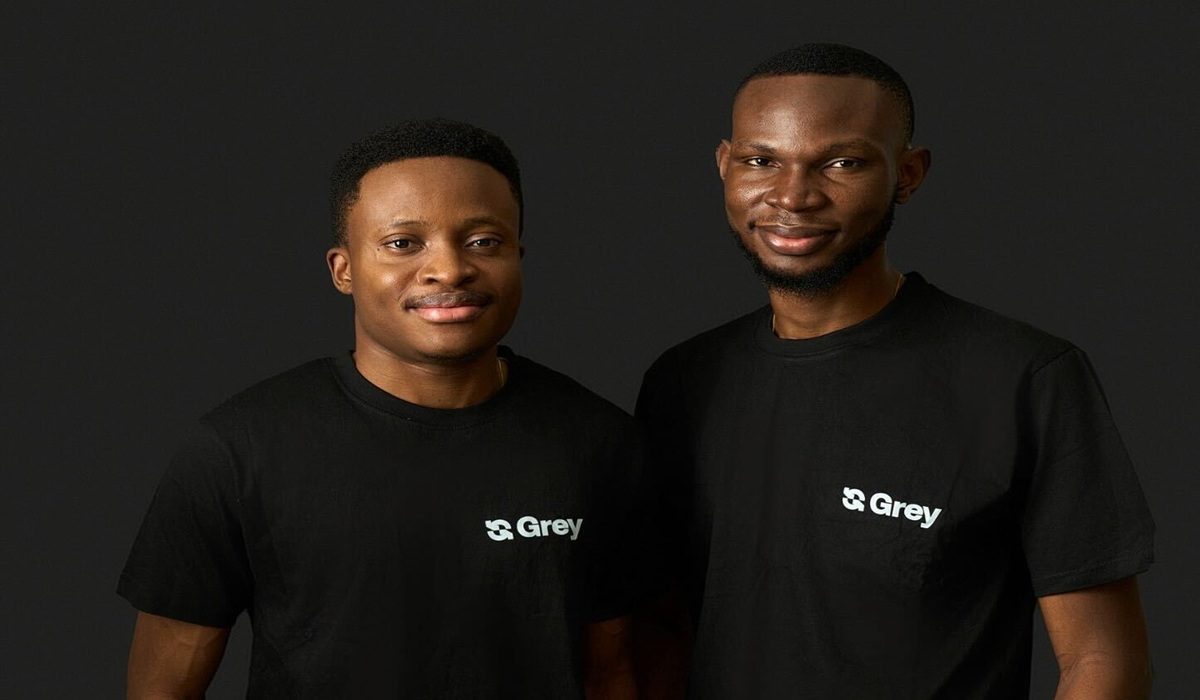
African cross-border payments company Grey has launched Paycheck, a dedicated salary account for professionals earning in US dollars, British pounds, and euros, as it moves to become the primary financial operating system where remote workers save, borrow, and spend.
Idorenyin “Idee” Obong, CEO and co-founder of the Y Combinator-backed startup, unveiled the product on stage at TechCabal’s flagship Moonshot 2026 conference on Wednesday. Alongside the announcement, he revealed that Grey has quietly processed nearly $5 billion in lifetime total payment volume (TPV) — a cumulative measure of all transaction value processed rather than revenue — across more than 40 million transactions for over 3 million users in 70 countries. Obong co-founded the company with Chief Operating Officer Joseph Femi Aghedo.
The launch marks a deliberate break from the pattern that has defined African cross-border fintech for the past five years. Whether a software engineer in Lagos or a product designer in Nairobi earned in dollars, pounds, or euros, user behaviour remained stubbornly uniform: the moment a foreign invoice cleared, the user swapped the hard currency and cashed out into a local commercial bank account. Platforms built impressive gross transaction volumes on those foreign exchange spreads, yet captured almost none of the long-term deposit float. Obong’s keynote was aimed squarely at killing that transit-pipe reflex.
“When we started Grey, it was a pure currency exchange product,” Obong told Technext in an exclusive one-on-one interview immediately following his keynote. “We then evolved it into what it is today, and we’ve been very intentional about not being a pass-through.”
While the official launch announcement highlights automatic salary sorting, fee-free incoming payroll, monthly reward draws, and priority support, the conversation with Obong revealed a much deeper architectural play. Beneath the consumer-facing perks lies a calculated push into algorithmic credit underwriting, off-balance-sheet lending partnerships, physical card fulfilment, and a closed-loop business-to-business-to-consumer payroll rail.
Solving the remote worker’s credit blind spot
Across emerging markets, remote tech talent and digital creators occupy a strange financial paradox. They often earn multiples of local corporate salaries in foreign currency, yet domestic commercial banks and traditional credit bureaus often cannot see them. Because their inflows sit on offshore fintech rails rather than local salary schemes, securing a domestic loan or even a simple overdraft is nearly impossible. It is the gap Grey is building against: the platform that receives the salary holds the earnings history conventional underwriting never sees.
“The problem we have seen is that people who use our product to receive their salaries oftentimes don’t have access to credit,” Obong explained. “Why? Because the standard credit bureaus hardly underwrite foreign currency via another bank. And so this is data and intelligence we’ve built over the last six years to underwrite customers better than anyone else.”
Underwriting remote workers, however, carries a glaring structural risk: global gig work and offshore contracts can terminate abruptly, and invoice cycles fluctuate. When pressed by Technext on how Grey’s proprietary “income intelligence” separates a stable remote salary from a volatile freelance gig, Obong drew a firm line between Paycheck as a salary-sorting layer and the underlying credit scoring engine.
“First, we need to separate Paycheck from our credit product,” he clarified. “Paycheck is a service for salaried employees where we offer them perks in addition to receiving their salary today. One of those perks is higher interest rates for savings; another is credit.”
To price the risk of sudden contract loss or erratic inflows, Grey treats its internal ledger like a high-frequency bank statement analyser. The regularity of a customer’s earnings, rather than the size of any single payment, drives the underwriting decision.
“From our data, we can underwrite these customers to know how much risk and exposure they can take on in getting a loan or an overdraft with Grey,” Obong explained. “It’s just like with any other lending company where you send your bank statement, and the frequency of your earnings tells the risk appetite of that lending company. If you have a customer who is earning every single month in credit, that’s a more suitable customer. You can extend them higher loans versus someone who is less regular.”
Lending in emerging markets has humbled dozens of well-funded fintechs over the past decade through currency mismatches and high default rates. Rather than turning Grey into a balance-sheet lender overnight, Obong confirmed that the company is insulating its own capital entirely during this phase.
“We’re not putting any risk on our balance sheet in offering this product, and that’s why we’re working with very credible lending partners to offer this service,” he said. “It’s just like when we started Grey and wanted to issue banking services. We are not a bank ourselves; we did not immediately start issuing our own accounts in our own name. We had to go through a partner, start building it out, and then look to own the infrastructure much later. That’s the same approach we’re looking at here.”
Letting established lending partners carry the principal risk allows Grey to avoid tying up its own liquidity or getting bogged down by country-by-country banking licences. Because credit and interest-bearing products trigger strict securities and lending rules across different territories, Obong noted that both the credit and yield features will roll out in phased, jurisdiction-specific waves alongside licensed local partners.
Building reasons to stay
Keeping money inside the app requires giving users tangible reasons not to cash out the moment a payment lands. A few weeks before Moonshot, Grey rolled out Pouch, a feature that lets users partition funds into goal-specific savings buckets. With Paycheck, the company is layering an introductory 3% annual interest rate on savings for salary account holders, while non-Paycheck users earn 2%.
The yield arrives in a macro environment where US Treasury yields — the customary baseline for dollar-denominated savings — still hover above 4%, raising the question of whether an introductory rate alone can alter entrenched cash-out habits. Grey’s answer is breadth rather than a single hook: alongside the 3% interest rate, Paycheck bundles 1% cashback reward points on card spend, eSIM data packages for international travellers, co-working workspace passes, crypto investment options in select jurisdictions, and upcoming physical plastic and metal USD cards.
“We don’t think that just one thing is enough; we’re building a holistic ecosystem,” Obong said. “Take a customer living in Lagos, Nigeria, working for a company in the US. They receive their salary and decide to send money to family in another country or save 20% of their paycheque and earn interest on it. If they are travelling, they can use their Grey card to pay for their flight ticket and get an eSIM with Grey when they reach the new country. If their payday came late and they need credit to quickly sort out a problem, we can offer them that credit. The goal is to meet our customers at every important touchpoint.”
On the logistics of shipping physical plastic and metal cards across Africa, Latin America, and Southeast Asia — a vertical notorious for sudden sponsor-bank shutdowns and steep courier costs — Obong emphasized multi-partner redundancy.
“We have multiple banking partners and multiple card partners because we want to avoid our customers being stranded,” he said. “In terms of cost, getting a card shipped to you might cost you something, but it’s something we’re going to make sure is within affordable rates for our customers wherever they are in the world.”
Grey Business accelerates past $100 million
Perhaps the most revealing metric shared on Wednesday was the velocity of Grey Business, the company’s business-to-business arm. Launched in early 2026, the unit processed $61.4 million in its first four months and has now surpassed $100 million in total processed volume, helping propel overall company TPV growth to between 170% and 175% year-on-year. The surge is fuelled by venture-backed startups bridging offshore capital into local operating expenses and by trading SMEs tapping Grey’s newly launched Chinese yuan (RMB) payout rails.
“Grey Business should have come a lot earlier for us as a company,” Obong reflected. “A typical use case is a tech startup that has received funding, but their day-to-day expenses need to be in local currency. We provide that bridge for them. And something very important is the RMB payouts, which we launched because of customer demand. Today we see our customers using our RMB payouts to pay their suppliers.”
A closed payroll loop
Placed side by side — Grey Business’s bulk payout capabilities across more than 170 countries and Paycheck’s consumer salary accounts — a much larger strategic picture emerges: a self-contained payroll network that eliminates third-party intermediaries like Deel or Wise and bypasses correspondent banking fees. When asked if building that closed business-to-business-to-consumer payroll loop is the ultimate endgame, Obong did not hesitate.
“That’s the goal,” he said. “Because today we already have businesses who pay their employees via Grey Personal as well. So that’s a rail and a corridor we intend to drive aggressively in the next few weeks and months.”
Those commitments give observers a concrete checklist for the months ahead: the pace of the Grey-to-Grey payroll corridor, which jurisdictions receive the phased credit and yield launches, and how quickly physical cards reach users across Africa, Latin America, and Southeast Asia.
Six years after starting out as Aboki Africa, Grey is no longer satisfied being the bridge between foreign employers and local bank accounts. By pairing business-to-business treasury rails with salary-backed consumer credit and yield, Obong is betting that the next $5 billion will not simply pass through Grey — it will stay there.

