Glassnode's Book Churn Metric Shows Why Bitcoin's Order Book Depth Can Mislead
Key Takeaways
- •Glassnode's Book Churn metric, built from Binance perpetual futures data backfilled to January 2020, quantifies how often order book quotes are updated, a dimension that depth and spread alone cannot capture.
- •When Book Churn scored 2 or higher, the following hour was more volatile than the median 63% of the time, exceeding the 50% baseline set by chance.
- •A simpler signal based on each window's high-to-low price range edged Book Churn by a fraction of a point, with the two metrics correlating at 0.84, though churn fired in roughly half the windows where the range signal stayed silent.
- •On April 27, BTCUSDT update volumes nearly tripled to between 1.8 million and 2.1 million per ten-minute window while depth and spread remained calm, illustrating how churn can flag activity invisible on standard screens.
- •Glassnode disclosed that the test ran in-sample, 2020 and 2021 results reached only 53% to 57%, and the study covered a single contract on one exchange without measuring trading returns or execution costs.
Order book depth shows how much liquidity rests at each price. It says nothing about how quickly that liquidity is being rewritten. That distinction sits at the center of "Book Churn," a metric introduced in Glassnode research published on November 18. Built from Binance perpetual futures data and backfilled to January 2020 for both Bitcoin and Ether, Book Churn flagged a more volatile-than-median following hour 63% of the time when it scored 2 or higher — well above the 50% baseline set by chance, yet only marginally ahead of a far simpler signal built from each window's high-to-low price range.
What Book Churn Actually Counts
Binance streams every change to its order book as it happens. Each message indicates, in effect, that a given price level now holds a new quantity of bids or asks. Trades generate messages as well, because a fill shrinks the amount resting at that price. Glassnode sums these messages in ten-minute windows; on BTCUSDT, a typical window carries roughly 607,000 updates.
A raw count needs context. Glassnode converts it into a score by measuring each window against the same clock hour over the previous 30 days, so a busy trading hour is judged against its own history while quiet overnight hours face theirs. A score of 2 marks an unusually active window; readings of 3 or above are rarer still.
The feed has blind spots. It reports price levels, not individual orders, meaning a single message can bundle several cancels, new orders, and fills. It does not separate a pulled quote from an executed one, and it identifies no traders. When the exchange connection drops and resets, a window can even register as quieter than it really was. A spike says the book got busy. It cannot say why.
Two Books, One Screenshot
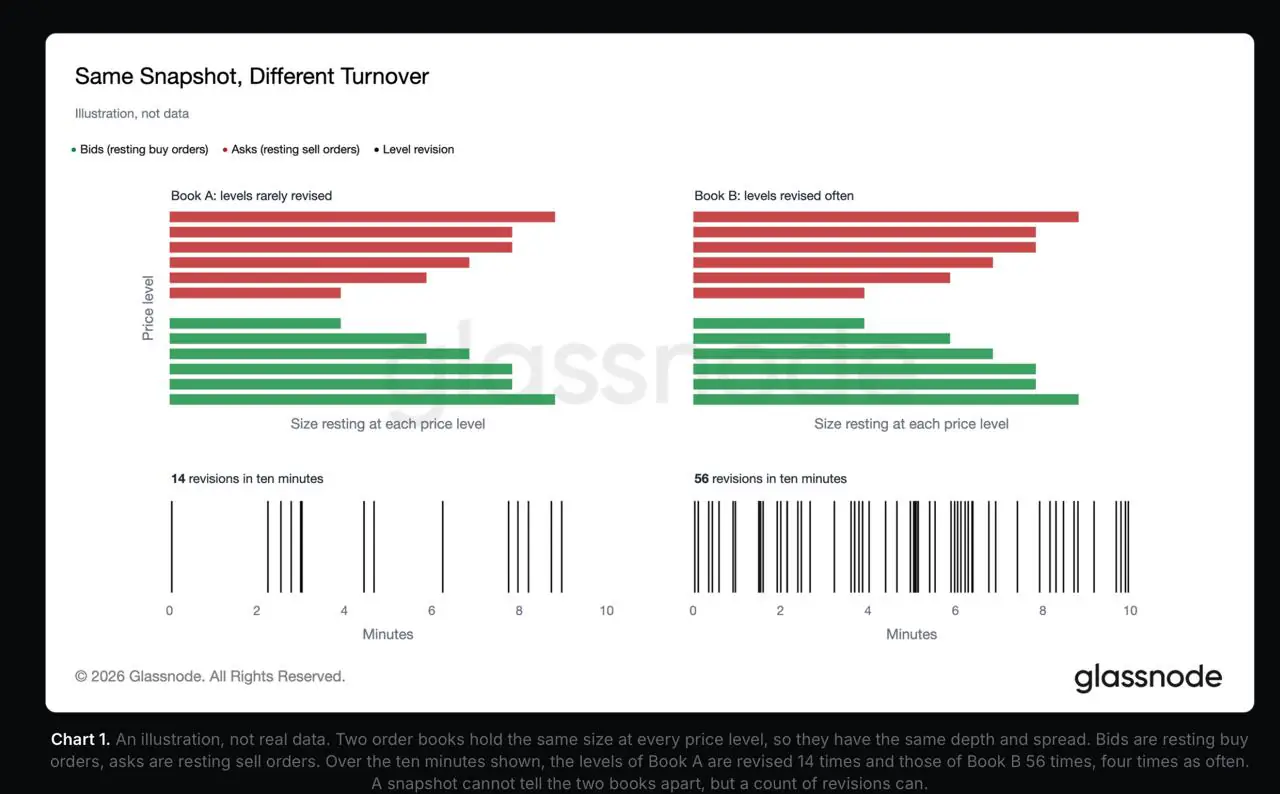
Picture two order books holding identical quantities at every price — same depth, same spread. A screenshot cannot tell them apart, but ten minutes of observation can: in Glassnode's illustration, one book changes 14 times while the other changes 56. Those counts are invented to demonstrate the idea, but the point behind them is real. Depth tells you how much is resting; churn tells you how often it moves. Neither metric answers the other's question.
April 27: A Calm Surface, a Tripling Feed
In this study, depth means the dollar value of bids and asks resting within 1% of the mid-price, and the spread is the gap between the best bid and the best ask. The mid-price is the midpoint between those two quotes. On the morning of April 27, both looked calm.
Three consecutive windows beginning at 05:10, 05:20, and 05:30 UTC carried between 1.8 million and 2.1 million updates each, up from 0.6 million to 0.9 million in the hour before. Churn scores hit 4.34, 3.83, and 3.41. Combined depth, which had ranged between $400 million and $464 million in the prior hour, slipped to between $377 million and $412 million, then jumped to $565 million in the next window. The spread sat at about one tick — the minimum price increment — throughout.
Price did not sit still. The high-to-low range reached 95 basis points — close to 1% — in the first burst window, then 28 and 39 basis points in the following two. Range measures how far price traveled inside a window, not which way it finished. A trader watching depth and spread saw a mild dip; underneath, the update feed had nearly tripled.
Most busy windows look nothing like this. Across BTCUSDT history, elevated churn usually came with thinner depth and wider spreads, showing correlations of -0.40 and +0.49 respectively. The combination that matters most — normal depth, quiet prices, and frantic quoting all at once — appeared in only about 7% of BTCUSDT readings scoring 3 or above. Those are the windows where churn picks up something nothing else on the screen shows.
Scope matters here. This is one perpetual futures contract — a derivative with no expiry date — on one exchange, not the whole Bitcoin market. Combined depth also counts both sides of the book, while a buyer can draw only on the asks — a fraction of that total.
Where Churn Meets Execution
A market buy takes the cheapest ask first, then the next one up, and keeps climbing until the order is complete. Coinbase's trading rules spell out that a single market order can fill at several prices. Consider a hypothetical book shown twice: once as a trader sees it, and once after a single quote moves.
In Book A, a 3 BTC market buy pays $100,000, $100,100, and $100,200 — an average of $100,100 before fees. Anyone expecting the whole order at the top price pays $300 more than planned. Thin depth at the best ask caused that. Churn played no part.
Book B is where churn enters. The seller at $100,000 pulls that coin and reposts it at $100,150 a moment before the order lands. The trader sees the same screen, sends the same order, and pays $450 above the top-of-book estimate. Repeat that kind of swap across thousands of price levels and the result is a churn spike. The score cannot say which level will move, or where it goes next.
A limit order caps the price but may leave a position partly filled, or not filled at all — and fees sit on top of every figure above.
63% Sounds Strong. The Baseline Is 50%.
Glassnode's main test asked a narrow question: when churn scored 2 or higher, was the next hour more volatile than the median hour? Half of all hours land above the median by definition, so a coin flip scores 50%.
Random spikes landed right on the coin flip, confirming the test was not rigged. Churn cleared that line, and higher scores cleared it by more.
The highlighted row is the awkward one. Glassnode built a matching signal from nothing but each window's high-to-low swing, and it edged churn by a fraction of a point — a gap too small to call either way. The two scores move together with a correlation of 0.84, and price range alone explains about 70% of the variation in the churn score. For the most part, churn re-measures price movement through the quote feed.
Not entirely, though. In roughly half the windows where churn fired, the range signal stayed silent. Similar accuracy, different moments.
The day-old row tells its own story. A reading from a full day earlier kept most of the edge, pointing to volatility that lingers for days, while the current reading added four to five points on top. Even so, about 37% of high readings still came before a perfectly ordinary hour.
Glassnode lists its own limits. The test ran in-sample: volatility buckets and control groups were set using each full calendar year, including months a live trader would not yet have seen. Results for 2020 and 2021 came in at 53% to 57%, not clearly above chance. By Glassnode's own description, Bitcoin and Ether on one exchange amount to close to a single test. The score says nothing about direction, and the study never measured trading returns or execution costs.
Before Sending a Large Order
Check the ask side at your own order size. A combined depth figure blends buyers and sellers, and the best price usually covers only the first slice of a big order.
During a churn spike, read a one-tick spread as a fact about the best price and nothing deeper. The next level up may be the one getting rewritten.
Then decide which risk to carry. A market order gets the trade done at an unknown price. A limit order holds the price and may never fill.
Glassnode has not tested whether churn improves real fills once depth, spread, and fees enter the math. It also does not publish how long each reading takes to arrive after its window closes — a detail that matters to anyone hoping to act on one. What the metric offers today is narrower but still worth having: when updates triple and the spread does not budge, the calm on screen is only the top layer.
Source: Coindoo

