ECB Says Offline Digital Euro Payments Will Stay Private as Banks Monitor Online Transactions
Key Takeaways
- •Offline digital euro payments will keep transaction records on users’ devices and will not be directly linked to identities by the Eurosystem.
- •Online digital euro payments will be accessible to financial intermediaries, which the ECB says is needed for anti-money-laundering compliance.
- •ECB survey data show cash use at euro-area point-of-sale terminals has fallen since 2019, while card and mobile payments have increased.
- •The ECB plans holding limits and a 24-hour merchant sweep requirement, and it has said that up to €700 billion could leave banks without such limits.
- •The European Parliament and the Council are preparing to vote on the legal framework, and issuance can begin only after the legislation is adopted.
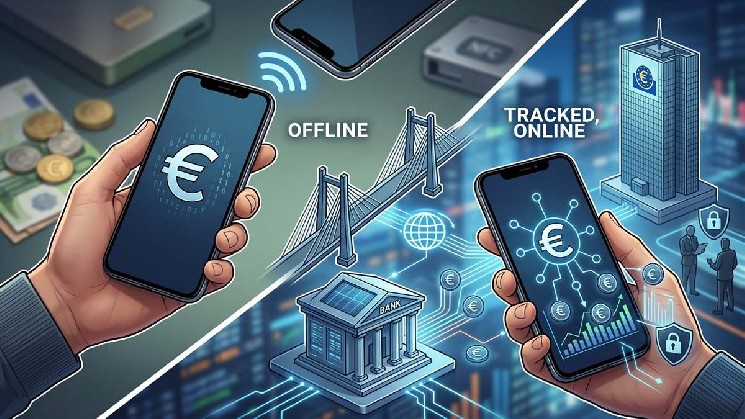
The European Central Bank (ECB) has confirmed that digital euro payments executed offline will offer cash-like privacy, while online transactions will remain under the direct monitoring of commercial banking institutions.
The statement was delivered by Piero Cipollone, a member of the ECB's Executive Board, whose remarks outline a two-tier privacy model: strong confidentiality is confined to the offline channel, while the connected channel — where the bulk of modern commercial activity is concentrated — remains visible to financial intermediaries.
The design lands as the ECB confronts a payments landscape its own survey data show is moving away from cash: the central bank's studies indicate that the share of euro-area point-of-sale transactions paid in cash has declined steadily since 2019, while card and mobile payments — often processed by non-European networks such as Visa and Mastercard — have grown. European officials have framed the digital euro partly as a matter of payment autonomy, offering the bloc a public alternative to private, foreign-dominated payment rails.
Offline privacy, online visibility
Under the offline modality, transaction records will remain restricted to users' devices, and the Eurosystem will not directly link identities to those payments. However, by conditioning privacy exclusively on offline settings, the central bank relegates confidentiality to a marginal use case within an increasingly digitized economy. That stands in contrast to physical cash, which by design carries no transaction trail in any setting.
In the connected channel, financial intermediaries will have full access to transactional data, under the rationale of anti-money laundering (AML) regulatory compliance. Although the ECB references zero-knowledge proofs in online environments to limit data exposure to the issuing central bank, the ongoing access granted to commercial banks ensures that everyday transactions stay within the perimeter of institutional monitoring — an architecture that subordinates individual privacy rights to centralized oversight.
CBDC versus cryptocurrencies
The framework reinforces the inherently different nature of central bank digital currencies (CBDCs) compared to cryptocurrencies such as Bitcoin. While Bitcoin was created to empower individuals through financial sovereignty and decentralization, the digital euro operates as a state-driven instrument for centralized control and financial oversight, perpetuating financial intermediation.
The ECB is not alone in this direction: dozens of central banks are developing or piloting retail CBDCs, from China's e-CNY pilots to live deployments such as the Bahamas' Sand Dollar and Nigeria's eNaira — all of them state-issued instruments running on centrally governed infrastructure rather than permissionless networks.
Technical design and user-borne risk
The technical design incorporates secure hardware elements in mobile phones to mitigate double-spending in offline operations, shifting the entire risk of physical device loss or damage onto the user. Because offline balances live only on the handset, a lost or damaged device puts those funds at risk.
Unlike the free crypto-asset market, where blockchain technology fosters permissionless interoperability, the digital euro introduces containment measures designed to protect the traditional banking system.
Holding limits and merchant sweep rules
Simulations conducted by the ECB itself acknowledge that, without holding limits, up to €700 billion in deposits could flee commercial institutions. Consequently, the regulatory framework will impose strict caps on individual holdings and mandate that merchants sweep their funds within 24 hours, directly constraining citizens' freedom to save and manage their own capital.
Legislative step ahead
Amid global warnings regarding the mass-surveillance risks inherent to central bank digital currencies, the European Parliament and the Council of the European Union are preparing to vote on the digital euro legal framework — a step that would formalize the expansion of state oversight across European digital payment systems. The legislative proposal was introduced by the European Commission in June 2023, and the ECB — which entered its formal preparation phase for the project in November 2023 — has stated that issuance can proceed only once that legislation is adopted.
Source: CryptoNews | Crypto Economy

