Diesel outpaces crude and gasoline as global refining disruptions widen
Key Takeaways
- •Brent settled at $72.48 a barrel on Feb. 27 and rose to $91.62 on Wednesday, while ULSD increased from $2.596 to $4.4523 a gallon over the same period.
- •Since the Iran war began, Brent has gained 26.4% and ULSD has gained 71.5%, with the RBOB gasoline proxy up 56.5%.
- •The spread between Brent and ULSD crossed $90 a barrel on the first two days of this week, a level the article says was likely a historic high.
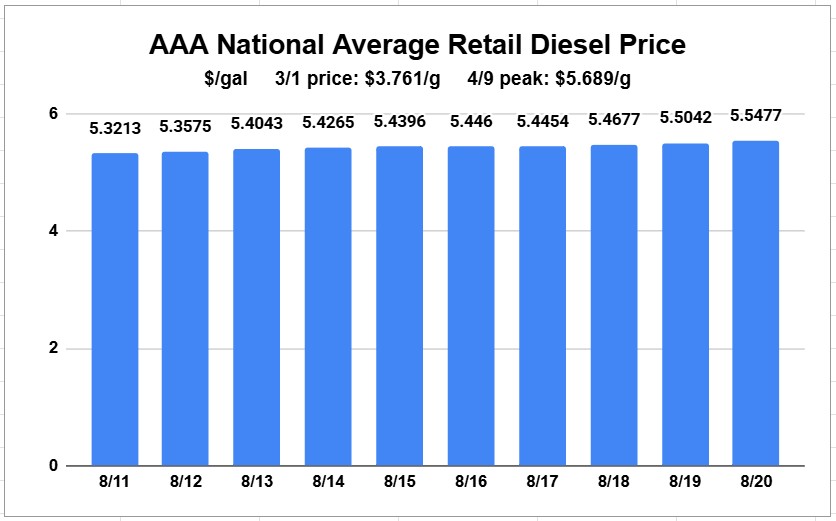
- •Average U.S. retail diesel prices reached $5.5477 a gallon on Thursday, within 15 cents of the post-war peak set on April 9.
- •The IEA said Russian refinery exports have nearly halved recently after intensified attacks, while U.S. refiners have pushed utilization to 97.2% to capture strong diesel margins.
Beyond simply noticing retail diesel prices rising again, consumers dealing with higher fuel costs should understand several key comparisons.
On February 27, the last trading day before military action began between Iran on one side and the U.S. and Israel on the other, international crude benchmark Brent settled at $72.48 a barrel on the CME commodity exchange. On the same day, ultra low sulfur diesel (ULSD) settled at $2.596 a gallon.
On Wednesday, Brent settled at $91.62 a barrel. ULSD settled at $4.4523 a gallon.
By the math, since the start of the war, Brent is up 26.4%, while ULSD is up 71.5%. Thursday’s settlement was $4.4803 a gallon. On CME, the contract for RBOB, an intermediate product that serves as a proxy for gasoline, had risen 56.5% since the Iran war began. That is well above Brent’s increase, but still below diesel’s.
It is the wide gap between crude and diesel that has drawn broad attention to the fuel, in part because fleets are frustrated to hear that crude is rising slowly or even falling while their own fuel costs continue climbing. Diesel is even taking the spotlight from gasoline, which, because it is consumed by far more people than diesel, usually draws more attention from the media, politicians and general consumers.
That shift was captured in a recent Axios article titled, “Diesel desperation is mounting.”
No one has been a more consistent voice on the rising diesel market and what it means for the broader energy picture than Jeffrey Currie, former head of commodities at Goldman Sachs, who is now involved in several businesses. He has made numerous television appearances, including one this week on CNBC, where he described the disconnect between crude and product prices as historic.
“Nobody consumes crude oil but refineries,” he said. “To everybody else on the planet Earth, what matters are the product prices.”
Currie said the spread between product prices and crude prices had historically been “relatively stable.” But on a day when Brent was trading at about $87 a barrel, he noted that diesel in European trading was around $170 a barrel.
“Crude is nearly half the price of the products,” Currie said. “So those relationships, those econometric models, everybody that’s been making that assumption that the spread between oil and products is a relatively stable constant relationship have missed out.”
A gigantic gap
There are multiple ways to measure the current disconnect. The crack spread measures the value difference between a barrel of crude and the products refined from it.
A simple way to highlight diesel’s strength is to compare the second-month price of ULSD on CME with the first-month Brent price, since Brent can be refined into ULSD.
On February 27, the final trading day before the Iran war began, that spread was about $36.55 a barrel. On the first two days of this week, it crossed $90 a barrel for the first time since the war began, and likely for the first time in history. Crude settled at $91 a barrel that day, underscoring Currie’s point that crude is about half the value of ULSD. The spread later fell slightly below the $90 mark on Wednesday.
At the pump, the result is that average U.S. retail diesel prices, as measured daily by AAA, were $5.5477 a gallon on Thursday. That was within 15 cents of the post-war high of $5.5689 a gallon set April 9 and more than 25 cents a gallon higher than August 10, when the latest run of higher retail prices began.
The question is why diesel has reacted to the full range of bullish market factors more sharply than crude and more sharply than gasoline since the Iran war began. The list is long, and it runs through both supply disruptions and refinery behavior.
Cutbacks in Russia
With so much attention focused on the Middle East and the Strait of Hormuz, the effect of Ukrainian attacks on Russia’s refining infrastructure — which is heavily engineered to produce a strong diesel yield — initially received less attention. That has changed.
The International Energy Agency, in its July monthly report, detailed some of the impact of the drone attacks. Since then, the situation has only worsened from the diesel market’s perspective.
“Trade data show that exports have nearly halved in recent weeks, following the intensification of attacks by Ukrainian forces on Russian refineries,” the IEA said.
In July, the IEA estimated that Russian refining runs were down 1.6 million barrels per day year over year because of the attacks.
“In conjunction with the attack on Russian storage sites and infrastructure, this loss of product output has reportedly caused widespread domestic fuel shortages and led to a temporary ban on diesel exports,” the IEA said.
More recently, energy consulting and information firm RBN Energy estimated that crude runs in Russia had dropped from more than 5 million barrels per day last year to around 3.8 million barrels per day in July, which it said was a 25-year low.
How U.S. refiners are reacting
U.S. refiners are rushing to take advantage of the spread. The refinery utilization rate published weekly by the Energy Information Administration has not been below 90% since the end of April and has been consistently above 95% since the first week of June. The latest weekly report put utilization at 97.2%.
“They’re always going to respond to market signals, and with strong diesel cracks, they’re going to produce the maximum,” John Auers, managing director of refined fuels at Novi Labs, said in an interview with FreightWaves.
Wall Street has rewarded independent refiners with a surge in share prices. Valero (NYSE: VLO), for example, hit another 52-week high Thursday at $352.33. A year ago, the stock was below $138.
Auers said refiners have already planned investments to produce more diesel over the long term, in part because electric vehicle adoption has softened gasoline demand. That shift is slowing in the U.S. but remains strong in other parts of the world. Still, those changes will take time.
“New refineries globally are generally more diesel or distillate oriented,” he said.
There have also been concerns that running refineries this hard for this long could set some plants up for a major breakdown. Even in good times, the U.S. industry tends to run above 90% at this time of year, but not at this level for this long.
Fewer refineries, tighter supply
The U.S. Energy Information Administration said earlier this year that the country lost about 250,000 barrels per day of refining capacity last year. Two major refineries closed in 2025, one in Houston and one in California.
Because the oil market is global, a shutdown anywhere in the world can affect the U.S. market, whether it is permanent or the result of war-related damage.
In its latest report, the IEA said global refinery inputs were about 5 million barrels per day below year-earlier levels at 80.9 million barrels per day. Global oil demand is more than 100 million barrels per day, though not all of that becomes refined products; for example, the 100 million figure also includes natural gas liquids such as propane. Even so, a 5 million barrel-per-day loss of refinery operations is significant.
Middle East refineries hit
Auers said “three or four” refineries in the Middle East have been damaged by Iranian attacks, cutting refining capacity in the region. A 380,000-barrel-per-day refinery in Bahrain was hit early in the war, and Auers said it is “completely out.”
He also pointed to a key unknown: the war’s impact on Iranian refining capacity, which is difficult to determine.
Crude quality matters
Middle East and Russian crudes, both affected by military conflict, are heavier and tend to yield more diesel than crudes from places such as West Africa or the Permian Basin in the United States.
Tight inventories
The latest weekly EIA report shows total U.S. non-jet distillate inventories — which include heating oil but are generally a little less than 90% diesel — are well below normal levels for this time of year.
Currie, in an interview on X with Mario Nawfal, said the divergence in inventories is a key reason for the blowout in crack spreads.
Products markets are dealing with what Currie called “rotating bottlenecks around the world right now.” Crude markets, by contrast, have been pressured lower by releases from strategic stockpiles such as the U.S. Strategic Petroleum Reserve (SPR). There are no strategic inventories for products.
Those reserve releases gave the market a “reprieve,” which was also helped by the surge in crude supply that came out of the Gulf when the ceasefire first went into effect in early April. Products received no similar injection of supply, Currie said.
“And it’s just a matter of time before we end up with the shortages starting to move from products into crude oil, and there’s no indication this thing is ending anytime in the very near future,” he said.

