From $250,000 to $3.4 Million: Bitcoin Trader Claims Huge Options Gains During Market Sell-Off
Key Takeaways
- •A trader known as Crash claimed on October 30 that he grew $250,000 to nearly $3.4 million by trading Bitcoin options during the recent crypto price downturn.
- •He also reported turning $130 into $25,000 within six hours on a single options contract, which he described as his best single-day percentage return.
- •The displayed balance of $3,387,187.14 implies a profit of about $3.14 million, or roughly 1,255%, while the smaller trade equates to approximately a 192x gain before fees.
- •The evidence consists only of a self-published screenshot showing an aggregate balance, with no order history, deposit records, or contract parameters available for independent verification.
- •The trader warned that timely profit-taking is critical in low-liquidity derivatives, where bid-ask spreads can make actual execution worse than on-screen balances suggest.
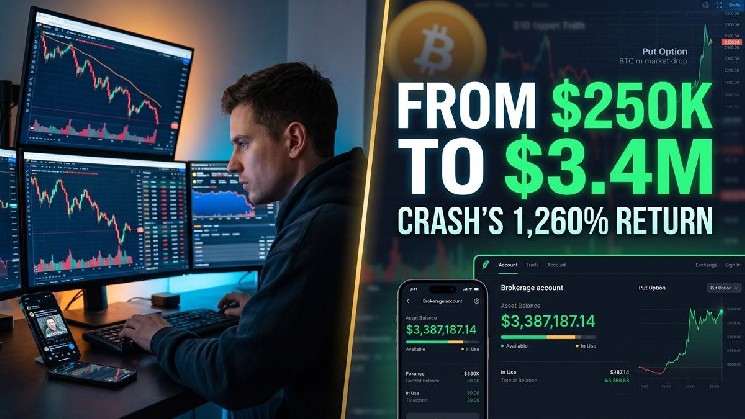
From $250,000 to $3.4 Million: Bitcoin Trader Claims Huge Options Gains During Market Sell-Off
A Bitcoin options trader known on social media as Crash claimed on Friday, October 30, that he grew his capital from $250,000 to nearly $3.4 million by trading options contracts during the recent downturn in cryptocurrency prices.
The claim was published through the trader's personal account on X, together with a screenshot of his account balance showing total assets valued at $3,387,187.14. According to the shared data, most of the funds appeared as available, while a smaller portion was categorized as in use. Alongside the weekly result, the trader also reported a single trade that converted $130 into $25,000 within a six-hour span.
Turning $250,000 into $3.4M this week on the market drop
And $130 into $25,000 in 6 hours on a single options contract (my record % return wise on a contract in 1 day)
Semi educational but mostly just me recording my own proof and good moments
Tip of the video is to always be… pic.twitter.com/uYzOjgz1oY
— Crash (@CrashiusClay69) October 30, 2026
The Numbers Behind the Claim
Arithmetically, an increase from an initial $250,000 to a flat $3.4 million represents a 13.6x multiple on the starting balance. The absolute difference amounts to $3.15 million, corresponding to a nominal return of 1,260%. Measured against the exact figure displayed in the screenshot ($3,387,187.14), the total profit stands at $3,137,187.14, marking a return of approximately 1,255%.
However, as technical market analysis points out, the visual data reflects only an aggregate balance. It does not detail individual order history, whether external deposits were made to the account, or what percentage corresponds to fully realized positions. Because the figures exist only as a self-published screenshot, outsiders have no way to audit them — a recurring feature of trading results shared on social media, where performance claims rest on whatever evidence the poster chooses to disclose.
Alongside the weekly total, the trader highlighted a specific put option trade on Bitcoin with a reported return of 150x. In a follow-up post, he claimed to have turned $130 into $25,000 in six hours through a single option, calling it his single-day percentage record.
This $130 trade would represent a final value 192.3 times the initial stake, yielding a gain of $24,870, or roughly 19,131% before platform trading fees. Report data notes that the trader's post did not clarify whether this $130 contract was the same 150x put trade, meaning both claims remain separate statements without verifiable contract parameters.
Technical Mechanics and Risks of Put Options
A put option contract gives the holder the right, under the terms established by the instrument, to sell the underlying asset at a predetermined strike price. In cash-settled contracts, the seller pays the corresponding cash difference rather than requiring physical delivery of the tokens.
When Bitcoin's price declines, the market value of a put option typically appreciates, as the agreed-upon selling right becomes more advantageous. Derivatives financial literature indicates that an option's premium depends not only on the direction of the spot price, but also on the time remaining until expiration and the implied volatility priced in by market makers. During broad market declines, that implied-volatility component generally rises, which raises the premiums buyers pay for downside contracts.
A lower premium on out-of-the-money options can produce substantial percentage swings if the underlying asset's price drops rapidly toward the strike level. For the outright buyer of a put option, the maximum financial risk is strictly capped at the premium paid should the contract expire out of the money with zero intrinsic value. That asymmetry — a small, fixed premium at risk against a payout that scales with the size of the decline — is the mechanism behind the kind of outsized multiples claimed in this week's posts.
Despite the published numbers, the trader emphasized the technical importance of taking profits in a timely manner once significant favorable moves occur. His warning focused specifically on low-liquidity derivatives, where the bid-ask spread can impair actual execution compared to the theoretical balances displayed on screen.
Looking ahead, the expiration of the major monthly Bitcoin options blocks on Deribit and CME is scheduled for the final trading session of November 2026, a date when institutional players will adjust their hedges ahead of upcoming central bank monetary policy decisions. Deribit, a crypto-focused derivatives exchange, and CME, a regulated traditional marketplace, host listed Bitcoin options markets whose monthly expiries are among the most closely watched dates on the derivatives calendar. As for the claimed gains themselves, they remain self-reported, with any order-level confirmation resting on records the trader has not made public.

