New Paper Revisits the Term Spread's Predictive Power After the Missing 2024 Recession
Key Takeaways
- •Pre-2020 term-spread models explained more variation in recession outcomes than models estimated over the full sample.
- •Adding the debt service ratio increased the model’s explained variance from 0.26 to 0.57 and eliminated false positives in the reported specification.
- •The debt-service model identified the 1990-91 and 2008-09 recessions but did not predict the 2020 pandemic or a 2024 recession.
- •Including expected unemployment reduced the estimated 2024 recession probability below 40%, although the approach missed the 2008-09 recession.
- •The study also examines Canada and Germany and finds that the yield curve became less accurate after the 2020 recession.
The failure of a widely anticipated US recession to materialize in 2024 has forced economists to reappraise the term spread, long regarded as the most reliable recession predictor for the United States. The term spread — the gap between yields on longer- and shorter-dated Treasury securities — carries that reputation because inversions, in which short-term yields rise above long-term yields, have historically preceded US downturns. A new paper, “Missing Recessions: Revisiting the Term Spread’s Predictive Power,” by Menzie Chinn and Laurent Ferrara, re-evaluates the indicator’s predictive power and explains the false positive signal.
The failure of a recession to materialize in 2024 has forced a reappraisal of the term spread as the most reliable recession predictor for the US. In this paper, we re-evaluate the predictive power of the term spread, and explain the false positive signal in terms of sample specificity, simultaneity, and omitted variables, focusing on the United States, but including other advanced economies for which the term spread has proven to be a useful predictor in the past. We confirm that prior to the 2020 recession, the yield curve was an accurate predictor of recessions in the US, Canada, and Germany, but proved less accurate thereafter. For the US, accounting for term premia does not improve prediction appreciably, while taking into account expectations of future unemployment does. More definitively, in line with Borio, et al. (2020), we find inclusion of the debt service ratio reconciles the failure of a recession to appear in 2024 after the strong yield curve inversion observed at the end of 2022, for both the US and Germany.
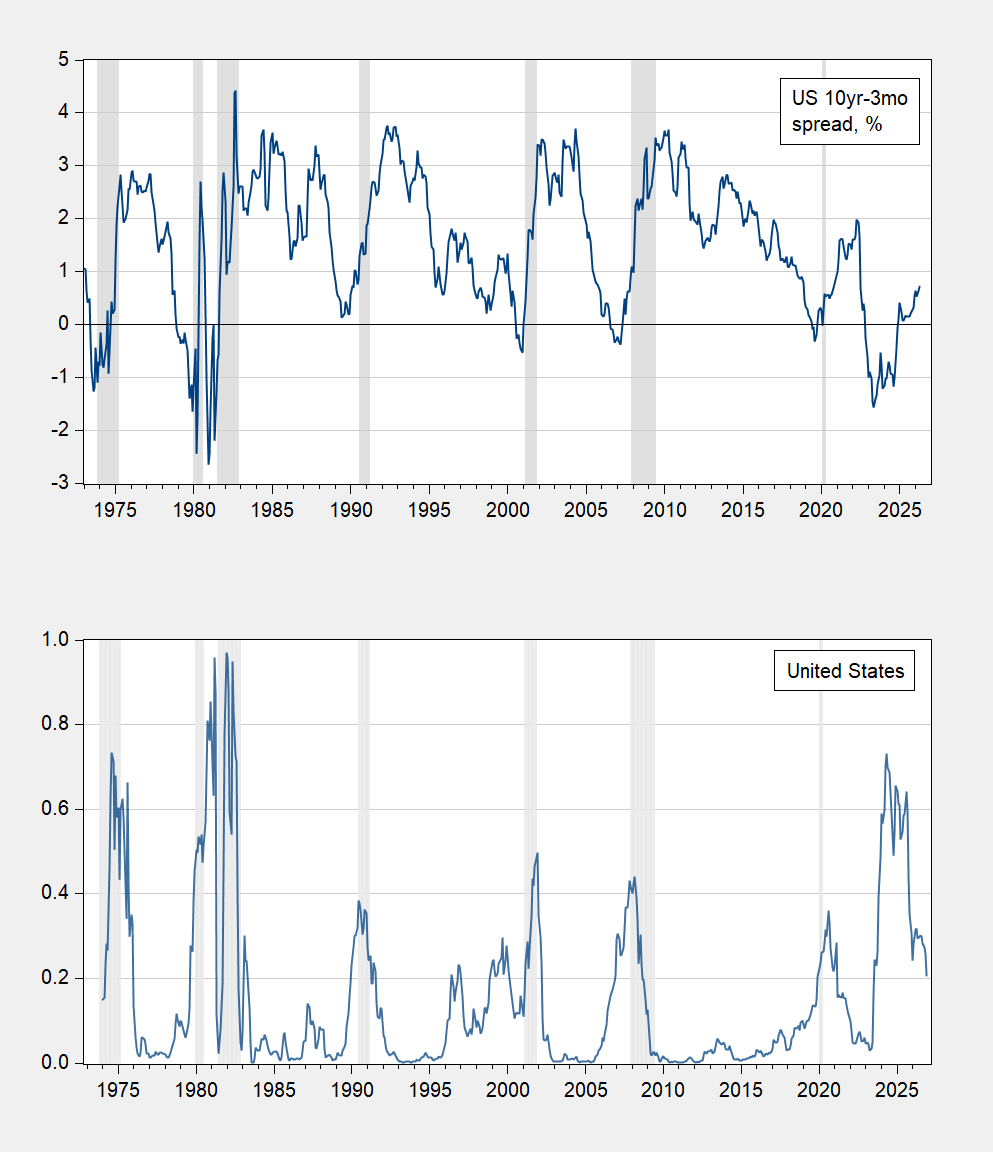
Focusing on the United States, most term spread measures — including the 10yr-3mo and 10yr-2yr spreads — indicated a high likelihood of recession in 2023-24, given the large and persistent inversion recorded in 2022. Relying on pre-2020 data, estimated recession probabilities looked strikingly elevated. Figure 1 of the paper shows the US 10yr-3mo spread, in percent, in the top panel, and the corresponding probability of recession in the bottom panel, derived from a regression estimated up to 2019M12, with NBER-defined peak-to-trough recession dates shaded gray. The NBER — the National Bureau of Economic Research — is the organization that formally dates US recessions, which is why its peak-to-trough shading serves as the standard reference in charts of this kind.
The authors catalog several possible explanations for the term spread’s 2024 mis-fire. The data-generating process may have changed since 2020. The behavior of the term premium — the extra yield investors require to hold longer-maturity debt rather than rolling short-term bills — which is part of the term spread, may have shifted. Estimates may also have been biased by the omission of Taylor Rule variables, such as expected unemployment outcomes, or of financial variables capturing the financial cycle. It is also possible that “by chance” the recession simply did not occur — after all, one is never 100% confident.
To weigh these possibilities, the authors estimate term spread specifications over a full sample, or augment them with key variables.
The results, reported in Table 2 of Chinn and Ferrara (2026), show that the proportion of variance explained using the term spread is higher in the pre-2020 sample than in the full sample, at 0.33 versus 0.26. Adding a separately estimated term premium — the ACM estimate from the NY Fed — does not appreciably change the full-sample result. Adding the expected change in the unemployment rate, a variable motivated by the Taylor rule’s implication that future Fed funds rates will be lower if markets anticipate a slowdown or recession, does yield a marginally significant coefficient, although the pseudo R² is essentially unchanged.
Only the inclusion of a proxy for the financial cycle — the debt service ratio (DSR), which measures the share of income that borrowers devote to servicing debt — raises the proportion of variance explained appreciably, to 0.57. The equation incorporating the DSR also delivers the best fit in the sense of producing no false positives while catching the recessions of 1990-91 and 2008-09; it appears as the teal line marked &DSR in Figure 5 of the paper, with NBER-defined peak-to-trough recession dates shaded gray. For forecasters, the practical upshot is that the shape of the yield curve on its own does not capture how heavily household and corporate budgets are burdened by debt payments — a dimension the authors’ results suggest belongs alongside the spread in recession-forecasting models.
The finding that the DSR improves recession prediction holds even when the estimation period is restricted to pre-2020 data. In that configuration, the model predicts the recessions of 1990-91, 2001, and 2008-09, but not the 2020 pandemic recession — nor a 2024 recession.
The authors do not dismiss the Taylor rule as useless. As column 4 in Table 2 shows, including the expected change in the unemployment rate — conjoined with using the Fed funds rate instead of the 3-month rate — reduces the estimated probability of recession for 2024 below the 40% threshold (the blue line marked &UE), while still catching previous recessions, with the exception of 2008-09. In that sense, not explicitly taking the Taylor rule into account could form part of the explanation for the erroneous 2024 recession call.
The paper, which also examines the experiences of Canada and Germany, is a substantially revised version of earlier work described here. Read the entire paper here.

