Week 37 Commodities Market Watch: Oil Cleared $100, Gold Lost to Rate Pressure, and Grains Softened Into Friday
Key Takeaways
- •WTI crude settled Friday at $100.05 and Brent near $104.61, both posting weekly gains of about 8% as Middle East facility tanker, and shipping risks outweighed a holiday-shortened trading week.
- •Gold fell more than 2% for the week, with December futures closing at $4,391.30, as hot CPI and PPI prints pushed September FOMC hike odds toward roughly 90% and lifted the 10-year yield near 4.975%.
- •US commercial crude stocks declined 391,000 barrels for the week ended September 4, less than the approximately 1.4 million barrel draw analysts expected, while refinery utilization held near 97.8% of capacity.
- •Copper retreated from Week 36 levels near $6.55–$6.60 toward roughly $6.28 per pound, as rising rate expectations and uneven Chinese demand data outweighed the still-open structural supply narrative.
- •Corn, soybeans, and wheat all closed lower on Friday, led by soybeans down 35 3/4 cents to $12.96 1/2, showing agriculture continued trading on weather and export fundamentals rather than oil's momentum.
Quick Answer
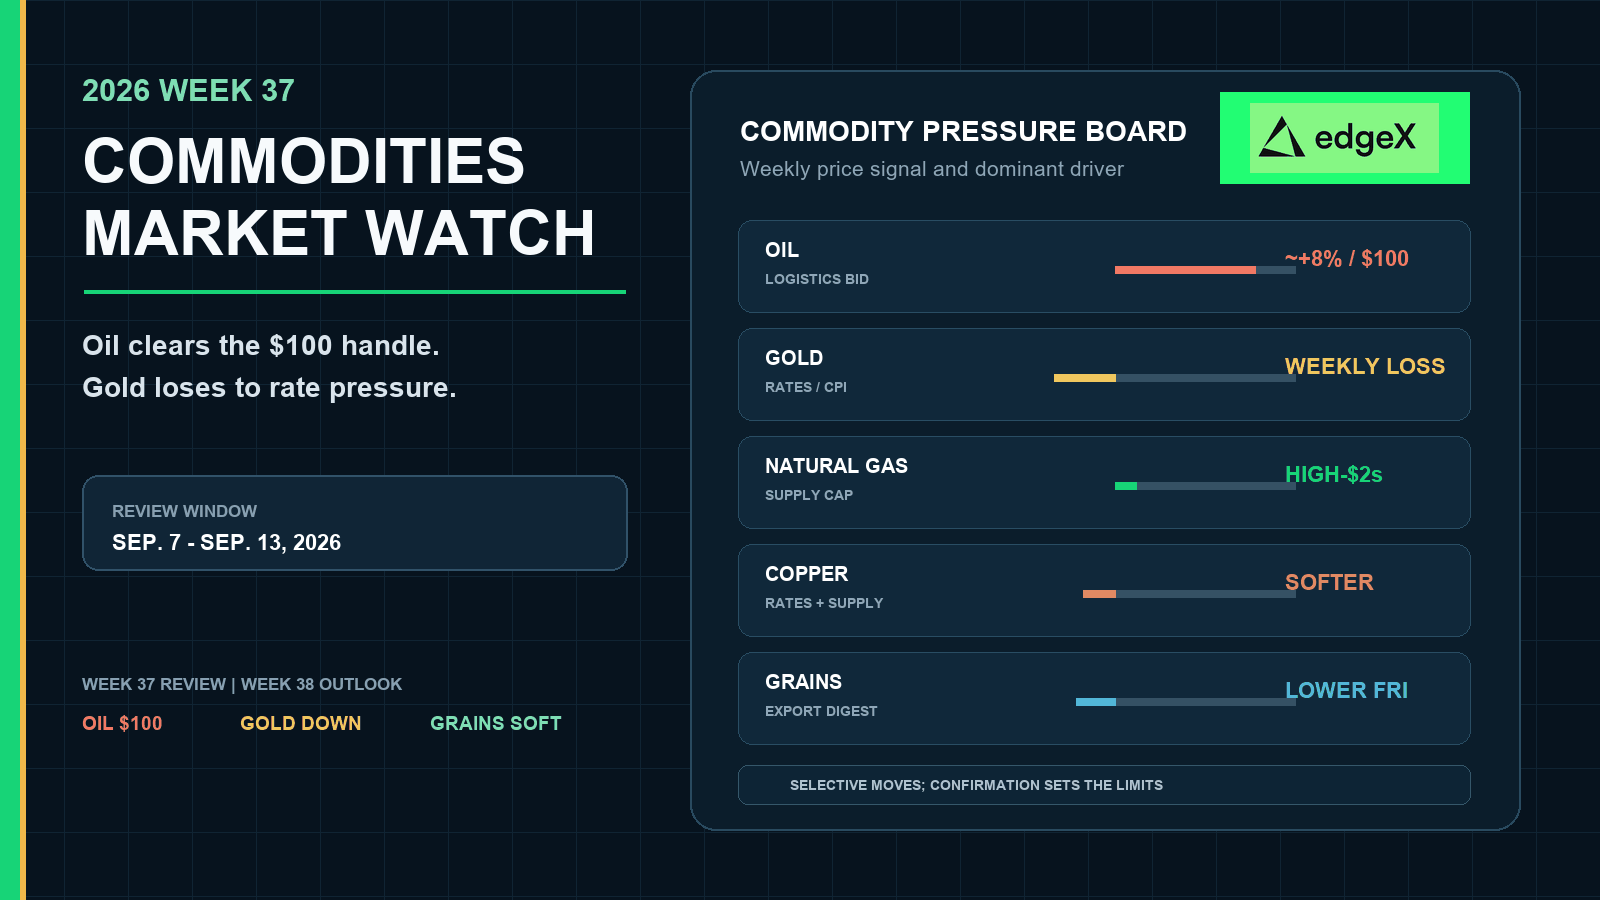
Week 37 stretched the commodity split rather than closing it. Oil cleared the psychological $100 mark on continued Middle East logistics risk and product stress, then pulled back into Friday without surrendering the weekly gain. Gold moved the other way: firm CPI and PPI data, higher bond yields, and rising rate-hike odds overpowered residual hedge demand even while crude stayed elevated. Natural gas remained supply-capped in the high-$2s. Copper drifted softer from its Week 36 highs while structural supply risk stayed in the background. Grains finished weaker into Friday, especially soybeans, showing agriculture still trades its own weather and export calendars. Week 38 therefore opens with energy still the loudest inflation channel, metals more sensitive to the September 15–16 FOMC decision, and grains needing fresh fundamental confirmation.
Week 37 Made Oil the Inflation Anchor Again
After Week 36 rebuilt a geopolitical oil premium and left gold damaged by payrolls, Week 37 tested whether energy risk would keep climbing into policy week or mean-revert under inventory pressure. Oil climbed through midweek, cleared $100 on WTI, and still finished sharply higher despite a Friday pullback. Gold’s weekly loss showed the opposite constraint: metals that can benefit from geopolitical stress reverse quickly when inflation data lifts real-rate expectations. Copper and grains again refused to copy oil’s weekly path.
Oil converted geopolitics into a three-digit tape
Friday futures closes put October crude at $100.05, down $2.43 on the day, and Brent near $104.61, down about $3.02, according to Brownfield Ag News and Investrade’s September 11 market review. Both benchmarks still posted weekly gains of about 8% after midweek multi-month highs, with Brent briefly approaching the $107–$108 area on Houthi, Saudi facility, and tanker headlines. That sequence extended Week 36’s rebound from the mid-$90s rather than inventing a new demand boom. The holiday-shortened week left fewer sessions for mean reversion and more room for logistics headlines to dominate.
Policy and physical markets still diverged inside the complex
Gold’s weekly decline was driven by CPI, PPI, yields, and FOMC pricing rather than metal-specific supply. Natural gas held a high-$2s neighborhood on weather and LNG without matching crude’s breakout. Copper softened from elevated Week 36 levels while year-ago comparisons remained strong. Grains finished lower into Friday. Energy again sat at the center of the inflation debate, while metals and agriculture still needed their own confirmation paths into Week 38.
Week 37 Commodities Dashboard
| Market | Completed Week 37 evidence | What the result means |
|---|---|---|
| Brent crude | About +8% weekly; Friday settle near $104.61 after midweek $107–$108 area | Logistics premium extended into three-digit territory, then pulled back on Friday |
| WTI crude | About +8% weekly; Friday close $100.05 | U.S. crude joined the global risk bid through the $100 handle |
| U.S. petroleum stocks | Crude −391k bbl week ended Sep 4; runs near 97.8% capacity | Physical balance stayed firm, but the draw was smaller than expected |
| Gold | Weekly-loss direction; Dec futures $4,391.30 Friday | Rate-hike odds and yields reclaimed control of the bullion tape |
| U.S. natural gas | High-$2s/mmBtu neighborhood into the Week 37/38 turn | Weather and LNG support remained capped by domestic supply |
| Copper | Softer from ~$6.55–$6.60 toward high-$6.20s | Elevated year-ago levels met near-term rate and demand pressure |
| Corn, soybeans, wheat | Lower Friday closes vs Week 36; soybeans −35 3/4¢ day | Agriculture cooled further without becoming an oil trade |
Oil and Products Pushed the Inflation Channel Higher
Oil’s weekly gain was large enough to change consumer and policy math, and inventories still blocked a pure panic reading. WSJ coverage dated September 10 said U.S. commercial crude stocks for the week ended September 4 fell 391,000 barrels, less than the roughly 1.4 million barrel draw expected by analysts. EIA summary notes put refinery runs near 17.6 million barrels a day at about 97.8% capacity utilization. Product-market coverage into the Week 37/38 turn also kept diesel near record retail stress and national gasoline averages elevated as Middle East logistics risk stayed open.
The weekly oil advance was a risk-and-balance story, not a demand boom
Week 36 showed unresolved geopolitics can re-bid oil quickly after a partial premium unwind. Week 37 showed the same file can stretch into three-digit prices when facility, tanker, and shipping headlines stack on still-firm refining runs. Coverage emphasized logistics risk, product tightness, and inflation transmission rather than a synchronized global demand boom. Friday’s $2–$3 pullback showed traders were willing to reduce exposure into the weekend without proving the logistics premium had closed.
If Hormuz and Red Sea traffic stay impaired, Saudi alternative routes remain constrained, or product stocks fail to rebuild in the next EIA prints, oil can hold or retest the midweek highs. If diplomacy improves and product inventories rebuild, the weekly gain can reverse quickly even from a $100 handle.
Products remained the closer link to consumer inflation
Diesel and gasoline sit closer to freight, food distribution, and household fuel costs than crude in storage. Record-area diesel stress and rising pump prices keep energy inside the CPI path that already lifted September hike odds. The same energy shock that supports crude can tighten financial conditions through higher expected policy rates, which helps explain why gold did not automatically rally with oil. Week 37 left oil as the loudest commodity inflation input heading into the Fed decision.
Gold Lost the Week to Yields and Hike Odds
Gold exited Week 37 under a rate-and-inflation shock rather than a safe-haven rally. Brownfield listed December gold at $4,391.30, down $16.00 on Friday. Investrade put spot near $4,408.90 into the quiet Friday finish and still counted gold and silver among the week’s losers. Midmorning Barron’s coverage on September 11 said gold was headed for a weekly loss of more than 2%, weighed down by surging oil, higher bond yields, and rising rate-hike expectations after the inflation sequence.
CPI and PPI reclaimed control of the gold tape
August headline CPI rose 0.4% month over month and 3.4% year over year, while core CPI rose 0.3% and 2.4%. Producer prices showed a hotter annual print near 5.4%. Money-market pricing moved toward roughly 90% odds of a September FOMC hike, the 10-year yield finished Friday near 4.975%, and non-yielding metal lost relative appeal. Residual geopolitical hedging is not automatic gold support while the rate channel is hostile. Oil can clear $100 on logistics risk in the same week gold falls on inflation data, so bullion is trading the policy path more than the crude path.
Natural Gas Stayed Supply-Capped While Oil Broke Out
U.S. natural gas again refused to behave like a pure satellite of crude. Trading Economics notes into the Week 37/38 turn left Henry Hub in the high-$2s/mmBtu area, around $2.88 in early Week 38 references, without a certified full-week percentage locked in the free sources used for this review. That neighborhood is firm enough to show weather and LNG demand still matter, and soft enough to show production and storage still protect the ceiling.
Weather and LNG helped; production still protected the range
Hotter forecasts and export feedgas can stabilize nearby contracts, but near-record Lower-48 output and comfortable inventories still require weaker production, bullish storage prints, or a deeper international shock for a sustained breakout. Persian Gulf logistics stress can support global energy risk without forcing Henry Hub through oil’s $100 path. Week 37 left gas as a regional physical market with firmer support and no scarcity stampede.
Copper Softened From Elevated Levels Without Losing the Supply Story
Copper left Week 37 softer than the Week 36 close while remaining historically expensive on a longer lookback. Week 36 had held near $6.55–$6.60 a pound. Trading Economics copper notes into mid-September placed futures near $6.28/lb after a multi-day soft patch, with the past-month move lower even as the year-ago comparison stayed strongly positive. Forbes supply commentary dated September 11 kept the longer-run scarcity and mine-disruption narrative in view even as near-term tariff and positioning trades faded.
Rate pressure met still-open physical risk
Nearby softness does not cancel structural supply constraints, shipping bottlenecks, or the multi-year scarcity thesis. It does show industrial metals can lose ground when hike odds rise and Chinese activity data remain uneven. China’s August CPI at 0.8% year over year and PPI at 3.8% year over year were energy-heavy rather than proof of a clean household-demand recovery, so copper still needs physical premiums and factory follow-through. The supply story remains open; the near-term rate and demand channel pressed first.
Grains Softened Further Without Becoming an Oil Trade
Agriculture again refused to copy the energy complex. Brownfield Ag News closing futures for September 11 put December corn at $5.30 1/4, down 3 1/2 cents on the day; November soybeans at $12.96 1/2, down 35 3/4 cents; and December Chicago wheat at $7.25 1/4, down 16 cents. Versus Week 36 Friday closes near $5.36 3/4 corn, $13.09 3/4 soybeans, and $7.34 wheat, all three finished lower. Market recaps dated September 11 also described corn, soybeans, and winter wheat shifting lower into the weekend.
Crop, export, and demand calendars still dominate
Late-summer weather can still change corn and soybean yield assumptions, while wheat remains sensitive to global supply headlines and export competition. Higher energy costs can lift the longer-run floor through diesel, fertilizer, and freight, but nearby direction still depends on production and export balances. Week 37’s Friday soybean slide showed traders were unwilling to hold oilseed risk into the weekend even while crude sat above $100. That is selective agricultural digestion, not a food-price collapse, and not an oil-led grain trade for Week 38.
Cross-Market Impact Map
| Commodity signal | Economic transmission | What would confirm it |
|---|---|---|
| Oil’s ~8% weekly gain through $100 | Stronger energy inflation and freight cost channel into FOMC week | Hormuz/Red Sea logistics path and the next product inventory |
| Smaller-than-expected crude draw with high runs | Supportive refining balance without panic scarcity | Continued product tightness rather than a rebuild in the next EIA report |
| Gold’s weekly loss under hike odds | Higher real-yield pressure and less automatic safe-haven support | Softer FOMC guidance, weaker dollar, or renewed hedge demand |
| Gas in the high-$2s | Demand support capped by production and storage | Bullish storage or weaker Lower-48 output |
| Copper softer from elevated levels | Rate-sensitive industrial metal pressure with open supply risk | Chinese premiums, factory demand, and inventory confirmation |
| Lower Friday grains | Weather/export premium digestion | Crop-condition deterioration or stronger export sales |
What Week 37 Changed
Week 37 replaced Week 36’s rebuilt oil premium with a harder inflation anchor. Energy risk moved through the $100 handle on logistics and product stress, then pulled back into Friday without erasing the weekly gain. Gold again showed firm inflation data and hike odds can overpower residual hedge demand in the same week oil rises. Natural gas stayed supply-capped. Copper drifted softer from elevated levels while the structural supply story remained open. Grains cooled further into Friday, led by soybeans. Week 38 still requires market-specific confirmation rather than one complex trade.
Week 38 Outlook: FOMC Week Tests Selective Confirmation
Week 38 covers September 14–20. The base case is selective confirmation under an FOMC lens rather than a uniform commodity rally. Oil starts above $100 with logistics and product support still intact, but Friday’s pullback showed the market can fade overextended risk into a policy event. Gold starts from a second consecutive rate-damaged finish and needs softer real yields or less hawkish Fed communication. Copper enters softer-elevated and must prove Chinese demand. Grains enter after Friday softness and need crop or export follow-through.
Oil and gas will be decided by logistics, products, and storage
Energy’s first tests remain physical. Watch Hormuz, Red Sea, and Saudi East-West pipeline headlines for whether the geopolitical premium holds above $100, and use the next EIA Weekly Petroleum Status Report to test whether gasoline and distillate tightness persists after the smaller-than-expected September 4 crude draw. If products keep drawing while logistics stay impaired, oil can retest midweek highs; if products rebuild and diplomacy improves, the weekly advance can reverse quickly even from a three-digit handle. Diesel and gasoline retail paths remain the consumer-inflation transmission that links crude to the Fed.
For U.S. gas, the next storage print, production trend, and LNG feedgas path remain decisive. Weather and export demand can support the high-$2s area, but record-area output and comfortable inventories still cap conviction unless storage turns clearly bullish or production softens.
Gold needs the rate channel to stop working against it
Gold’s Week 38 path depends less on oil’s level and more on the September 15–16 FOMC decision, yields, and the dollar. A hike that is already priced can still hurt bullion if the statement or press conference pushes real yields higher; a less hawkish path, weaker dollar, or renewed safe-haven demand would help repair the weekly damage. Residual geopolitical risk is not automatic gold support while the rate channel is hostile. BOE and BOJ meetings can add cross-currency noise, but the Fed remains the primary real-yield driver for bullion.
Copper and grains must convert open risks into fresh evidence
Copper already carries an elevated year-ago comparison and an open supply-risk narrative. Week 38 confirmation requires Chinese physical premiums, broader industrial data, and no quick restocking that would mark tightness as positioning alone. Without that, FOMC-driven rate pressure can dominate even if mine and logistics constraints remain real.
Grains need weather and export follow-through after Friday’s softer closes. Further crop-condition deterioration or stronger export sales would rebuild premium; comfortable production assumptions and weaker overseas demand would not. Higher energy costs can support the longer-run floor through diesel and freight, but they are not enough alone after the September 11 soybean slide.
A single shipping headline can reprice oil faster than weekly inventories, while a single FOMC paragraph can reprice gold faster than commodity-specific flows. Favor oil only while logistics and product stocks stay tight, gold only if yields cooperate after the Fed, copper if Chinese demand joins the supply signal, and grains if weather or exports tighten the balance sheet.
Trade Commodities Perpetuals On-Chain with edgeX
Commodity markets move fast. Your trading infrastructure should too.
edgeX is a decentralized exchange built on EDGE chain, settling on Ethereum via Arbitrum, that lets traders access tokenized RWA commodities perpetuals with institutional-grade execution and true self-custody. No KYC. No centralized custodian. Just full control of your assets, your private keys, and your positions.
Why traders choose edgeX for commodities:
- Ultra-deep liquidity: $10 million of depth within a one-basis-point spread, with sub-0.1-basis-point slippage on trades over $100,000, even during peak volatility.
- High-performance engine: Up to 200,000 orders per second with sub-10 millisecond matching latency.
- True self-custody: Withdrawals require only your wallet authorization; no platform approval needed.
- No KYC required: Start trading commodities, tokenized stocks, and crypto perpetuals without identity verification.
- 100% trading fee rewards: edgeX’s Trade to Own program returns 100% of trading fees back to users in $EDGE tokens.
- USDC-backed settlement: USDC is designed by Circle to be redeemable 1:1 for U.S. dollars, giving traders a familiar settlement base.
Whether you're trading gold, oil, or other RWA commodities, edgeX gives you the liquidity depth of a centralized exchange with the security of on-chain settlement.
The platform is available on desktop and as a native mobile app on iOS and Android, so you can manage positions and react to commodity market moves from anywhere.
Ready to trade commodities perpetuals without the constraints of a centralized exchange? Start trading on edgeX with no KYC and no compromises.
Frequently Asked Questions
What dates did 2026 Week 37 cover?
This review covers September 7 through September 13, 2026. The principal futures-market close was Friday, September 11, after a U.S. holiday-shortened start to the week.
Why did oil clear $100 in Week 37?
Oil extended Week 36’s geopolitical and logistics bid as Middle East facility, tanker, and shipping risk stayed open. Friday closes put WTI at $100.05 and Brent near $104.61, with weekly gains of about 8% after midweek multi-month highs. The move was a risk-and-balance extension rather than proof of a clean global demand boom.
What did inventories say about the oil balance?
For the week ended September 4, U.S. commercial crude stocks fell 391,000 barrels, less than the roughly 1.4 million barrel draw expected by analysts. Refinery runs stayed high near 97.8% of capacity, keeping the physical market firm even without a panic-sized draw.
Why did gold lose the week while oil rose?
Gold finished under rate pressure after firm CPI and PPI data lifted September FOMC hike odds toward about 90% and pushed yields higher. December gold closed Friday at $4,391.30, and weekly coverage put bullion on course for a loss of more than 2%. Geopolitical energy risk did not automatically support non-yielding metal while the rate channel was hostile.
What is the Week 38 commodities outlook?
The base case is selective confirmation under an FOMC lens. Oil needs logistics and product-inventory follow-through above $100, gold needs softer yield pressure after the September 15–16 Fed decision, copper needs Chinese demand to validate still-elevated supply-risk prices, and grains need weather or export follow-through. A uniform commodity rally is not the base case.

