Tokenized Real-World Assets in 2026: Market Size, Growth Rates and Leading Asset Classes
Key Takeaways
- •Estimates of the 2026 tokenized RWA market range from about $19 billion to more than $60 billion, largely because trackers differ on whether to include stablecoins, permissioned chains, and assets locked in smart contracts.
- •Tokenized US Treasuries form the largest category at roughly $15.4 billion, about 40% of the market, led by BlackRock's BUIDL, Circle's USYC, and Franklin Templeton's BENJI.
- •Private credit is the second-largest category and represents about 77% of value lent against tokenized assets, whereas tokenized real estate accounts for less than 1% of the tracked market.
- •Tokenized stocks and ETFs are the fastest-growing segment by users, with active stock holders surpassing one million and tokenized ETF market capitalization tripling from $219 million to $654 million during 2026.
- •Long-term projections diverge sharply, from McKinsey's roughly $2 trillion base case for 2030 to a $16.1 trillion estimate from BCG and ADDX.
Tokenized real-world assets — RWAs, in common market shorthand — are blockchain tokens that represent ownership of something held off-chain: a government bond, a loan, a fund share, a share of stock or a bar of gold. Advocates point to faster settlement, lower minimum purchase sizes and the ability to post such tokens directly as collateral.
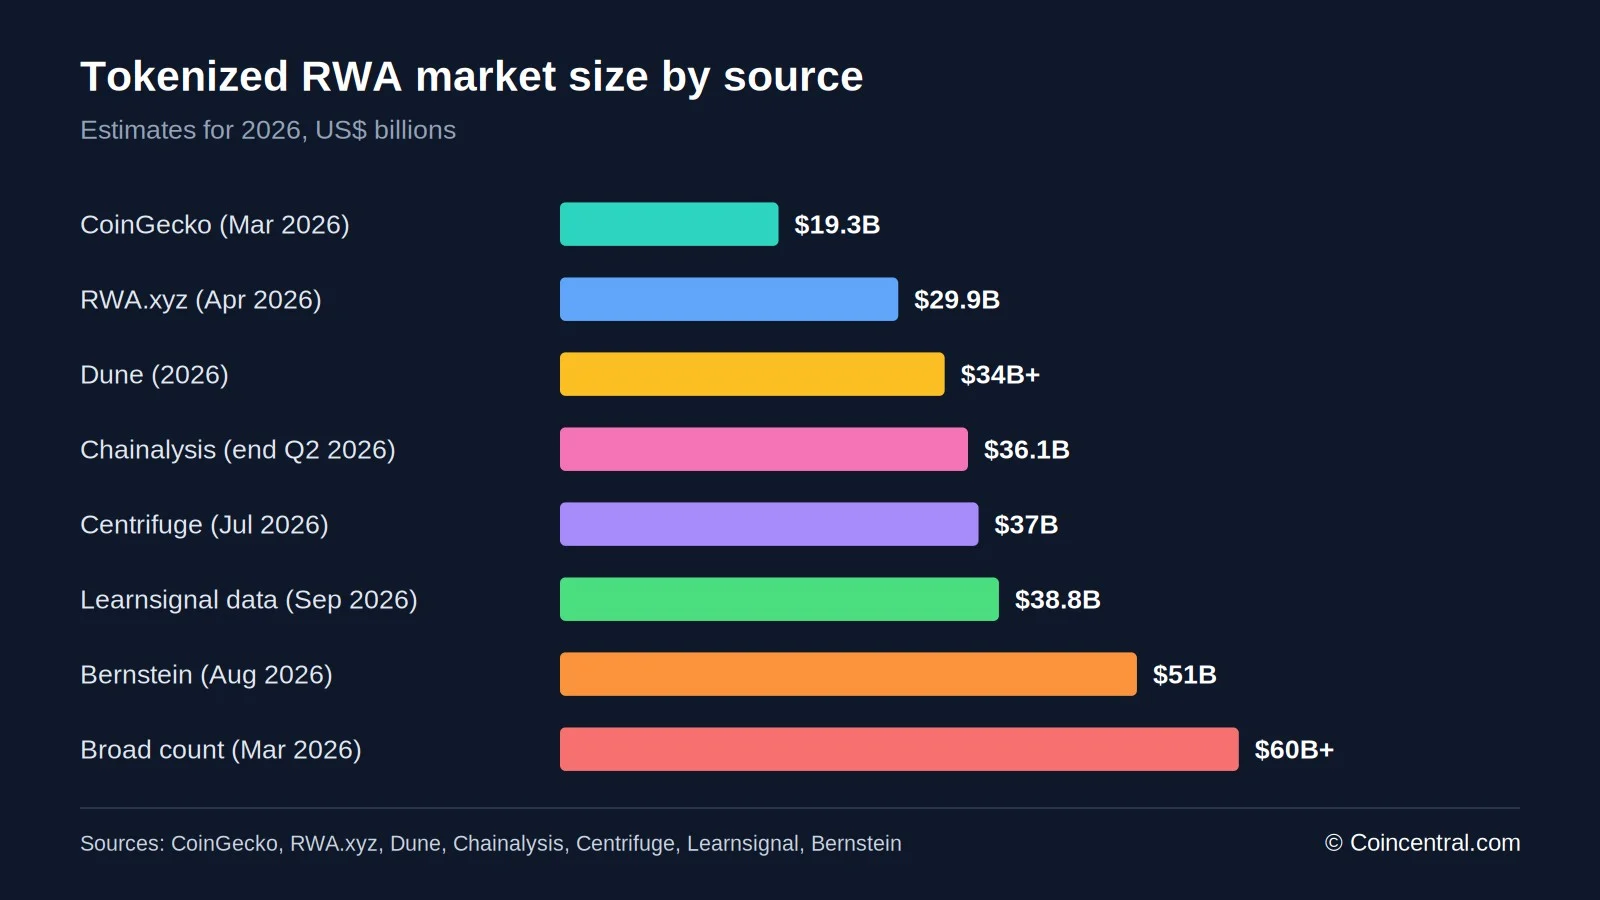
The market expanded quickly through 2026, yet its headline size remains a matter of definition. Depending on the tracker consulted, estimates run from roughly $19 billion to more than $60 billion, because providers draw the boundaries in different ways. Drawing on several recent reports, this article maps out where the market stands today.
Value is heavily concentrated. Tokenized Treas dominate, private credit ranks second, and real estate remains marginal. The sections below examine market size, growth rates, flagship products, asset classes, holders, on-chain lending, tokenized equities and long-range forecasts.
How Big Is the Tokenized RWA Market in 2026?
No single, agreed figure exists. Tracked data cited by Learnsignal as of mid-September 2026 shows about $38.8 billion in tokens distributed on-chain. Those tokens represent underlying assets worth around $365 billion — roughly $305 billion once stablecoins are excluded.
Other trackers land in a similar band for distributed assets. Chainalysis sized the market at $36.07 billion at the end of the second quarter of 2026. Dune reported that total supply crossed $34 billion during the year, while Centrifuge recorded an increase from about $25 billion to $37 billion over the first seven months.
Counts at both ends diverge. CoinGecko measured market capitalization of $19.32 billion in March 2026. Bernstein, cited by CoinDesk, put about $51 billion of tokenized assets on-chain, and the broadest definitions have produced totals above $60 billion.
The discrepancies stem from method. Market capitalization captures the circulating value of tokens. Total value locked can sweep in assets held inside smart contracts, including collateral that does not trade freely. Stablecoins are another dividing line: many analysts treat these currency-pegged tokens as a category of their own, so some totals include them while others subtract them. Some trackers also include assets on permissioned chains, while others count only publicly distributed tokens. Chainalysis noted that activity on private networks such as Canton never appears in on-chain holder counts, so the full market may be larger than any single dataset shows.
For scale, CoinDesk Data reported that total stablecoin market capitalization reached $317 billion in March 2026. A distributed RWA market of roughly $30 billion to $40 billion is a small fraction of that figure.
Dates matter as well. The figures above were recorded in different months, and the market moved in between. A March 2026 report will look small next to a September 2026 one, even when both use the same method.
How Fast Is Tokenized Asset Growth?
Growth over the past year is large on every measure. RWA.xyz data shows the market rising from $8.8 billion on April 16, 2025, to about $29.9 billion on April 16, 2026 — an increase of roughly 240%. CoinGecko reported growth of 256.7%, from $5.42 billion in January 2025 to $19.32 billion in March 2026. Yellow.com research cited year-over-year growth of 184% in its mid-2026 count, and Chainalysis reported 135% growth over the prior period for a market that ended the second quarter at $36.07 billion.
The steepest percentage gains came off small starting points. Chainalysis found corporate credit up 3,156% and private equity up 1,340%, but those moves carried each category only from tens of millions of dollars to about a couple of billion. Dune reported tokenized stocks rising more than 2,000%.
Treasuries grew less in percentage terms but added more dollars. Chainalysis logged a 125% rise, from $6.86 billion to $15.42 billion — more than the next three categories combined in absolute terms.
Base effects shape how these numbers read. A category climbing from $50 million to $1.5 billion posts an enormous percentage gain while adding little to the total. Readers should weigh the dollar change alongside the percentage.
Short-term data shows the mix is still shifting. Learnsignal's 30-day figures for September 2026 had tokenized stocks growing more than 17%, the fastest category, while tokenized Treasuries slipped slightly over the same stretch.
Tokenized US Treasuries: The Largest Category
US government debt is the biggest tokenized asset class. Chainalysis counted $15.42 billion on-chain in the period ending mid-2026, or 42.8% of all tokenized RWA value. Learnsignal's September data puts the figure near $15.7 billion, roughly 40% of the market.
Lower counts exist too. MetaMask, citing RWA.xyz, listed about $12.88 billion in early April 2026, up from roughly $5 billion in late 2024. Astraea Law found tokenized Treasury funds crossing about $15 billion by mid-May 2026.
Three products stand out. BlackRock's BUIDL fund holds roughly $2.7 billion, and BeInCrypto placed its market cap at $2.8 billion on August 31, 2026. Circle's USYC holds around $2.6 billion, and Franklin Templeton's BENJI fund is also reported at $2.6 billion.
These products hold short-term government securities and issue tokens representing a claim on the pool. MetaMask lists typical yields of about 3% to 5%, with daily redemption common. Some tokens rise in price as interest accrues, while others hold a price near $1 and instead add tokens to the wallet.
Learnsignal offers a useful clarification of what actually changes. The legal exposure is familiar, since a tokenized Treasury fund still holds Treasury bills. What changes is the record-keeping layer: transfers can settle in minutes rather than days, and the token can serve as collateral without a separate custody handoff.
The risks sit mostly in the token layer. The underlying debt carries little credit risk, but holders face counterparty, smart contract and redemption delay risk. Separately, Franklin Templeton has received SEC no-action relief allowing its mutual funds and ETFs to invest in BENJI, with implementation possible as early as the fourth quarter of 2026.
Tokenized Assets by Category
Each category behaves differently. MetaMask, using RWA.xyz data from early April 2026, lists Treasuries at about $12.88 billion and commodities at about $7.37 billion. Private credit stood near $5 billion in distributed value, though broader counts reach $18 billion to $19 billion.
Commodities are almost entirely gold. Tether Gold holds about $2.7 billion and Paxos Gold about $2.4 billion, together roughly 74% of the category. These tokens pay no yield, so returns depend on the gold price.
Real estate is the smallest of the major categories. Learnsignal puts it at about $226 million, less than 1% of the tracked market — striking, given that real estate is among the most cited use cases in industry commentary. Forecasts for the sector are far larger: Deloitte projects $4 trillion in tokenized real estate by 2035, a figure that shows how early the category remains.
Higher yields come with higher risk. MetaMask noted that stress in the broader private credit market in March 2026 demonstrated how weak loans can affect tokenized products. Lockup periods are common, and secondary market trading is thin — together, they can leave a holder unable to exit a position quickly.
Who Holds Tokenized Assets
The holder base is global. Chainalysis found that US holders make up 11.7% of the global tokenized RWA holder base and 11.4% of its value. Tokenized Treasuries break the pattern. By value, Italy accounts for 29.9% of geolocated tokenized Treasury holdings, Portugal holds 18.8% and Singapore 18.2%, while the United States ranks fourth at 10.5%.
Holder counts tell a different story. Japan leads with 16.4% of holders but just 0.4% of value. Chainalysis reads this as a small group of large foreign holders driving value, with a wider retail base building small positions.
The issuers are mostly large traditional firms. Learnsignal lists BlackRock, Franklin Templeton, Apollo, Hamilton Lane and WisdomTree among the main builders — asset managers rather than crypto startups.
Ethereum remains the dominant network. MetaMask reports that it hosts over 56% of all tokenized asset value as of April 2026. Stellar, Solana, Polygon, Avalanche, Arbitrum, Base and BNB Chain also host products.
Chainalysis adds a policy point. A holder outside the United States who buys a tokenized Treasury product creates demand for US government debt rather than for their own government's debt. Tokenization also changes who can buy: by lowering minimum position and removing the need for a US brokerage relationship, a wholesale instrument becomes one a retail holder in Lisbon or Singapore can purchase directly.
Private Credit and On-Chain L
Lending data shows how tokenized assets are actually used. Dune found that credit assets make up about three-quarters of all real-world assets deposited in decentralized lending, while only a tiny fraction of tokenized Treasuries is used that way.
Chainalysis reached a similar result. Private credit accounts for 77% of all value lent against tokenized RWAs, and the number of wallets lending private credit grew 1,618% over the period. Commodities lending rose 875%. Treasuries moved the other way and fell 23% — the only category to contract.
Chainalysis ties the split to liquidity. Private credit is hard to sell in untokenized form, so a token that can be posted as collateral is worth more to its holder. Treasuries are already the most liquid collateral in traditional finance; a holder who wants cash against them has established ways to get it.
Yield is another driver. Dune CEO Frederik Haga said tokenized private credit lets investors earn interest while using the same assets as collateral to borrow and fund other trades. MetaMask lists typical private credit yields of 8% to 15%.
Private credit also looks larger in some datasets. Bernstein, cited by CoinDesk, said about 47% of $51 billion in tokenized assets is private credit — a category that often sits below the surface of public dashboards.
Tokenized Stocks and ETFs
Tokenized equities are small by value but growing fast in users. Insights4VC tracked distributed tokenized stocks rising from $951 million in March 2026 to $1.89 billion in July. Dune reported that active holders passed one million. Other datapoints run higher: a figure cited by OneBullEx shows holders rising from 103,000 in January to 1.9 million by September 2026. Ondo Finance's stock platform reached $1 billion in total value locked in May 2026.
Token Terminal data shows tokenized ETFs tripled in size during the year, with market capitalization rising from $219 million on January 1 to $654 million. Holders of tokenized ETFs rose about 51-fold, while holders of individual tokenized stocks rose about 26-fold.
Binance bStocks counts 448,400 holders — half of all tokenized ETF holders — but only 23.3% of market cap, or $160 million. Robinhood has 13.1% of holders and 5.4% of capital. Ondo Finance holds 47.4% of capital, or $325.7 million, from only 20.3% of holders.
Users prefer single companies over funds. Dune estimates that individual stocks make up 81% of tokenized equities held in spot markets, and their value grew ninefold in a year — a reversal of the pattern on traditional markets, where more than 6,000 US-listed ETFs now outnumber individual stocks.
The Token Terminal data also shows overlap. Products tracking the S&P 500 and Nasdaq-100 have a combined value of about $330 million, nearly half the sector total. Because several issuers offer similar exposure on different chains, demand for one index is split across near-identical tokens.
Liquidity remains a limit. MetaMask notes that order books for most tokenized stocks are much thinner than for traditional shares. The SEC said on January 28, 2026, that existing securities laws apply whether ownership is recorded on-chain or off-chain.
Forecasts, Regulation and Risks
Long-term forecasts vary widely. BCG and ADDX project a $16.1 trillion opportunity by 2030, while McKinsey's base case is about $2 trillion in tokenized market capitalization by the same date — a gap of roughly eight times between two institutional forecasts. Today's distributed market stands near $38.8 billion. Any single projection should be treated as an estimate, not a settled fact.
Rules differ by region. The US House Financial Services Committee held a hearing on March 25, 2026, on the Modernizing Markets Through Tokenization Act of 2026. No comprehensive federal framework exists, and the SEC works case by case, including the Franklin Templeton relief and a pending Ondo filing. The EU treats tokenized securities as financial instruments under existing law and licenses service providers under MiCA — a regime OneBullEx describes as clearer, though demanding. Firms operating across borders face questions about which rules apply.
The risks are practical. An arXiv study covering December 2025 to May 2026 found signs of illiquidity in some tokenized markets. Tokenized funds are also spread across networks that cannot share collateral without a bridge.
Infrastructure may drive the next phase. The NYSE has announced plans for 24/7 trading and instant settlement, and Franklin Templeton is working with DigiFT and Binance on wider institutional use.
What the Statistics Show
The tokenized RWA market is real and growing, but it is still narrow. Distributed value sits in the range of $30 billion to $40 billion on most trackers, and Treasuries account for about 40% of it. Private credit comes next, while real estate is under 1%.
Growth is fastest in stocks and ETFs, driven by retail users on large platforms, yet capital still sits with a smaller group of large holders — a gap between holder counts and dollars that repeats across ETFs, Treasuries and stocks. Forecasts for 2030 range from $2 trillion to $16.1 trillion, and readers should compare sources carefully, because each tracker defines the market differently. This article is for information only and is not financial advice.
Several developments could change the picture in the coming months: the SEC response to Ondo's filing, Franklin Templeton's plan to place BENJI inside traditional funds, whether NYSE round-the-clock trading leads to tokenized listings, and whether the Modernizing Markets Through Tokenization Act moves beyond its March 2026 committee hearing. Each would change how easily assets move between old and new markets.
Sources
- Real-World Asset Tokenization Explained: Where the Market Actually Stands in 2026 (Learnsignal)
- North America: Inside the Growth of Agentic Commerce (Chainalysis)
- RWA categories in 2026: tokenized Treasuries, stocks, commodities, and more (MetaMask)
- New report finds that rapid expansion of tokenization is giving rise to new styles of investing (Fortune)
- Tokenized ETFs Triple in Size as Retail Adoption Outpaces Capital Growth (Richard Salmond)
- Tokenized Treasuries Drive RWA Market Past $30 Billion In Early 2026 (OneBullEx)
- Stablecoins & Tokenized Assets Report March 2026 (CoinDesk Data)
This article is based on reporting originally published by Blockonomi.

