Stock Ownership in 2026: Boomers Hold Most Wealth as Younger Generations Trade More
Key Takeaways
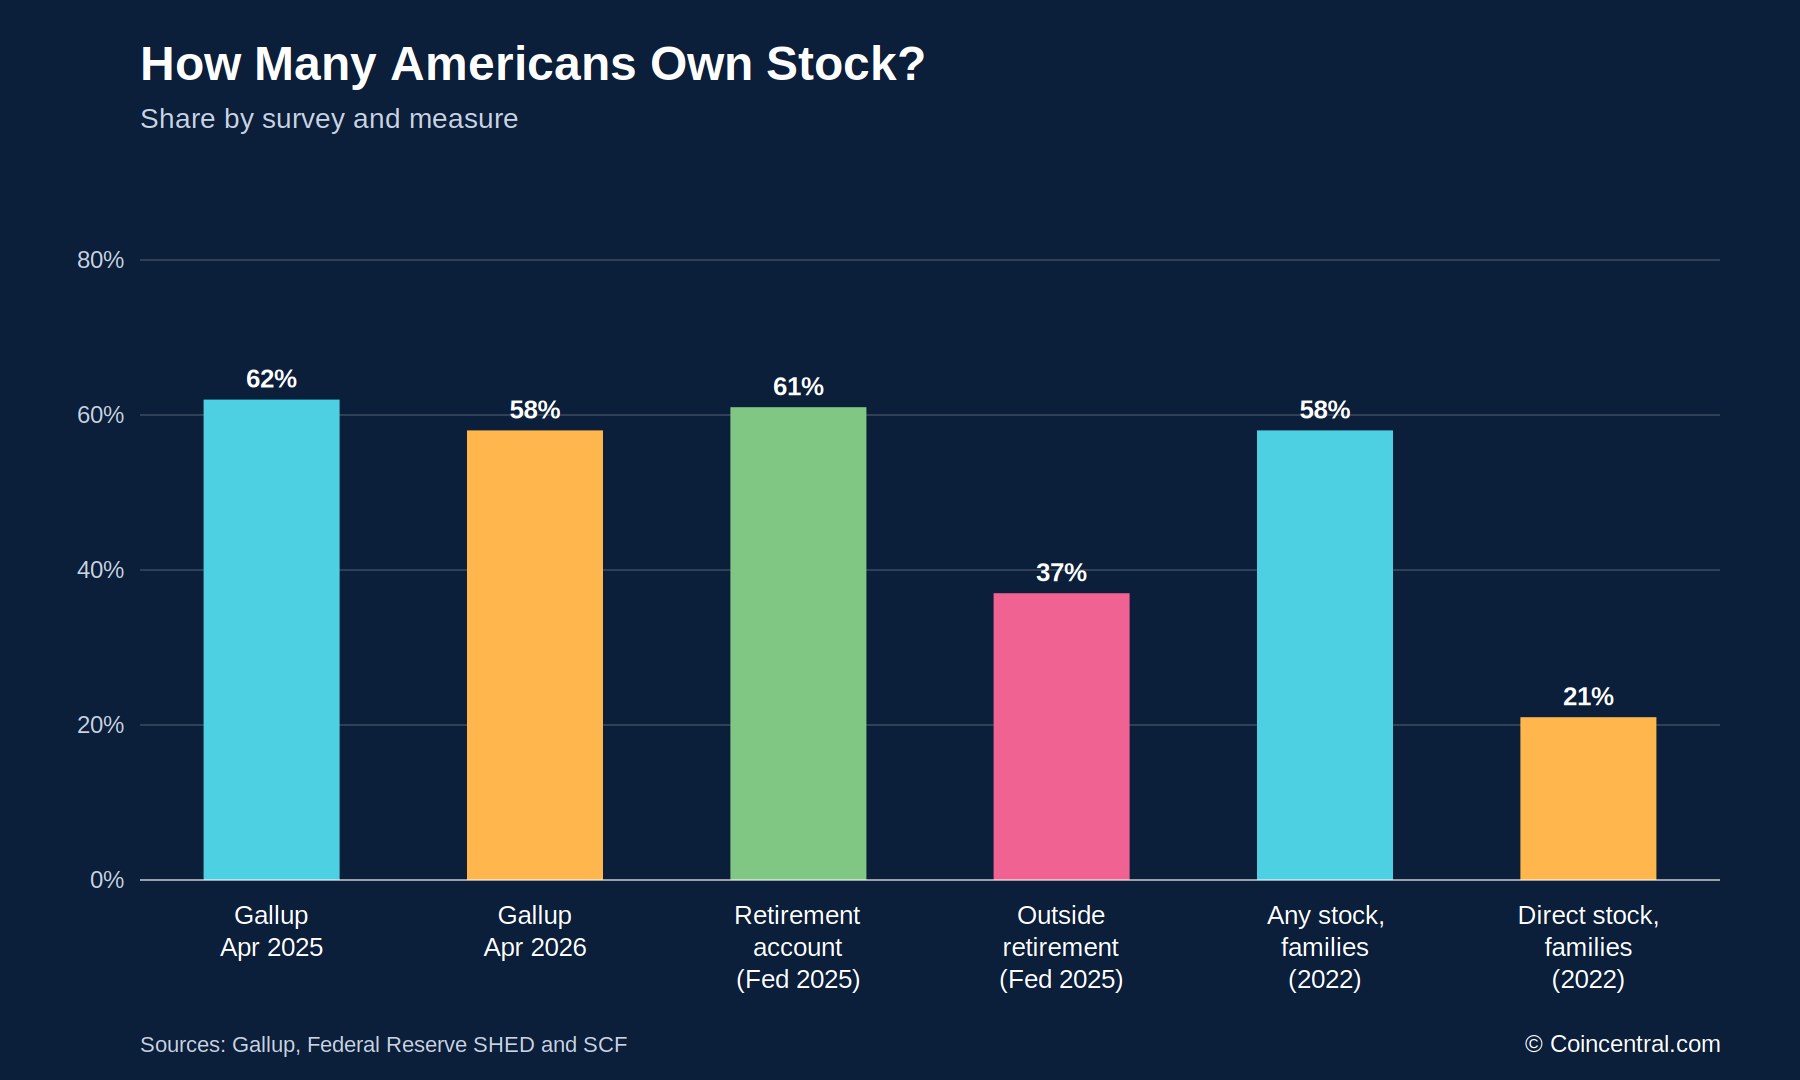
- •Gallup's April 2026 survey found that 58% of U.S. adults owned stock, down from 62% the prior year and marking the first decline since 2016.
- •The wealthiest 1% of Americans hold roughly 50% of all equities, worth about $27.6 trillion, while the bottom 50% by net worth own about 1%.
- •Baby boomers held 54% of U.S. equities in the first quarter of 2026, compared with 22% for Gen X and 9% for millennials.
- •Younger investors are expanding retirement savings, with Gen Z IRA contributions rising 65% year over year in the first quarter of 2026 according to Fidelity, while millennial contributions rose 31%.
- •The Motley Fool survey of 2,000 investors showed AI-related stock ownership at 68% among Gen Z and 65% among millennials, versus 38% among baby boomers.
Stock ownership in the United States remains unevenly distributed across age and wealth groups. Older Americans hold most of the market value, while younger investors trade more frequently, use different tools and show stronger interest in areas such as artificial intelligence.
This review draws on data from Gallup, the Federal Reserve, The Motley Fool’s survey of 2,000 investors and several other reports. It examines how many Americans own stocks, where the value is concentrated and how investment behavior differs among baby boomers, Gen X, millennials and Gen Z.
The surveys use different definitions and methodologies. Some include stocks held through retirement accounts or mutual funds, while others focus on direct ownership. The figures below identify their sources where relevant so the differences can be compared. That distinction matters because broad participation in the market does not mean that households have equal exposure to its value or to the decisions involved in managing investments.
58% of U.S. Adults Owned Stock in 2026
Gallup’s April 2026 survey found that 58% of U.S. adults owned stock, equivalent to about 156 million people. The figure fell from 62% a year earlier and marked the first decline since 2016.
Gallup includes shares held directly and those held through mutual funds, index funds or self-directed retirement accounts. Most Americans who qualify as stock owners hold their exposure inside retirement plans rather than through a standard brokerage account.
The Federal Reserve’s 2025 Survey of Household Economics and Decision-making illustrates the distinction. It found that 61% of adults had a retirement account, including a 401(k), IRA or Roth IRA. By contrast, 37% held stocks, bonds, exchange-traded funds or mutual funds outside a retirement account.
The Federal Reserve’s Survey of Consumer Finances provides a longer historical perspective. In 2022, 58% of families held stock in some form, but only 21% owned individual shares directly. Direct ownership has remained close to 20% for roughly three decades.
The distinction affects how ownership is measured. Someone whose 401(k) is invested in an index fund is counted as a stock owner even if that person never places a trade. People who buy individual shares directly make more active decisions and tend to be older and wealthier.
Wealthy Households Hold Most of the Market Value
Participation and value are separate measures. Federal Reserve data show that the wealthiest 1% of Americans hold approximately 50% of all equities, worth about $27.6 trillion in the first quarter of 2026.
The top 10% by wealth held 87% of equities, valued at about $48 trillion. The bottom 90% held the remaining 13%, a smaller share than the top 1% held alone. The bottom 50% by net worth owned about 1% of stocks, worth roughly $590 billion.
As a result, a 20% annual gain in the S\u0026P 500 would produce about half of its dollar gain for the top 1%, even though many other households also have some exposure through retirement plans or funds.
Holdings are relatively modest even among families that own stock. The median value was $52,000 in 2022 when mutual funds and retirement accounts were included. Among families that held shares directly, the median was $15,000, the lowest level recorded in that survey.
The difference reflects the shift toward fund-based investing. Retirement plans and mutual funds have given more families some market exposure, while direct shareholders continue to account for a larger portion of the gains associated with rising share prices.
Baby Boomers Hold 54% of U.S. Equities
According to the Federal Reserve’s Distribution of Financial Accounts for the first quarter of 2026, baby boomers held 54% of all U.S. equities, worth $29.71 trillion. Gen X held 22%, or $12.23 trillion, while millennials held 9%, or $4.94 trillion.
The Federal Reserve release did not provide a separate equity figure for Gen Z. However, the 2025 Survey of Household Economics and Decision-making found that 36% of Gen Z held stocks through a retirement account and 20% held stocks outside one.
Households headed by people under 40 owned about 6% of equities. That share had doubled during the decade, while the value of their stock holdings had increased about threefold since 2020, according to data cited by investment writer Ben Carlson.
Boomers therefore held more than half of the country’s equities, while Gen X and millennials together held less than one-third. The distribution is consistent with the number of years each generation has had to earn income, save and allow investments to compound.
Net Worth Rises Sharply With Age
Federal Reserve Survey of Consumer Finances reports show a close relationship between age and household wealth. Households headed by someone aged 65 to 74 had a median net worth near $1.2 million. Households headed by someone under 35 had a median below $15,000.
Gen X households, generally headed by people aged 44 to 59, had a median net worth of about $450,000. Millennials, roughly aged 28 to 43, had a median near $130,000. Households headed by people aged 65 to 74 controlled about one-third of total U.S. household wealth.
Average net worth is higher than median net worth because older households hold substantial amounts of stock and real estate. Younger groups continue to have lower homeownership and stock-market participation rates, although low-cost brokerages and robo-advisors have created additional routes into the market. The SEC has noted the increasing use of those services among younger investors.
Canadian data show a similar age-related pattern, although they describe a different national market. Statistics Canada found that a typical Gen X head of household at age 40 had about $500,000 in assets and $100,000 in debt. A baby boomer at the same age had less than $300,000 in assets and about $30,000 in debt.
Statistics Canada also reported that Canadian millennials aged 25 to 34 had a median net worth of $70,600 in 2019, almost twice the level recorded for Gen X at the same age.
Younger Americans Are Using Retirement Accounts More Often
High housing costs, student loans and inflation continue to affect younger Americans. Even so, available data indicate increasing use of tax-deferred retirement accounts.
The share of IRA accounts held by people under 30 has nearly doubled over the past 10 years, based on Wall Street Journal data cited by Carlson. Fidelity Investments reported that Gen Z IRA contributions rose 65% year over year in the first quarter of 2026, while millennial contributions increased 31%.
Three-quarters of people aged 35 and under selected Roth accounts, compared with fewer than half a decade earlier.
Historical data provide additional context. Only 4% of U.S. households owned stocks in the early 1950s. The figure reached 19% by the early 1980s and rose rapidly during the 1990s. By 2022, 58% of families held stock in some form.
Carlson has cited lower barriers to entry as one factor behind wider participation. Technology has simplified investing, fees have declined and minimum balances have largely disappeared. He has also said that expensive housing may leave some younger people with more cash to invest in stocks because they are unable to buy homes.
Carlson argues that more people should be invested and that beginning earlier gives gains more time to compound in retirement accounts when the money remains invested for decades.
AI Stocks Show the Largest Generational Difference
The Motley Fool surveyed 2,000 U.S. investors aged 18 and older. About 59% said they held AI-related stocks. Ownership was higher among younger investors: 68% for Gen Z and 65% for millennials, compared with 48% for Gen X and 38% for baby boomers.
Younger holders were also more likely to describe themselves as long-term investors in AI stocks. The survey found that 43% of millennials and 41% of Gen Z identified as long-term holders. Only 10% of Gen Z and 10% of millennials said they had no plans to buy AI stocks, compared with 19% of Gen X and 35% of boomers.
Expectations about AI’s effect on market returns differed by age. About 73% of millennials and 67% of Gen Z expected a positive effect over the next 10 years. Among boomers, 42% expected a positive effect and 16% expected a negative one, the highest negative response of any generation.
Across all respondents, 56% expected AI stocks to outperform the broader market over the next decade. About 22% of Gen X and 22% of boomers said AI gains were already priced in, compared with 14% of millennials.
A separate question about sector ownership produced an even wider gap. AI-related stocks were held by 74% of Gen Z and 69% of millennials, compared with 53% of Gen X and 39% of boomers. That was the largest generational difference among the sectors included in the survey.
Growth Stocks and Speculative Holdings Appeal More to Younger Investors
Growth stocks were the most common category overall, held by 57% of investors. They were the leading choice for Gen Z at 61%, millennials at 58% and Gen X at 55%.
Younger investors were also more likely to report owning value stocks. The share was 51% for Gen Z and 43% for millennials, compared with 32% for both Gen X and boomers. Younger investors were more than twice as likely to hold speculative assets such as penny stocks or meme stocks.
Older investors showed greater preference for large, established companies. About 48% of boomers held U.S. stocks, compared with 35% of Gen Z. Boomers and Gen X also reported higher ownership of oil and gas stocks, bank stocks and biotech or medical-device stocks.
Generations differed on the number of holdings needed for a high-performing portfolio. Some 37% of Gen Z said one to five stocks could form such a portfolio, compared with 24% of boomers. Meanwhile, 22% of boomers said a strong portfolio required more than 20 stocks, compared with 8% of Gen Z.
The Motley Fool recommends holding at least 25 stocks across several industries, while also saying that the appropriate number depends on risk tolerance and how closely an investor wants to monitor each position.
Thematic stocks, including AI, clean energy and biotech, were held by 9% of boomers and 11% of Gen X. The figures were 5% for Gen Z and 7% for millennials. The source also noted that younger investors may favor broader holdings such as growth stocks and index funds.
Gen Z and Millennials Trade More Frequently
Trading frequency varies sharply by generation. About 47% of Gen Z and 39% of millennials said they traded at least once a week, compared with 22% of Gen X and 15% of baby boomers.
Daily trading was reported by 15% of Gen Z and 13% of millennials. Gen X and boomers each recorded a 6% rate. At the other end of the scale, 60% of boomers traded less than once a month, compared with 12% of Gen Z.
Frequent trading can involve transaction fees, short-term capital-gains taxes and the possibility of emotionally driven decisions. Research has consistently found that most active traders perform worse over time than a simple buy-and-hold strategy.
When choosing stocks, all four generations ranked fundamental factors most highly. Competitive advantage, trust in company leadership and dividend payments were among the leading considerations. Social media ranked last, and TikTok creators were the least influential source for every generation.
AI tools, including ChatGPT, ranked seventh among 10 factors overall. Gen Z ranked those tools higher than boomers did, but they remained in the middle of the list.
Paid advisory services had somewhat greater importance for older investors. Boomers gave them a 4.9 rating on a 10-point scale, compared with 5.5 for Gen Z. Free investing websites and blogs received similar ratings across generations, ranging from 5.3 to 5.7.
Retirement Is the Main Goal for Older Investors
Retirement was the primary investment goal for 71% of baby boomers and 61% of Gen X. The corresponding figures were 42% for millennials and 33% for Gen Z.
Retirement savings was still the most common single goal for Gen Z, at 24%. Long-term wealth building followed at 19%, well above the 9% reported for Gen X and 7% for boomers.
Saving for a major purchase, such as a home or car, was more common among younger investors. The share was 9% for Gen Z and 4% for millennials, compared with 2% for Gen X and 1% for boomers.
The financial-independence, retire-early movement, commonly known as FIRE, was most popular with Gen X at 5%. Interest in the concept was similar across all four generations.
Dividend Strategies and Learning Sources Differ by Age
Dividend stocks were present in portfolios across all generations. Between 14% and 16% of investors in each group held more than half of their portfolio in dividend stocks, although for most investors the category represented less than half of total holdings.
Reliable income was the leading reason Gen Z and millennials gave for owning dividend stocks, at 45% and 44%, respectively. Long-term compounding was cited by 43% of both groups, compared with 31% of boomers.
Older investors were more likely to reinvest dividends automatically. About 61% of boomers did so, compared with 53% of Gen X, 41% of millennials and 30% of Gen Z. Younger investors were more likely to spend the income.
More than half of Gen Z, or 57%, and 52% of millennials viewed dividend investing as a side hustle or alternative to gig work. The shares were 29% for Gen X and 16% for boomers.
The sources investors used to learn also differed. YouTube was used by 67% of Gen Z and 56% of millennials, compared with 26% of Gen X and 14% of boomers. TikTok was used by 47% of Gen Z and 4% of boomers. Reddit was used by 29% of Gen Z and 3% of boomers.
Half of boomers, or 50%, turned to a financial advisor for dividend advice, compared with 24% of Gen Z.
Earlier Studies Show Differences in Risk and Values
A 2022 Statista survey asked respondents how they would invest $100,000. Nearly half of baby boomers and members of the Silent Generation chose stocks. The share was 53% for Gen X, 63% for millennials and 81% for Gen Z.
A 2022 Stanford study found that two-thirds of investors aged 58 and older were only somewhat concerned, or not concerned at all, about environmental and social issues. About two-thirds of millennial and Gen Z investors said they were very concerned about those issues.
Savings behavior also varied. A 2022 State Street Global Advisors study found that one in 20 Gen X investors reduced retirement contributions because of inflation, compared with 18% of millennials and 11% of boomers.
An April 2021 Motley Fool survey found that about 73% of Gen Z owned stocks and that cryptocurrency was also popular among the group. A 2017 Accenture report found that 67% of millennials wanted computer-generated recommendations as part of their investment strategy.
Younger investors have not always adopted newer tools as widely as perceptions suggest. A 2020 Morningstar survey of 1,300 Americans aged 18 to 25 found that only 18% had used a robo-advisor, while about three in 10 had met with a human financial advisor.
Because some of these studies are several years old, they provide background rather than current measurements. The newer figures from Gallup, the Federal Reserve and The Motley Fool offer a more current view of 2026.
Overall, the data show that boomers and Gen X control most of the market value and tend to favor steadier, longer-term investment habits. Gen Z and millennials own a smaller share of total equities, but they trade more often, report higher ownership of AI-related stocks and are increasing their use of retirement accounts.
Overall stock ownership fell to 58% in 2026, while wealth remained concentrated among the richest households. Future surveys will indicate whether younger investors continue to narrow the ownership gap.
Source: CoinCentral

