Sky's $4.4 Billion Liquidity Disclosure Shows Why USDS Cash-Outs Need a Separate Bank Route
Key Takeaways
- •Sky.money reported more than $4.4 billion in stablecoin liquidity in its Peg Stability Module on Oct. 9, enabling one-for-one conversion between USDS and USDC with no protocol swap fee or slippage on the direct leg.
- •Borrowing against collateral, migrating legacy tokens, and swapping through existing inventory can each raise stablecoin token counts without any matching inflow of new bank dollars.
- •Sky recorded roughly $1.6 billion in cumulative USDC-USDS routing volume on Uniswap by Oct. 6, a turnover figure that includes two-way and repeated conversions and does not measure net issuance.
- •Circle's MiCA-based redemption, last updated Sept. 15, requires eligible EEA retail holders to pass eligibility, identity and transaction checks and hold an EEA bank account, with a five-business-day redemption timeframe unless discrepancies arise.
- •Converting USDS into USDC through the PSM completes only the token-conversion leg, and an actual cash exit still depends on the issuer's banking route and the inventory available at the time of the transaction.
Sky's $4.4 Billion Liquidity Disclosure Shows Why USDS Cash-Outs Need a Separate Bank Route
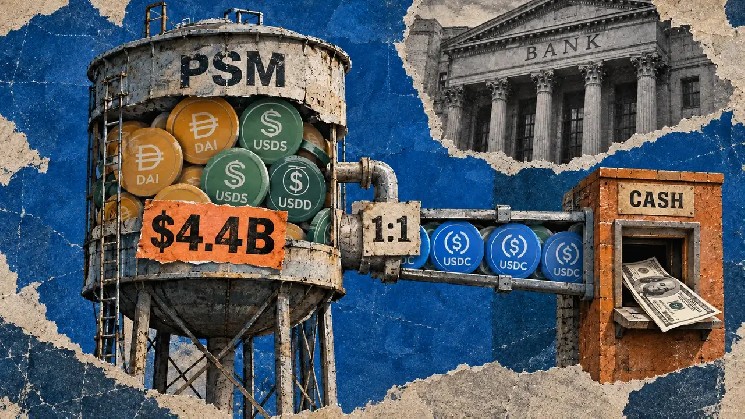
Sky.money reported more than $4.4 billion in stablecoin liquidity held in its Peg Stability Module (PSM) as part of an Oct. 9 explanation of its conversion mechanism. The PSM gives holders a direct route between USDS, the Sky Protocol's dollar-linked token, and USDC at a one-for-one rate.
The disclosure draws a line between metrics that are often conflated, and the distinction matters whenever aggregate token counts are read as evidence of fresh dollar inflows. Token circulation measures the stock of holdings. Conversion inventory measures what a holder can actually receive on a particular exit route. Fresh external dollar demand refers to money entering the token system from outside. Borrowing against collateral and upgrading an existing token can each raise individual token counts without establishing a matching inflow of bank dollars. Likewise, a swap routed through existing inventory merely moves liquidity between holders or between token forms; it does not by itself constitute new issuance.
How the PSM conversion works
Sky describes the PSM as enabling direct USDC and USDS conversion in both directions using liquidity already held inside the protocol. Because the mechanism itself supplies the other side of the trade, it does not need to find a separate trader willing to take the opposite position.
At the settings described in the October explanation, the direct PSM leg carries no protocol swap fee and no slippage. A routed trade can still incur costs elsewhere: if it passes through another token pool before reaching USDC or USDS, that leg follows the pool's own pricing, liquidity and fees.
The $4.4 billion figure reflects aggregate stablecoin liquidity as disclosed on Oct. 9. An actual USDS exit depends on the USDC inventory available on that route at the moment of the transaction.
Sky also reported roughly $1.6 billion in cumulative USDC-USDS volume processed through routing on Uniswap, a decentralized exchange protocol, by Oct. 6, following its July 8 integration. Cumulative turnover can include flows in both directions and repeated conversions, so it does not measure net USDS issuance or new dollars deposited into crypto.
Borrowing and migration change what a supply increase means
A separate converter on Ethereum connects DAI and USDS. According to Sky's developer documentation, the two tokens share a single issuance source, and holders can convert between them in either direction without liquidity restrictions. That statement applies to the DAI-USDS converter, not to the availability of USDC in the PSM.
The accounting implication is straightforward: a holder can change the denomination of an existing position. An increase in USDS considered on its own therefore need not represent additional money entering the wider system. Understanding the economic change requires tracking the DAI side of the conversion as well.
USDD, a separate collateral-backed stablecoin, adds two more routes through which a token count can change: borrowing and migration. Its vault documentation describes depositing collateral, minting USDD as debt, and repaying the tokens plus stability fees to release the collateral. Users can also withdraw collateral while maintaining sufficient coverage. This creates spendable liquidity for someone who wants to keep a collateral position, alongside an obligation to repay.
The borrower's new capacity to transact is economically useful, but because it is created against assets already held, each newly issued token does not require a corresponding new deposit of bank dollars. The pledged assets support the debt; their valuation is a different measure from the stablecoin inventory available to satisfy an immediate conversion request.
USDD also offers a migration route from USDDOLD into an equivalent amount of new USDD, subject to gas costs and with no deadline. In that case, a higher balance of the new token can simply reflect an upgrade of an existing holding. Comparing old and new contracts in isolation can obscure whether the underlying economic position has actually grown.
A meaningful supply comparison therefore requires consistent observation times and clearly stated token coverage, including how legacy tokens and holdings that back other tokens are treated.
USDD's PSM instructions make the immediate constraint explicit. The mechanism offers one-for-one conversion between USDD and supported stablecoins, with no service fee beyond network gas costs. Users must check the displayed quantity of the target token and keep their swap within that available amount. A holder seeking USDT, Tether's dollar-linked token, needs the inventory that can actually deliver USDT; an aggregate collateral valuation cannot substitute for that balance, just as a debt position's backing cannot automatically be treated as an uncommitted pool of redemption cash.
Receiving USDC is a separate step from receiving bank dollars
Circle, the issuer of USDC, describes a more direct fiat connection in its USDC issuance and redemption process. Eligible businesses deposit dollars into Circle accounts to obtain newly minted USDC, and returning USDC for dollars removes the redeemed tokens from circulation. Circle says the backing consists of highly liquid cash and cash equivalents, with most reserves invested in the Circle Reserve Fund, whose portfolio can contain short-dated Treasuries, overnight Treasury repurchase agreements and cash.
A purchase on an exchange can instead draw on USDC already held by the exchange. Circle notes that an exchange may mint additional tokens when it needs more inventory, meaning a buyer's demand for USDC does not necessarily trigger a new issuance transaction every time.
Access also differs between a protocol conversion and a bank redemption. Circle Mint is an institutional product that is unavailable to individuals and small businesses through that service. Eligible retail holders in the European Economic Area have a separate direct route via Circle France.
Circle's redemption policy under the Union's Markets in Crypto-Assets Regulation (MiCA), last updated Sept. 15, requires eligibility, identity and transaction checks, along with an EEA bank account capable of accepting USD for a USDC redemption. For eligible EEA retail holders, the policy sets a five-business-day timeframe unless discrepancies arise. It also permits deferrals during a stress event that prevents reserve rebalancing between Circle France and Circle LLC.
For a USDS holder seeking bank dollars, obtaining USDC through the PSM completes only the token-conversion leg. The issuer and banking route must still complete the cash leg. Each leg is defined by its own dated disclosure — the Oct. 9 liquidity figure on the conversion side and the Sept. 15 policy update on the issuer side — and the balance available for an actual exit is the one shown at transaction time, not the published snapshot. A stablecoin conversion balance and a bank payment remain separate stages of access to dollars.
This article is based on an analysis originally published on CryptoSlate.

