Silver's Unsung Strength: Resilience After the Parabolic Collapse
Key Takeaways
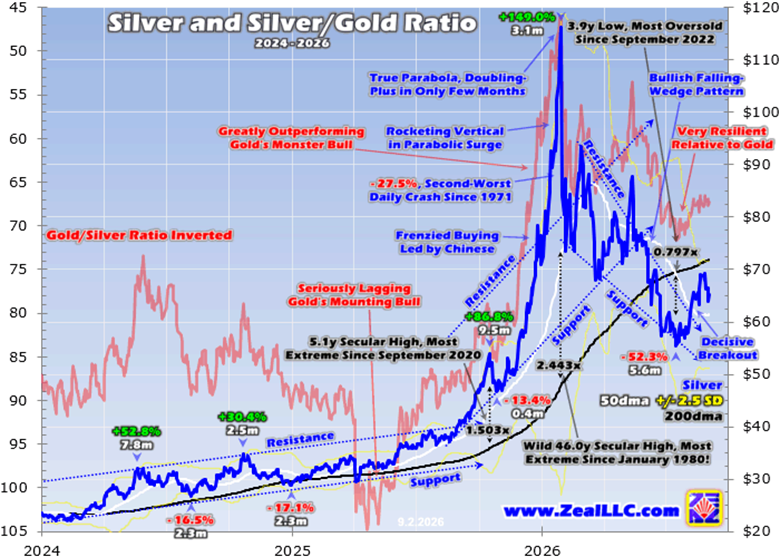
- •Silver peaked near $116 per ounce in late January 2026 after a 455.2% bull run over 27.8 months, then fell as much as 52.3% over 5.6 months to a mid-July bottom above $55.
- •Silver's initial post-peak crash of 27.5% in one day was its second-worst daily decline on record going back to 1971.
- •Despite the selloff, silver averaged nearly $74 in 2026 through early September, up 116.7% from the comparable 2025 period, and remained up 46.7% year-over-year at its mid-July low.
- •The silver/gold ratio has averaged 65.4x since May 2026, silver's strongest showing relative to gold in about a dozen years outside the parabolic anomaly.
- •The author argues that bearish sentiment rooted in recency bias is misplaced, and that silver miners remain substantially profitable with stocks trading at low valuations.
By Adam Hamilton — September 4, 2026
Silver sentiment has felt decidedly apathetic to bearish recently, with traders wanting little to do with the metal. That reaction is understandable after silver was more than cut in half earlier this year. Yet despite that perception, silver is showing considerable unsung strength. It weathered a dangerous post-parabola collapse relatively well and remains quite high compared with its own history and its primary driver, gold. Such resiliency is bullish.
The Parabolic Peak
In late January, silver skyrocketed alongside gold to an all-time high near $116 per ounce. That climax capped a spectacular bull run of 455.2% gains over 27.8 months, outperforming gold's parallel record cyclical bull by amplifying its gains 2.3x. Silver's performance was far from uniform, however: it lagged gold early on before shooting parabolic near the end to catch up. That terminal moonshot was wild — in just 3.1 months into the late-January peak, silver catapulted 149.0% higher.
As the author warned in mid-January, about a week before silver's climax, that was a dangerous extreme parabola — defined, after decades of studying market history, as doublings within two-to-three months following massive bull runs. Such one-sided, popular-speculative-mania, greed-fueled moves always end badly.
The infamous January 1980 episode offers the benchmark. Back then silver skyrocketed 196.1% in just 2.0 months into its peak; those levels would not be seen again until 31.3 years later in April 2011. By March 1980, just 2.2 months after that climax, silver had crashed 76.9%. The mid-January 2026 essay closed with sober warnings:
"Vertical moonshots are super-risky, nothing to be trifled with. ... Traders should avoid chasing silver's popular-speculative-mania gains, and gird for an imminent big-and-fast selloff."
A bit over a week later, silver stretched an eye-popping 144.3% above its key 200-day-moving-average baseline — a 46.0-year high in overboughtness, the most extreme reading since January 1980.
The Collapse
After such a hyper-risky parabolic moonshot, silver was due for a symmetrical collapse like those following similar past blowoffs, and it arrived swiftly. Right out of the late-January peak, silver crashed 27.5% in a single trading day — its second-worst daily crash on record going back to 1971. The author analyzed its implications in another essay in mid-February.
The aftermath of January 2026's wildest extremes in nearly half a century could have been far worse. Silver could have collapsed 75%+ in its necessary post-parabola reckoning; a three-quarters loss would have driven the price back near $29. Instead, at worst in mid-July, silver fell 52.3% over 5.6 months, bottoming above $55. Given the situation, that is close to best-case territory following an extreme parabola.
At the mid-July low, silver was down 21.9% year-to-date, which contributed to recent bearish herd sentiment. Yet that perspective is myopic, distorted by the post-parabola reckoning: at that low, silver was still up 46.7% year-over-year. And despite the carnage in the half-year into mid-July, silver has averaged nearly $74 so far in 2026 — 116.7% higher than the comparable year-to-date period of 2025 into early September.
Sentiment Blind Spots
It is therefore surprising, if not perplexing, to hear traders and analysts increasingly dismissive of silver. The author, in the financial-newsletter business for over a quarter-century, reports receiving heavy subscriber feedback — and cannot recall a single bullish e-mail on silver in recent months. Everyone writing about silver was disappointed by its collapse and expected the losses to keep mounting.
Several weeks ago, during a podcast interview following a long discussion on gold, the host asked why silver is performing so poorly. The author replied that silver was faring well this year, showing impressive resilience relative to gold — an answer that visibly surprised the host, who moved on.
Maintaining perspective is everything in markets, because humans naturally extrapolate the latest moves into infinity. Psychologists have studied this deeply under names including recency bias, availability heuristic, and hyperbolic discounting. It is a major problem for traders, as emotionally overweighting the present impairs buying low and selling high. A few days, weeks, or even months of price action is insufficient context; the minimum is the past half-year, and after an extreme parabolic-spike anomaly like silver's, that framing must extend to the last few years.
Reading the Silver/Gold Ratio
Gold is silver's dominant primary driver, with gold's price action overwhelmingly fueling silver sentiment and trading. This is partly a function of silver's dual identity: unlike gold, it is both a monetary-focused precious metal and a widely used industrial input, which historically makes it more volatile than gold and prone to amplifying gold's major moves. For readability, the gold/silver ratio with an inverted axis is used rather than the decimal silver/gold ratio (0.015x midweek); it stood at 67.3x on Wednesday.
Had silver merely cratered by half in six months after a normal bull run, it would be catastrophic. But after rocketing 149.0% in 3.1 months to its most-overbought levels since January 1980, being cut in half is quite resilient — post-parabola losses out of nearly-half-century extremes could have reached three-quarters or more.
In July, around the post-parabola bottom, silver averaged a bit over $58 — still 55.0% above the comparable July 2025 average. Had traders been told last year that silver would be at recent levels, they would have been ecstatic. This year's performance only feels weak when viewed myopically from the late-January parabolic climax, an extreme that never had any chance of being sustainable.
During the post-parabola collapse, silver carved a massive bullish falling-wedge chart pattern, parallel to gold's. Such patterns tend to resolve in strong upside breakouts, which indeed happened in gold, its miners' stocks, and silver. Silver's decisive breakout, along with the depth of its mid-July bottom, suggests the setup for a larger move: a bit over $55, silver had plunged to just 79.7% of its 200dma — a 3.9-year low and its most oversold level since September 2022, over a year before its monster bull began. The 52.5% selloff over 5.6 months eradicated the herd greed of the parabolic climax, resetting the technical and sentimental stage.
Silver's unsung strength is most apparent in the silver/gold ratio, which is not widely followed. From January 2020 to September 2023, just before silver's late bull began, the SGR averaged 81.7x — meaning it took 81.7 ounces of silver to equal one ounce of gold — versus longer-term averages around 55x to 60x. From October 2023 to October 2025, before the final three parabolic months into late January 2026, the SGR averaged an even worse 87.3x. Silver seriously lagged gold's record bull for most of its duration; as the author notes, silver was performing so dismally then that he rarely wrote about it.
The three months into and three months after the parabolic peak were an extreme anomaly unseen in nearly half a century: SGR reads averaged 66.5x on the way up and 62.0x on the way down, representative of nothing sustainable. But what came since — starting in May, after the anomaly reversed — reveals silver's strength. Over the latest four-plus months, while sentiment languished and price got sliced in half, the SGR still averaged 65.4x. With the brief exception of the unsustainable parabola, silver has not been this strong relative to gold since mid-2014 — its best showing versus gold in a dozen years, despite the necessary post-parabola collapse.
Miners and a Conservative Scenario
The author's firm added 18 new newsletter trades in fundamentally superior smaller miners as gold bottomed in recent months; by late August, unrealized gains were running as high as +63% in under six weeks. While mostly gold miners, the trades included a major silver miner. It does not report all-in sustaining costs, but its peers' Q2 AISCs ran between roughly $6 and $37 per ounce — and with silver averaging over $73 on close last quarter, mining it remained wildly profitable despite the post-parabola bust. Major and primary silver miners are earning substantial profits while their stocks still trade at low valuations relative to earnings.
Rather than guessing price targets, the author offers a conservative scenario. Silver is overwhelmingly driven by gold, tending to leverage its major moves by 2x+. If gold's young upleg grows into a new bull ascending at a modest 15% annually, that implies 30%+ yearly gains for silver. Assume major-silver-miner AISCs average $25 this year and climb 10% annually: if silver's next bull run starts at July's average near $58, silver miners' earnings would more than double within two years — and two years of 30% gains would carry silver only near $98 per ounce, still well under January 2026's parabolic extreme above $116. (These are the author's illustrative assumptions, not guarantees.)
Traders saddled with recency bias risk missing most of those gains, remaining apathetic or bearish as long as the herd is, unable to buy relatively low while silver stocks are out of favor — and turning bullish only after the next bull run is well underway. The remedy is maintaining sufficient perspective on price action.
The Bottom Line
Silver has shown major unsung strength in recent months. Yes, it was cut in half after its parabolic moonshot, but after such nearly-half-century extremes, losses could have exceeded three-quarters based on historical precedent. The post-parabola reckoning hammered silver back to its most-oversold levels in almost four years, and since then silver has enjoyed a decisive breakout from its massive falling-wedge pattern. Relative to its dominant driver gold, silver is trading at its best levels in over a dozen years. The recent apathy and bearishness toward silver, the author argues, has been myopic and misplaced: silver is faring far better than the herd gives it credit for.
Adam Hamilton, CPA, is president of Zeal LLC, which specializes in contrarian stock-market speculation and investment and publishes financial-market newsletters; its customers have come from all 50 states and more than 60 countries.
Source: GoldSeek
