Fed Rate Pause Likely After Payrolls Add Just 29,000 Jobs in Weakest Month of the Year
Key Takeaways
- •September nonfarm payrolls increased by only 29,000 jobs, well short of the 89,000 consensus forecast, marking the weakest monthly hiring pace of the year.
- •The unemployment rate rose to 4.2% from 4.1%, and July and August job figures were collectively revised down by 60,000.
- •The CME FedWatch tool showed the probability of an October Fed rate increase dropping to about 23%, though Dallas Fed President Lorie Logan suggested rates need to rise at least 50 basis points more.
- •The 10-year Treasury yield hit its highest level since 2002 and the 30-year reached a level last seen in May 2002, while Brent crude fell 4.4% for the week after G7 nations committed to releasing up to 100 million barrels from strategic reserves.
- •Nike declined 3.6% after missing revenue expectations and announcing additional workforce reductions, while Tesla rose 4.7% as third-quarter deliveries of 486,532 vehicles beat the consensus estimate of roughly 462,000.
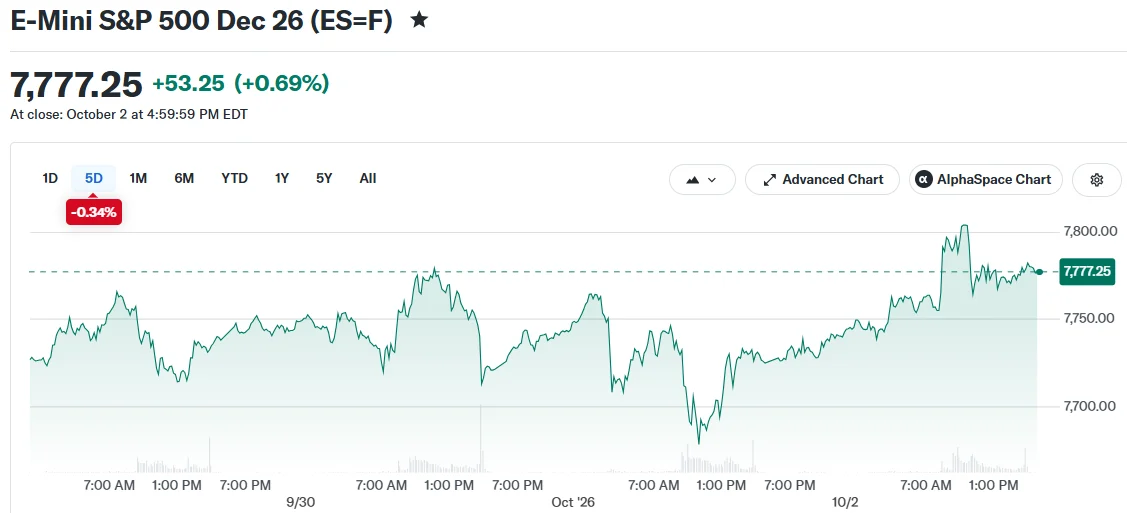
Wall Street ended Friday's session in positive territory, capping a volatile week for equities, after September employment data showed US hiring slowed far more sharply than economists anticipated. The S&P 500 advanced 0.8%, while the Nasdaq Composite surged 1.2% and briefly set a fresh intraday high. The Dow Jones Industrial Average posted a 0.5% gain. Across the full week, however, the Nasdaq was the only major index to close in the green. For markets, economic data often matters as much for its policy implications as for its content, since the expected path of interest rates feeds directly into borrowing costs and equity valuations.
The payrolls report was the centerpiece of a session that also featured sharp moves in individual stocks and commodities. Nike declined 3.6% following disappointing quarterly results and cautious forward guidance, while Tesla climbed 4.7% on better-than-expected delivery figures. Long-dated Treasury yields continued their ascent during the week, with 10-year and 30-year notes reaching levels unseen since the early 2000s, and crude oil retreated after G7 countries committed to releasing emergency stockpiles totaling 100 million barrels.
Employment Data Falls Short of Expectations
Friday's rally followed the release of disappointing September labor market statistics. According to the US Bureau of Labor Statistics, employers added a mere 29,000 nonfarm positions during the month, substantially below the consensus forecast of 89,000 new jobs. The reading represented the weakest monthly hiring pace of the year and the softest monthly job creation since January. The monthly payrolls report is the broadest recurring snapshot of US hiring and one of the key inputs the Federal Reserve weighs when setting policy under its dual mandate of maximum employment and price stability.
BREAKING: The US economy adds +29,000 jobs in September, well below expectations of +89,000. The unemployment rate rose to 4.2%, above expectations of 4.1%. August's job number was also revised down by -29,000 jobs. This marks the third weakest jobs report of 2026.
— The Kobeissi Letter (@KobeissiLetter) October 2, 2026
Revisions to prior months painted an even softer picture. July and August figures were collectively marked down by 60,000 jobs. Meanwhile, the jobless rate increased to 4.2% from the prior month's 4.1% reading.
Compensation growth also decelerated. Average hourly pay increased a modest 0.1% on a monthly basis and 3% year over year, representing the slowest annual advance since May 2021.
Market participants interpreted the lackluster employment data as evidence that the Federal Reserve may maintain its current policy stance at the upcoming October meeting. The CME FedWatch tool showed the probability of an October rate increase declining to approximately 23%. The tool derives those odds from pricing in fed funds futures, the contracts through which traders position for the path of short-term interest rates.
However, certain Fed policymakers have indicated that additional monetary tightening could be necessary to combat persistent inflation. Dallas Fed President Lorie Logan suggested rates might need to climb at least 50 basis points higher.
Treasury Market Diverges From Rate Expectations
Despite diminishing rate-hike probabilities, the fixed-income market continued its selloff throughout the week. Longer-duration Treasury yields extended their climb, with the benchmark 10-year note reaching its highest yield since 2002 and the 30-year bond touching a level last observed in May 2002. Long-term Treasury yields act as a reference rate across the financial system, underpinning pricing for mortgages and corporate borrowing, which is why their climb to multi-decade highs has drawn attention well beyond the bond market.
Market observers attributed the yield increases to several converging forces. Contributing factors included expanding federal debt levels, substantial corporate borrowing to finance artificial intelligence infrastructure investments, and ongoing inflation anxieties.
Oil prices exhibited the opposite trend. Brent crude fell 4.4% over the five-day period, while West Texas Intermediate declined 3.2%. The energy market retreat followed an announcement from G7 nations pledging to deploy up to 100 million barrels from strategic petroleum reserves. The coordinated action aims to ease pressure on international energy markets. Strategic reserves are government-held stockpiles intended for periods of market stress, and coordinated drawdowns have been used before to supplement global supply.
Individual Stock Highlights: Nike and Tesla
Nike shares retreated 3.6% following the athletic apparel giant's latest quarterly disclosure, which missed revenue expectations. Management also issued subdued projections for the coming fiscal year. The footwear company announced intentions to implement additional workforce reductions and to restructure its international operations. Nike has faced headwinds from intensifying competitive pressure and sluggish demand in the Chinese market, long one of its most important overseas regions.
Tesla stock moved sharply higher, gaining 4.7%. The electric vehicle manufacturer reported third-quarter deliveries of 486,532 units, surpassing the consensus estimate of roughly 462,000 vehicles. Delivery figures serve as the company's headline gauge of customer demand and rank among the most closely watched metrics in the auto industry.
Looking Ahead
Attention now turns to upcoming inflation indicators. The consumer price index and producer price index releases are scheduled for October 14 and October 15, respectively. The Federal Reserve's next monetary policy announcement is set for October 28. Both inflation readings will arrive ahead of the central bank's decision, rounding out a data-heavy stretch for markets.

