US SEC Approves Temporary Framework for Onchain Trading of Tokenized Securities
Key Takeaways
- •The SEC granted designated Tokenized Securities Venues conditional relief from the Exchange Act's exchange definition under Section 36(a)(1), with the exemption set to expire five years after publication.
- •Approved venues may conduct permissioned trading of tokenized U.S. stocks through automated market makers and liquidity pools, subject to limits on traded symbols and transaction volumes.
- •Venues must verify that tokenized shares carry the same economic and governance rights as equivalent National Market System stock, and must notify issuers, who may object, before listing tokens created by unaffiliated third parties.
- •The order requires smart contracts to be public and auditable on permissionless blockchains, regular publication of dollar-denominated trade data, and an immediate trading halt whenever the primary listing exchange stops the underlying stock.
- •Federal antifraud and antimanipulation provisions continue to apply under the exemption, and the SEC has requested public comment and operational evidence to shape future rules for tokenized securities.
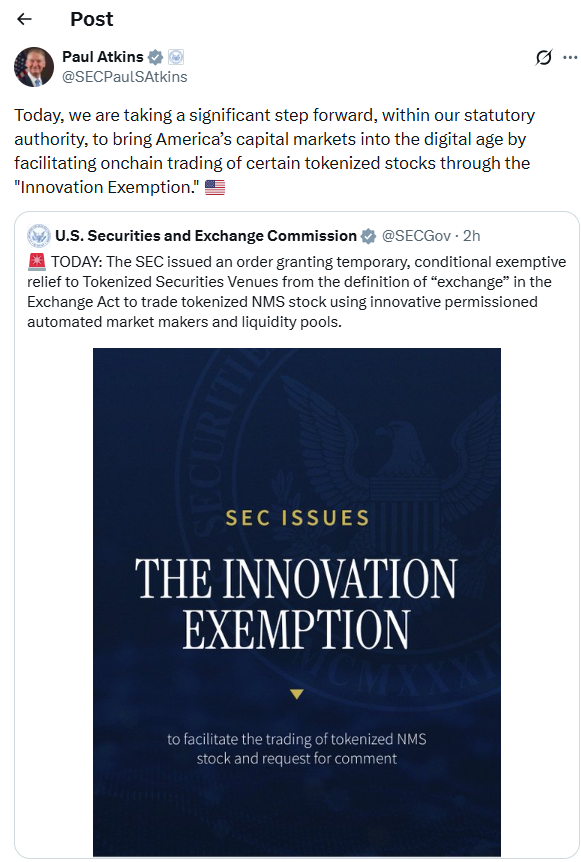
The U.S. Securities and Exchange Commission approved a temporary framework on Sept. 17 permitting limited onchain trading of tokenized U.S. stocks — blockchain-based tokens that represent shares of traditionally listed companies. Under the order, designated Tokenized Securities Venues receive conditional relief from the Exchange Act's definition of an exchange, the statutory category that generally captures platforms bringing securities buyers and sellers together, creating a regulated pathway for tokenized securities without immediately rewriting broader market rules. The approach also hands the agency live trading data ahead of any longer-term rulemaking.
Limited Onchain Stock Trading Under Supervision
According to the SEC, Tokenized Securities Venues may support permissioned trading through automated market makers and liquidity pools. In an automated market maker model, trades execute against pooled liquidity rather than through a continuous order book — a structure widely used in decentralized finance. These venues can bring buyers and sellers together through approved pools while setting access standards for participants.
The agency imposed limits on traded symbols and transaction volumes. Each venue must verify that tokenized shares carry the same rights as equivalent National Market System stock, including the economic and governance rights attached to the underlying security.
Chairman Paul Atkins said the framework would allow limited trading while the Commission considers further regulatory action.
The order also introduced issuer protections for third-party tokenization. Before listing tokens created by an unaffiliated third party, a venue must notify the underlying issuer, and that issuer must receive an opportunity to object. The requirement gives listed companies a direct role when third parties tokenize their shares.
On the technology side, smart contracts used by a venue must remain auditable and public, and the SEC required deployment on public, permissionless distributed ledgers, where contract code and transaction records can be independently inspected by anyone.
Reliance on Existing Exemptive Authority
Atkins said the Commission relied on Section 36(a)(1) of the Securities Exchange Act, which permits conditional or unconditional exemptions when they serve the public interest and investor protection.
The order created two forms of temporary relief. The first covered venues that could otherwise meet the Exchange Act's definition of an exchange. The second covered certain liquidity providers that use proprietary capital inside approved automated market maker pools; those firms received conditional relief from the statutory dealer definition.
The SEC did not suspend federal antifraud or antimanipulation rules. Atkins said those provisions continue to apply to securities activity conducted under the exemption.
Commissioner Mark Uyeda said transaction transparency formed a central condition of the order. Venues must publish U.S. dollar-denominated trade data at regular intervals, covering price, size, time, pool address, end-of-day pool size and daily volume. Uyeda said the disclosures would support monitoring and future policy evaluation.
Trading Controls for Tokenized Securities
The order also tied tokenized securities trading to traditional market stoppages. A Tokenized Securities Venue must halt trading whenever the primary listing exchange stops the underlying stock.
Venues must publish information covering their operations, trading activity and affiliate activity. The SEC additionally required books and records, technology safeguards and coordination around trading stoppages.
The framework builds on a policy path Atkins outlined earlier year. On Feb. 18, he said the agency was considering limited tokenized securities trading through automated market makers. Atkins later described the proposal as an interim framework while the Commission developed longer-term rules.
SEC officials also gathered industry comments through the agency's Crypto Task Force during 2026. That process drew competing views. Securities Industry and Financial Markets Association submissions warned that broad exemptions could fragment markets and create regulatory arbitrage, while other submissions supported limited exemptions with defined caps and disclosures. The final order adopted controls around access, volumes, issuers, data reporting and technology.
Next Regulatory Phase
According to the SEC, the exemption will expire five years after publication. The Commission also requested public comment on possible modifications and future regulatory steps. Uyeda asked commenters for data, case studies, incident analyses and operational evidence from live or test environments — material that could shape later rules governing tokenized securities and onchain market infrastructure.
The framework therefore creates a controlled market test rather than a general exemption for all tokenized equities. Its conditions tie tokenized shares to existing issuer rights, primary-market stoppages and federal securities-law protections, while giving the agency a way to collect new operational evidence.
The next formal milestone will be publication of the order in the Federal Register. Market participants can then track the comment process and any SEC guidance for prospective Tokenized Securities Venues.
This article is for informational purposes only and does not constitute financial, investment or legal advice. Regulatory exemptions and securities rules remain subject to SEC conditions, modification and future rulemaking.

