Repayment Data Could Bring More Underserved Borrowers Into the Credit System, Says Regxta CTO Moses Obika
Key Takeaways
- •Conventional credit assessment in Nigeria relies on records such as credit files, documented income and collateral that are generated mainly through formal financial channels, leaving much informal-sector activity invisible to traditional lenders.
- •Regxta's digital lending platform, which went live in October 2023, has processed more than 100,000 loans, onboarded 35,000 customers and disbursed over ₦10 billion, according to the company.
- •About 80% of Regxta's customers lack formal identification when they first approach the lender, and many also have no established credit files, payslips or conventional collateral.
- •Obika joined Regxta in August 2021 as a contract engineer and became chief technology officer in September 2022, leading development of the platform at a time when lending operations were still largely manual.
- •Repayment histories captured within one lender's platform currently inform only that lender's own decisions, and their recognition across the wider credit system remains an open question as borrower records accumulate.
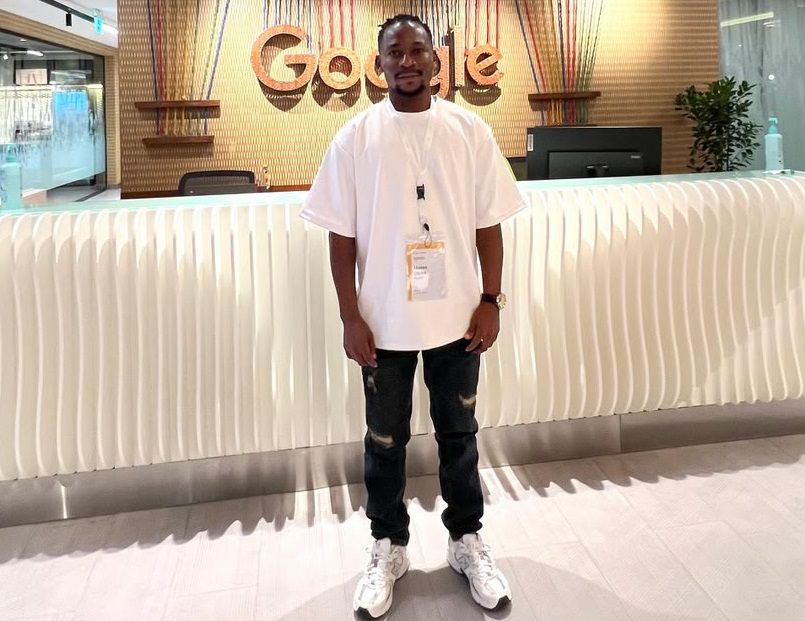
Millions of small business owners and informal-sector borrowers across Nigeria remain difficult for conventional lenders to assess, even when they have borrowed and repaid money successfully in the past. According to Moses Obika, Chief Technology Officer of lending company Regxta, the obstacle is rarely a lack of borrowing activity. More often, the transactions that would demonstrate how reliably a borrower repays take place outside the formal credit systems used by traditional financial institutions.
Without an established credit file, documented income, collateral or other conventional records, such borrowers can be hard to evaluate when they seek credit from new providers. The gap is structural: conventional credit assessment relies on records — credit files, documented income and collateral — that are generated mainly through formal financial channels, and much of the activity carried out in cash or through informal networks leaves no trace those systems can read.
Obika argues that repayment data offers an alternative route to making these borrowers visible to the credit system.
“Many underserved borrowers are not necessarily people who have never borrowed or repaid money,” Obika said. “The problem is that much of that repayment history is not visible where traditional lenders can use it. If that history is recorded properly, it could help bring more of them into the credit system.”
In his view, borrowers who begin without conventional credit records can still build useful financial histories over time, provided their loans and repayments are consistently documented. That would give lenders evidence of how a customer has handled previous credit, rather than forcing them to assess every application with little information about past borrowing behaviour.
The position is shaped by Obika’s work at Regxta, where he has developed technology for a lending operation serving customers who often arrive with limited financial documentation.
Regxta began lending in 2018 as The Bells Dynamic Option and rebranded in 2021, by which point it already had customers, field agents and an active loan book. Obika joined the company in August of that year as a contract engineer, at a time when much of the lending operation was still managed manually.
“When I started at Regxta, there was no app, no web platform, nothing,” he said. “The lending was real, the customers were real and the agents were real, but almost nothing was recorded in a way you could trust. Before we could think about credit scoring, we had to be able to see the book.”
The absence of a reliable central record became one of the main problems Obika encountered in the role. Without consistent information on loans and repayments, the company also had less usable data on how individual borrowers were performing over time.
Obika became Regxta’s chief technology officer in September 2022 and began leading the development of a digital lending platform designed to bring those records into a single system. The platform went live in October 2023.
Nearly three years later, Regxta says more than 100,000 loans have been processed through the system, with 35,000 customers onboarded and cumulative disbursements exceeding ₦10 billion.
According to the company, about 80% of its customers do not have formal identification when they first approach Regxta, while many also lack established credit files, payslips or conventional collateral. The lending process allows new customers to begin with smaller amounts and build a record through subsequent repayments, gradually producing information about how a borrower handles credit. The dynamic is self-reinforcing: with no record, a borrower is hard to assess, and hard-to-assess applicants rarely get the credit that would create one in the first place.
“Someone may start without a traditional credit file, but every successful repayment adds information about that borrower,” Obika said. “The more consistently that information is captured, the less invisible that person becomes when credit decisions have to be made.”
For Obika, the numbers recorded by Regxta over nearly three years are more than a measure of lending volume. They also represent thousands of borrowers generating repayment histories that did not previously exist in a form that could be easily assessed.
He further argues that if lenders are able to work with reliable repayment records, borrowers without conventional credit files would have another way of demonstrating how they manage credit. That could be especially important for informal-sector workers and micro-business owners, whose financial activity may not produce the documents traditionally used in lending decisions.
Instead of relying only on formal employment records, collateral or an existing credit file, lenders could also consider a documented history of borrowing and repayment when assessing customers. For borrowers who have repeatedly repaid loans successfully, Obika maintained, such records could reduce the likelihood of having to begin from zero each time they approach a new lender.
How far those records travel is the open question. Repayment histories captured inside one lender’s platform inform that lender’s own decisions; whether they come to be recognised across the wider credit system — the recognition Obika points to — is the piece of the picture still unresolved, and the development to watch as these borrower archives grow.
“If someone has consistently borrowed and repaid, that history should count for something,” he said. “Repayment data could help more underserved borrowers build a record that the wider credit system can recognise.”
Source: TechNext24

