Remita Moves Beyond Payments With Super Fintech App Launch at Nigeria Fintech Week
Key Takeaways
- •Remita launched its all-in-one mobile app during Nigeria Fintech Week, marking a strategic shift from backend payments processing into the consumer financial services space.
- •The app lets users view and manage bank accounts from multiple institutions in one place, extending account aggregation capabilities previously reserved for organisations to everyday consumers.
- •Through a partnership with PAPSS, the cross-border network developed by Afreximbank with the AfCFTA Secretariat, the app enables transfers from Nigerian bank accounts to any African bank account in local currencies.
- •The platform integrates a Loans Market for real-time loan offer comparison, investment options in stocks and government bonds, and AI-powered budget tracking, alerts, and recurring payments.
- •Remita currently processes more than 100 trillion annually, largely from corporate payments, and its app has already attracted thousands of beta users without any advertising or promotional spend.
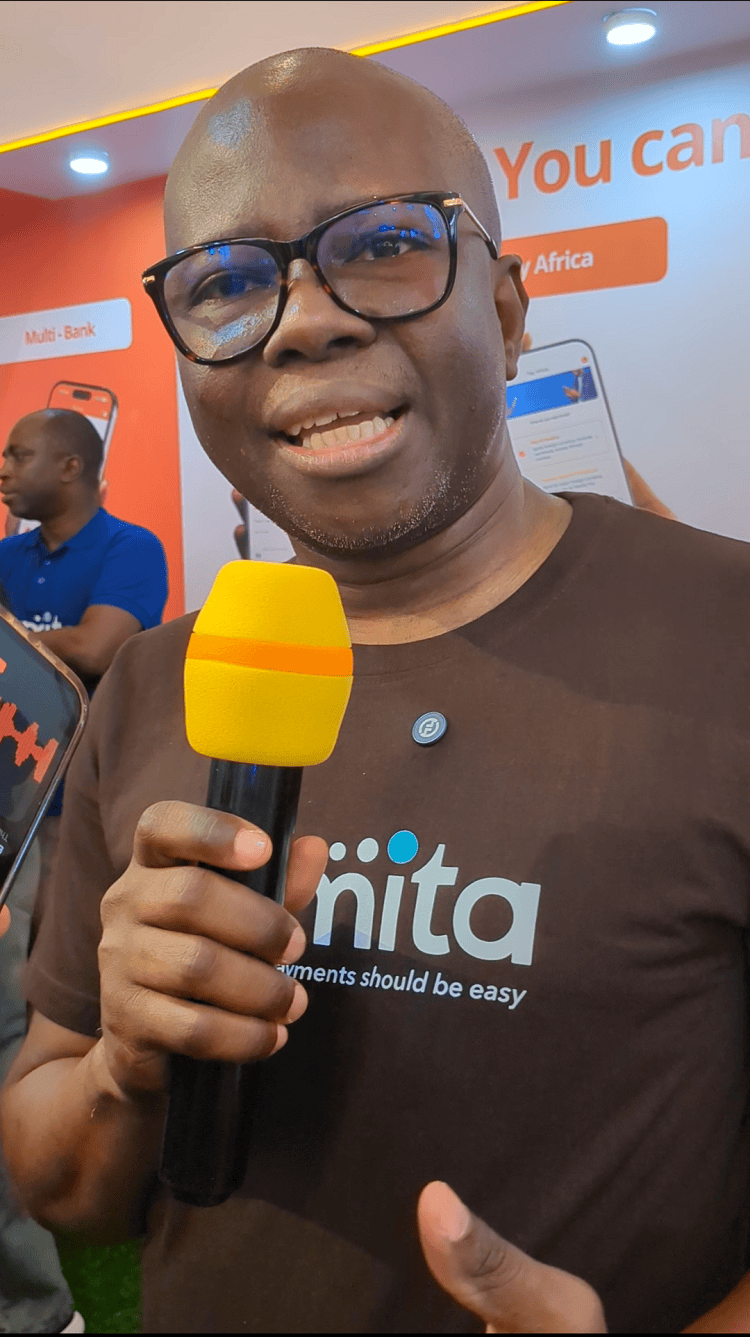
Nigerian payments platform Remita has launched an all-in-one mobile application, marking a strategic shift from pure payments processing to an all-encompassing financial solutions platform. The company announced the product during the ongoing Nigeria Fintech Week, the annual industry gathering that draws regulators, banks and startups from across the country, describing the new app as a hub for financial services.
According to Remita, the app goes well beyond payments. Users can buy stocks and shares, take loans, pay for utilities, purchase government bonds, and make transfers and transactions from Nigeria to several African countries, among a host of other functions. The platform also allows users to manage multiple financial technology apps from within it, making it a truly all-in-one offering.
Speaking at the launch, Remita Managing Director Deremi Atanda said the development showcases the company's next move and brings its solution to the world.
"The majority of people who have worked with us over the years have known us by the web expression, but today we are happy to present the Remita Mobile App, and that's the next evolution of the Remita experience. We're stepping out boldly into the consumer space, and this is well beyond payments. This is well beyond payments. This is a transformation of lifestyle. This is the expansion of access to financial services. This is ease," the MD said.
The consumer push marks a notable turn for a company whose payments infrastructure has long worked behind the scenes of Nigerian business and government, including collections under the Federal Government's Treasury Single Account. It also lands in one of Africa's most competitive consumer fintech markets, where apps such as OPay, Moniepoint and PalmPay have built large user bases around mobile payments and expanded into credit and other services.\n## A Product of Two Decades
Atanda said the app is the product of 20 years of helping everyday people make payments and learning what they want in the process. After two decades during which the company counted its own regulator among its customers, Remita has matured, built resilience, and developed the market understanding needed to serve consumers directly, he said. The result, he added, is a product that changes how people manage their finances.
"And the first bit of it is, for the first time at scale, what organisations or enterprises experience—being able to see all your bank accounts on a single app. That's the first thing. That every Nigerian, irrespective of where they bank or keep their funds, can begin to manage their funds from a single place," he said.
Account aggregation on that scale touches a longstanding policy priority in Nigeria, where the central bank has spent more than a decade promoting financial inclusion strategies to bring more adults into the formal financial system.
He noted that this capability was previously available only to organisations, until Remita brought it to the everyday person. The achievement, he said, was made possible through partnerships with financial institutions, adding that the company owes its success to the great trust and belief of the financial ecosystem.
"Irrespective of the bank where your accounts are, you'll be able to see them, monitor your balances, and transact. It represents the collaboration of the entire industry. And we say to ourselves, while other people innovate around products, we innovate the ecosystem: bring everybody together to ensure that the interests of the customers are achieved," he said.
Credit, Investments and Bills in One Place
Once users can manage their funds from a single place, they can do more than make payments. The new mobile app is set to democratise credit by giving users access to several loan platforms and enabling them to compare offers in real time through its Loans Market feature. In turn, loan platforms gain the ability to evaluate users accurately through a single platform.
The app also provides a venue for users to invest in stocks and shares, pay bills, and buy airline tickets from different accounts in one place.
"So you don't need to hop across different apps. You can use your different bank accounts to achieve different objectives from the same place. That's one of the things that we call financial management in a box," the MD said.
Pan-African Transfers via PAPSS
Beyond local payments, the Remita app enables transfers into any African bank account. The capability was built in conjunction with the Pan-African Payment and Settlement System (PAPSS), the cross-border payment network developed by Africa Export-Import Bank (Afreximbank) in collaboration with the African Continental Free Trade Area (AfCFTA) Secretariat to settle payments between African countries in local currencies. From within the app, users can securely debit any of their local bank accounts, based on their existing relationships with their banks, and transfer money to anyone in Africa.
AI-Driven Money Management
Remita is also positioning the app as a tool for the intelligent management of money. Leveraging artificial intelligence, it can track budgets and expenses, deliver signals and alerts, and provide action points after intelligently analysing trends. Users can set up recurring payments into different accounts and wallets, eliminating the need for physical reminders, while users who fall behind on those payments receive intelligent advice that compares their previous periods with the current one.
"So what we're saying is: financial services from a single place. Leveraging the power of partnership in the ecosystem, leveraging the trust that we've earned over the years, and ensuring that truly financial and economic inclusion becomes a reality, an everyday reality, for everyday Nigerians," Atanda said.
Eyes on Growth
The company currently processes in excess of 100 trillion every year, largely driven by corporate payments, according to Atanda, who said that transaction value is now set to soar as Remita enters the consumer space.
"We believe that in the next six months, we're going to see significant adoption in terms of transactions, not just instant transfer for local, but Pan-African transactions. We also see adoption that's going to drive services that people have not known before now that they have easy access to. One of those will be micro-pension. Another one will be credit for people who are already verified. A number of people are still having challenges accessing credit easily, but by virtue of access to intelligence of your data, Remita is making credit available to everyday Nigerians everywhere," he said.
The app has been in the beta stage for some time and has already accrued thousands of early adopters, despite the company running no adverts or promotions, Atanda noted. With no marketing spend behind those early numbers, how the app converts its beta base into sustained mainstream usage will offer an early measure of whether its ecosystem-first approach can carry it into everyday consumer finance.

