Up to Nine New US Lithium Mines Could Start Production by 2030
Key Takeaways
- •CRU forecasts up to nine new U.S. lithium mines could start producing by 2030, lifting annual output to 95,000 tonnes LCE, or under 4% of global supply, assuming all projects are realized.
- •Lithium Americas' Thacker Pass in Nevada is expected to be the first new mine online, targeting mechanical completion late next year and up to 40,000 tonnes of battery-quality lithium carbonate annually, financed in part by a $2.23-billion DOE loan.
- •Controlled Thermal Resources' Hell's Kitchen project in Southern California plans to co-produce lithium and geothermal power, with supply deals already signed with General Motors and Stellantis and a roughly $4.7-billion SPAC merger set to list it on Nasdaq.
- •Ioneer's Rhyolite Ridge, the continent's only known lithium-boron deposit, faces ongoing litigation over its BLM approval, with an appeals decision expected in mid-2027 that the company says will not delay construction.
- •Standard Lithium and Equinor's South West Arkansas project would be among the first large-scale commercial tests of direct lithium extraction, targeting 22,500 tonnes of lithium carbonate per year with first production planned for 2029.
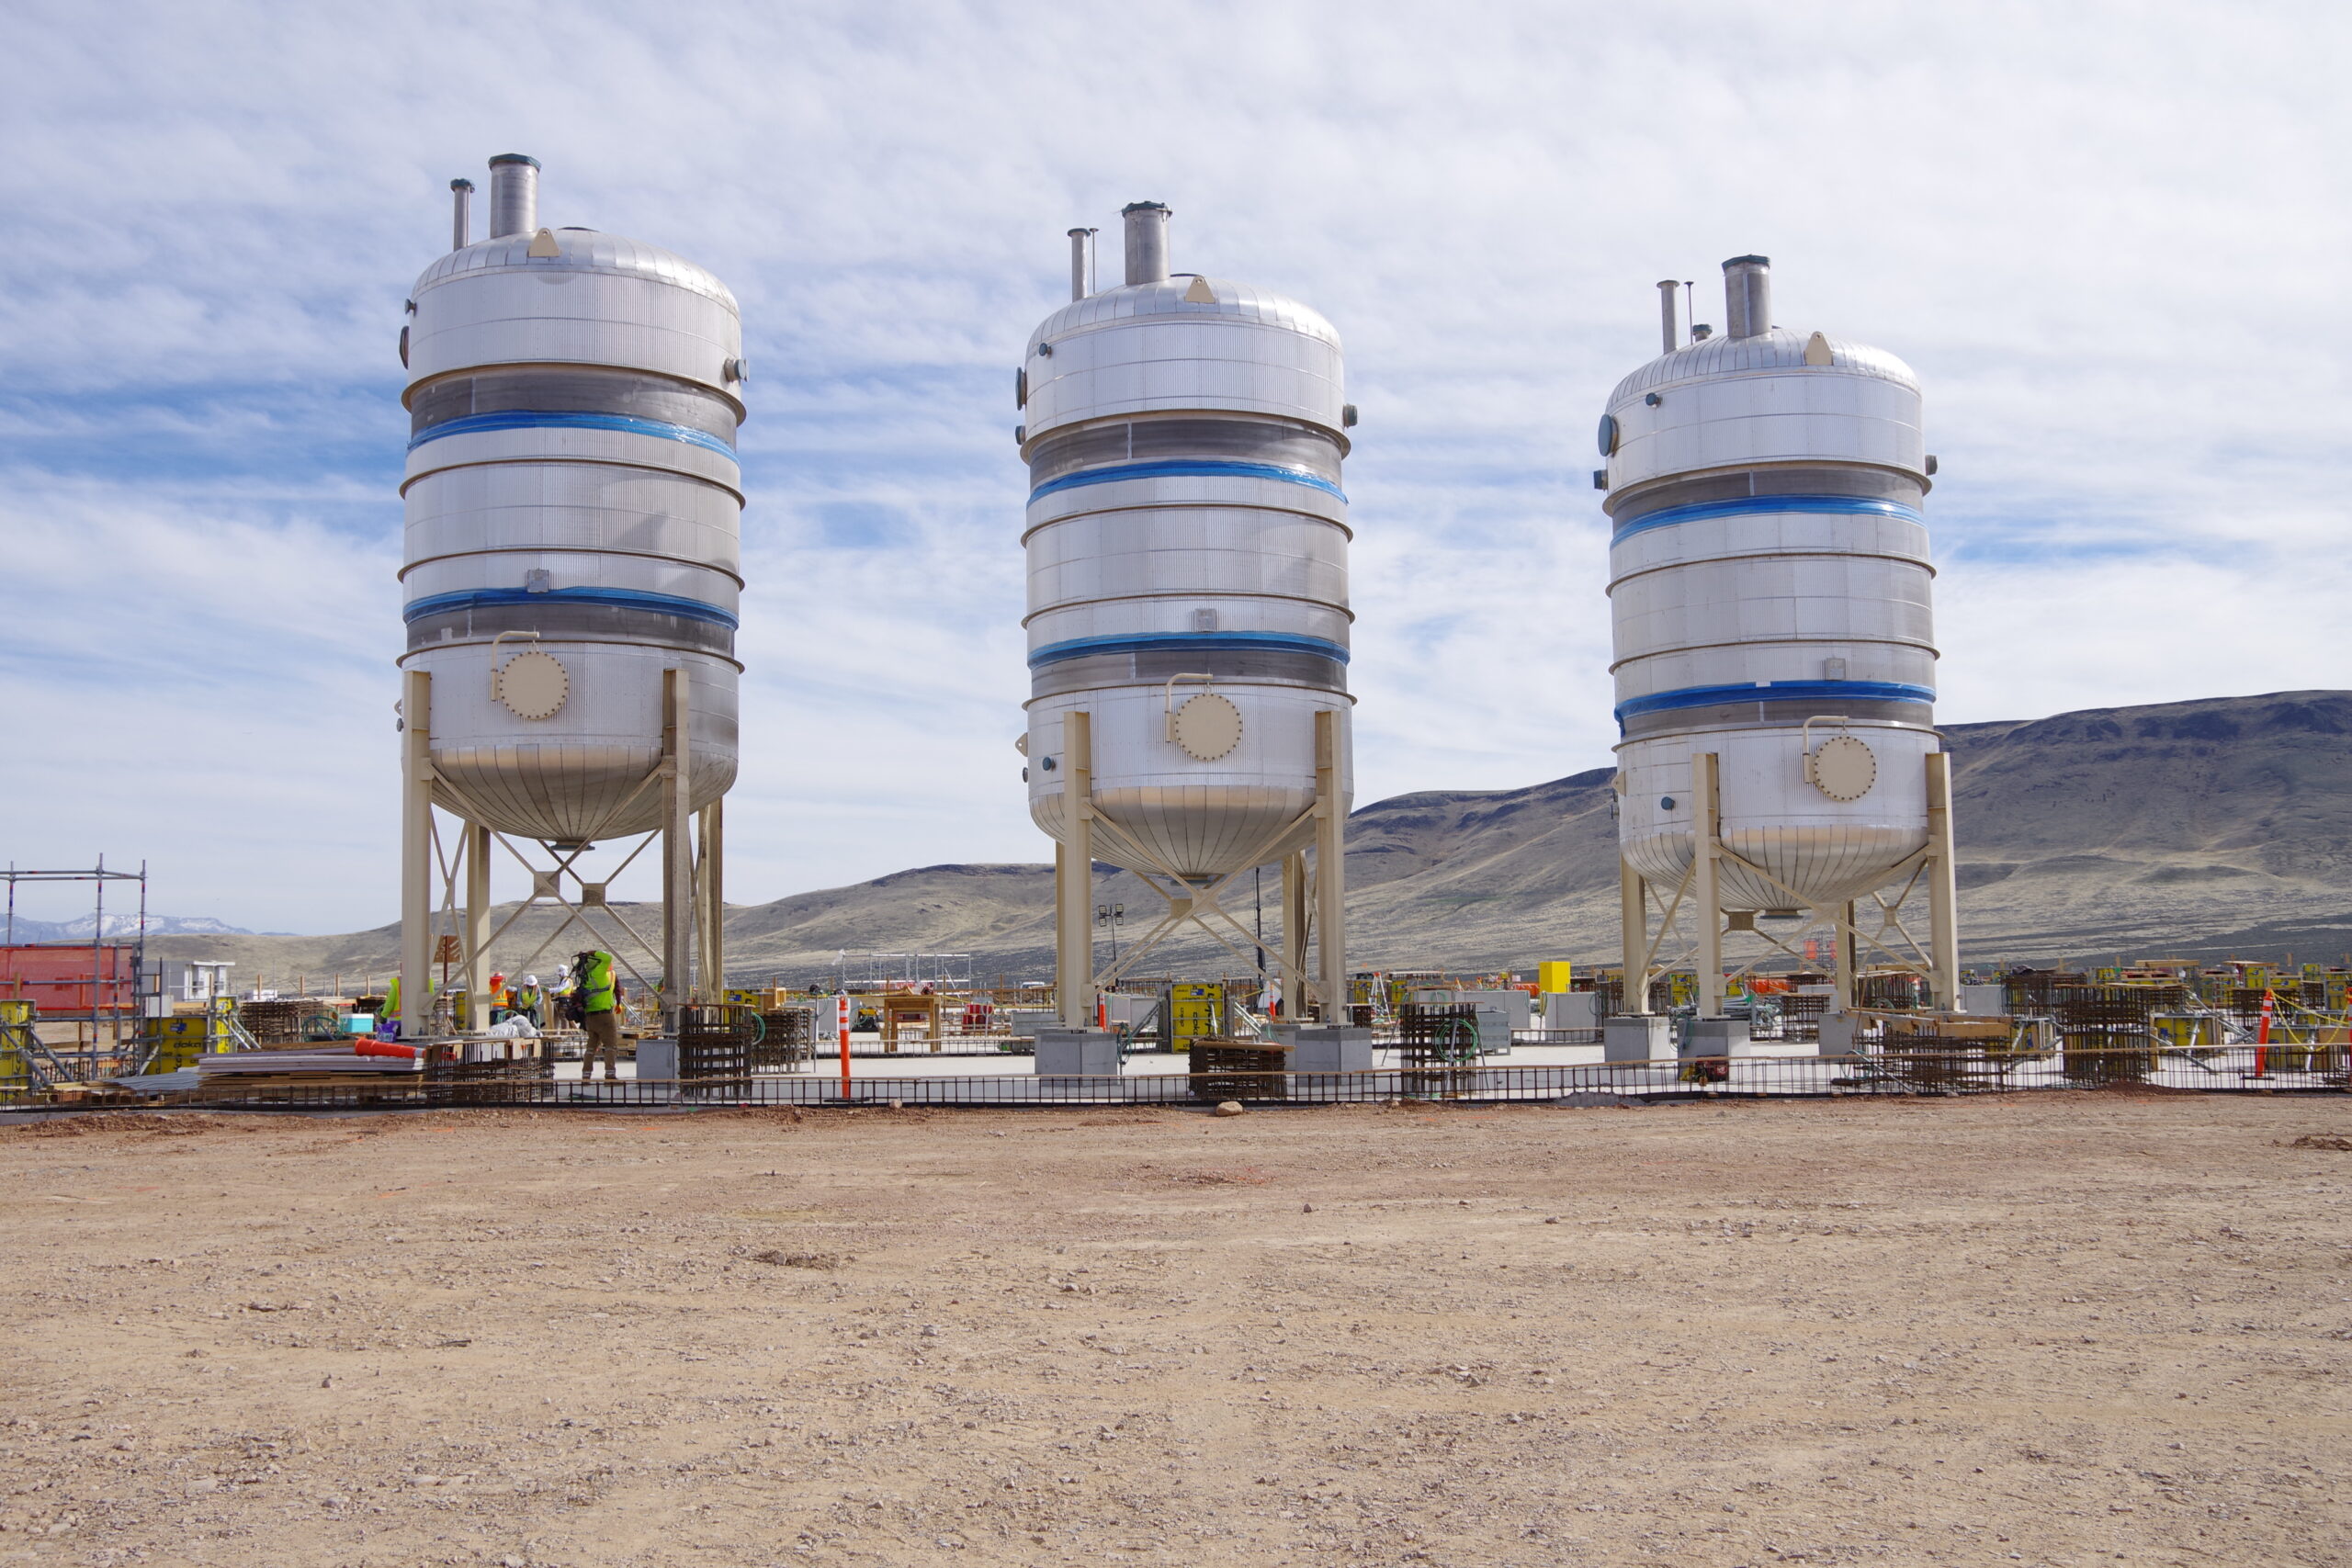
Albemarle’s (NYSE: ALB) Silver Peak mine in Nevada – currently the only active lithium operation in the United States – may soon be joined by a wave of new producers. Silver Peak, which has extracted lithium from Clayton Valley brines since the 1960s, has long symbolized how thin U.S. domestic output remains despite the metal’s central role in electric vehicle batteries and grid storage. As many as nine new lithium mines could begin producing in the U.S. between now and the end of 2030, according to London-based market research and business intelligence firm CRU.
The pipeline includes Lithium Americas’ (TSX, NYSE: LAC) Thacker Pass project in Nevada, which is positioned to become one of the Western Hemisphere’s largest lithium sources, and a Standard Lithium (TSXV: SLI; NYSE-A: SLI) project in Arkansas.
The construction boom will not be enough to make the U.S. a global lithium powerhouse, but it marks a beginning. By 2030, CRU expects up to 95,000 tonnes of lithium carbonate equivalent (LCE) to be produced annually in the U.S. – less than 4% of primary global supply – assuming all existing projects come to fruition.
On an adjusted basis that factors in the probability of delays, CRU forecasts U.S. output of 55,000 tonnes by 2030, or 2% of global supply. That compares with projected output of 5,000 tonnes this year, or 0.3% of world production. Mining projects are routinely exposed to permitting disputes, financing gaps and construction overruns, which is why risk-adjusted forecasts typically sit well below headline pipeline figures.
Global lithium supply remains highly concentrated. The top three producing countries – Australia, China and Chile – account for 77% of mined lithium output, according to a June report by investment research firm Alpine Macro. China alone holds nearly 70% of global refining capacity.
“Realistically, the United States is never going to take much market share away from somebody like China that dominates the lithium market and the whole battery value chain,” Cameron Hughes, a lithium market analyst at CRU, told The Northern Miner in an interview. “The target for the U.S. is to become more self-reliant and build out their own battery supply chain. The lithium is there, and they will produce enough lithium to service their own demand.”
Price recovery
The U.S. lithium push comes as prices for the commodity gradually recover from a two-year slump, driven by rising demand from the electric vehicle and energy storage sectors. Western governments, seeking to loosen China’s grip on electric-battery supply chains, have been providing grants and price support to encourage mine construction.
Thacker Pass is expected to be first out of the gate. Located near the Oregon border, roughly 835 km north-northwest of Las Vegas, its initial stage is still scheduled for “mechanical completion” late next year and is designed to produce up to 40,000 tonnes of battery-quality lithium carbonate annually.
Thacker Pass is on track for “energization” in this year’s fourth quarter, CEO Jonathan Evans said Aug. 13. Detailed engineering design surpassed 95% completion as of June 30, while procurement exceeded 80%, including the shipment of major plant materials and equipment, Lithium Americas said. The project has drawn strategic backing from General Motors (NYSE: GM), Orion Resource Partners and the U.S. government, reflecting the Trump administration’s drive to erode China’s dominance in critical metals.
U.S. backing
Financing for the project’s first stage includes a $2.23-billion loan from the U.S. Department of Energy. Yorkville Advisors Global – a New Jersey-based investment firm that has financed several media ventures of U.S. President Donald Trump – is another backer, having agreed in August to buy at least $150 million of Lithium Americas debentures.
The first-stage forecast for Thacker Pass remains budgeted at $1.3 billion to $1.6 billion this year, Lithium Americas said last month. Given the advanced engineering work, the company has begun preparing a definitive capital estimate, to be completed by Sept. 30.
U.S. steel tariffs and the Iran war will add $80 million to $120 million to this year’s construction expense for Thacker Pass, Lithium Americas said in May. Tariffs have not yet been included in the company’s total $2.93-billion capex estimate for the project.
Thacker Pass “is the most promising project,” CRU’s Hughes said. “It’s high capex, which is an issue that is always going to be the case in North America. But it’s moving along and it’s definitely one that we expect to come online first.”
Hell’s Kitchen
In Southern California, privately held Controlled Thermal Resources (CTR) is developing the Hell’s Kitchen project, which will convert geothermal brine into steam to generate electrical energy. Co-producing lithium from geothermal brine is attractive because the same resource yields both power and battery metal, but the approach has yet to be proven at large commercial scale.
Located about 200 km east of San Diego, Hell’s Kitchen is expected to produce 50 megawatts of power by 2028 and 25,000 tonnes of lithium annually by 2029. At full scale, it could produce up to 100,000 tonnes of lithium a year, CTR says. CTR already has lithium supply agreements with General Motors and Stellantis.
The project was placed on a fast-track permitting list by the Trump administration last year when it was designated a FAST-41 Covered Project.
In March, CTR agreed to merge with special purpose acquisition company Plum Acquisition in a deal valuing Controlled Thermal Resources at about $4.7 billion. CTR will list on Nasdaq upon closing, which is expected by year-end.
Legal proceedings
Ioneer’s (ASX: INR) proposed Rhyolite Ridge mine in Nevada is another important source of future supply, though its timeline is far less certain.
Rhyolite Ridge hosts the continent’s only known lithium-boron reserve and is one of only two such deposits globally, according to the Australian company. The boron output gives the project a second revenue stream alongside lithium. Ioneer says it will work toward a final investment decision in the next few months, after which construction would take about 36 months.
Litigation has added to the uncertainty. Three non-governmental organizations are contesting a 2024 Bureau of Land Management (BLM) decision that authorized the company’s plan of operations for Rhyolite Ridge and completed the National Environmental Policy Act process. Ioneer is actively participating in an appeal of a U.S. District Court decision upholding BLM’s approval of the project. Although the timing is outside the company’s control, it expects a decision in mid-2027. According to the company, the appeal is not expected to delay the start of construction.
Korean support
In June, Ioneer secured backing from two South Korean engineering and infrastructure groups. One of them, Korea Overseas Infrastructure & Urban Development, is considering an equity investment in the project, Ioneer said July 8.
Ioneer has been working on Rhyolite Ridge since 2016, initially bringing in Sibanye-Stillwater (JSE: SSW; NYSE: SBSW) as a partner in 2019. The South African miner walked away in February 2025 from a proposed $490-million investment for a 50% stake.
An October 2025 feasibility study for Rhyolite Ridge calculated an after-tax unlevered net present value of about $2.24 billion, an internal rate of return of 18% and a seven-year payback period. Lithium carbonate equivalent production at the site is now estimated at 24,500 tonnes for the first 25 years of operations, with boric acid output averaging 135,500 tonnes a year.
DLE prospects
Lithium mines may also emerge in the oil-rich states further east. Through their Smackover Lithium joint venture, Standard Lithium and Norwegian state oil company Equinor (NYSE: EQNR) are pursuing several projects in Arkansas and Texas.
High on the list is their South West Arkansas (SWA) project, which would be among the first large commercial applications of direct lithium extraction (DLE) in the U.S. DLE uses chemical processes to pull lithium from brines, in principle offering faster recovery and a smaller land footprint than the vast evaporation ponds used in South America – but the technology is not yet deployed at scale anywhere in the world, making the Arkansas projects a key test case.
SWA remains on track for a final investment decision and a construction start this year, CEO David Park said Aug. 10. First commercial production of battery-quality lithium carbonate is targeted for 2029.
Two key objectives remain for the Smackover venture: securing customer offtakes and completing project financing. “Advanced” discussions are under way with several prospective customers, with a goal of concluding all remaining offtake agreements by the end of the third quarter, Standard Lithium said last month.
SWA, which draws on lithium-bearing brines in Arkansas’ Smackover Formation, has a reported reserve of about 447,000 tonnes LCE. The current plan calls for 22,500 tonnes per year of battery-quality lithium carbonate.
Oil majors
Up to 19 million tonnes of lithium could be present in the brines of the Smackover Formation, according to a December 2024 report from the U.S. Geological Service. That has attracted major oil producers including Exxon Mobil, Occidental Petroleum and Chevron to the region. For companies with decades of drilling, brine-handling and subsurface expertise in the Gulf Coast basin, lithium extraction offers a way to leverage existing skills and infrastructure as the world shifts toward electrification.
Privately held T5 Smackover Partners, meanwhile, is developing an integrated geothermal energy and DLE “platform” in the region. In June, it signed a five-year offtake deal with Glencore (LSE: GLEN) under which the Swiss commodities giant will market all lithium carbonate produced at T5’s East Texas operations – about 5,000 tonnes a year. Deliveries are expected to begin once commercial production is under way, though T5 has not disclosed a start date.
“Outside of Nevada, the next most promising region is probably the southwest with Arkansas and Texas,” CRU’s Hughes said.
North Carolina revival
Other non-traditional lithium hubs could also emerge. Albemarle is seeking permitting approval to resume open-pit mining and expand the past-producing Kings Mountain mine in North Carolina, which sits on one of the country’s few known hard-rock lithium deposits.
Kings Mountain operated from 1937 until it was idled in the 1990s in favor of cheaper brine deposits in Chile. Its possible revival reflects how rising U.S. demand for domestic battery materials is making previously uneconomic deposits commercially interesting again. According to Albemarle’s website, the site is expected to supply sufficient material for 50,000 tonnes of lithium carbonate equivalent conversion capacity. The company has not published a resource estimate for the property.
