Mukuru’s ‘20-metre’ model aims to close the gap between receiving and spending money
Key Takeaways
- •Mukuru operates in more than 60 countries and serves 17.6 million customers through a physical and digital payout network across Southern and East Africa.
- •Chief Growth Officer Juan Seco joined Mukuru in 2023 after roughly a decade in the Jumia ecosystem, where his experience as CFO contributed to the development of the Jumia Pay payments platform.
- •The company recently launched a physical Visa debit card in Botswana that allows customers to spend wallet balances at retailers and withdraw cash from ATMs.
- •Mukuru has partnered with Bank Zero in South Africa to supply banking infrastructure for its account and card offering, with about 500,000 Mukuru customers being migrated onto that infrastructure as part of a combined base of more than 700,000 end customers.
- •Seco said new services should extend what customers already do, with channels such as agent networks, USSD and WhatsApp ensuring that people who transact in cash are not excluded from formal financial services.
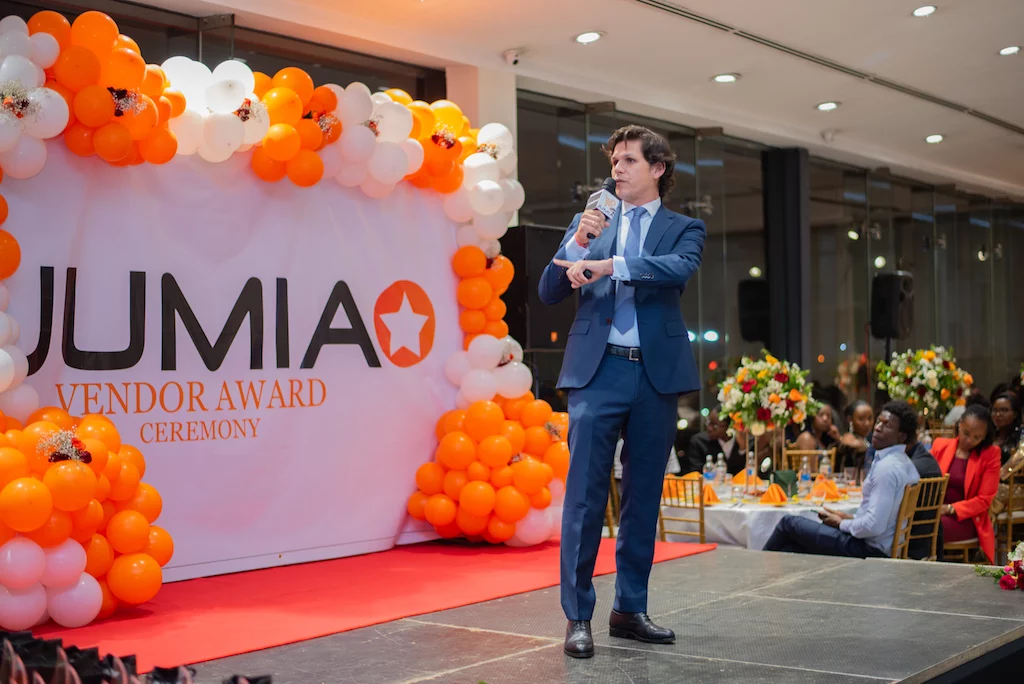
A brief 20-metre walk in Harare captures the idea behind Mukuru’s expansion from cross-border remittances into broader digital financial services. For Juan Seco, the company’s Chief Growth Officer and Managing Director for East Africa, the central challenge in African fintech is not the absence of complex financial software. It is the friction that remains after a remittance arrives.
Seco discussed that approach with PATHISANI MOYO in TechCabal’s latest edition of Coffee With….
A few days before the interview, the practical importance of that gap became clear to the writer through a conversation with his 76-year-old mother. She lives in Harare, while he lives in Johannesburg. After he transferred money to her through Mukuru, he called to confirm that it had arrived.
Her response was direct: “Mntanami (my son), don’t ever send me money through your friends again.”
The money had arrived directly on her mobile phone, allowing her to collect it in person after a walk of about 20 metres. That experience illustrates the principle behind Mukuru’s strategy: financial services should make it easier for customers to receive, store, move and spend money within the systems they already use.
The 20-metre lesson
Seco, who was born in Spain and spent years advising major financial institutions in New York before moving to Nairobi, describes South Africa-headquartered Mukuru as a “remittance-led neobank.” The term refers to digital-first financial services providers that operate without traditional branch networks. The company is best known for helping migrants send money home, but it is expanding into wallets, cards, payments and banking infrastructure.
Mukuru currently operates in more than 60 countries and serves 17.6 million customers through a physical and digital payout network across Southern and East Africa.
Seco’s route into African financial infrastructure was not linear. Born in Madrid, he spent his childhood between France and Luxembourg before studying finance and international business at McGill University in Canada. He began his career at PwC in Spain, where he audited financial institutions including American Express and Prudential. He later moved to New York to work in private-equity mergers and acquisitions.
Although the role appeared to offer a conventional corporate career, the schedule became difficult to sustain. Seco and his wife, a Colombian corporate lawyer who grew up in Kenya, had a daughter and then twins. Managing three children under three while both pursued demanding careers proved unsustainable.
“We found ourselves working crazy hours with three kids under three,” Seco said. His wife then asked him: “You’ve been unhappy for years doing work you aren’t passionate about. Why not make a change?”
Seco moved to Nairobi and accepted what he described as a significant pay cut to join Jumia, an early leader in African e-commerce. He spent roughly a decade in the Jumia ecosystem, working across technology, commerce and financial services. The move changed how he viewed the continent’s financial infrastructure.
The problem that changed Seco’s view of African fintech
As Jumia’s chief financial officer (CFO), Seco encountered a challenge that appeared operational but had broader implications. Jumia operated across several African markets, where customers often paid in cash. Cash-on-delivery was expensive and difficult to manage, while digital payments could make the business more efficient.
However, creating payment connections across those markets was not straightforward. The same technology team was repeatedly building integrations with different mobile-money systems, including M-Pesa, Kenya’s pioneering mobile-money service. Mobile-money systems let users store and transfer value from a phone, often without a traditional bank account.
Seco concluded that the problem was larger than adding individual payment integrations. Jumia needed an intermediary layer that could connect the systems. “This is broken. We need something in the middle,” was essentially his conclusion.
That thinking contributed to the development of Jumia Pay, the company’s fintech payments platform, and later led to a deeper focus on financial technology.
He saw similar limitations in corporate banking. Financial services that should have been digital still involved cumbersome processes. Corporate cards could function like prepaid instruments, and some transactions still required physical interaction with bank branches. For someone familiar with digital banking in North America, the contrast was significant.
Seco believed the opportunity was not to copy banking systems from other regions, but to build services around the realities of African consumers. At Jumia Pay, this approach expanded into lending and included working-capital products for sellers, buy-now-pay-later integrations, consumer credit in Egypt, microloans in Nigeria and other products linked to transactions already taking place on the platform.
From remittances to a “remittance-led neobank”
Seco joined Mukuru in 2023 and found an asset that many fintech companies spend years trying to establish: trust. Mukuru had spent two decades moving money across borders and had earned the confidence of millions of customers who relied on it to send funds home.
Seco, however, believed that the person receiving the money was as important as the person sending it. Customers in countries such as Zimbabwe, Malawi and Botswana were not necessarily asking for complicated new financial products. They wanted familiar services to work better.
That observation became the basis for the remittance-led neobank concept. Mukuru could use the trust developed through cross-border money transfers as the starting point for a broader financial relationship with customers.
“Remittance is the tip of the spear,” Seco said. “It is the first transaction and, in many cases, the first time we have that relationship with the customer. The opportunity is to take that trust and make the customer’s everyday financial life easier.”
In this model, remittances provide customers with a reason to use and trust the platform, while giving Mukuru an opportunity to address other everyday financial needs. Rather than the money arriving and immediately being withdrawn as cash, it can remain in a wallet. Customers can use it to pay bills, make purchases, receive salaries, send money elsewhere or eventually access other financial services.
Seco said Mukuru’s expansion should not be understood simply as an effort to sell more products to existing customers. Each new service, he said, should fit naturally into how customers already manage their money and address a need they already have.
“They should be an extension or adjacent to what the customer already does,” he said.
Making money usable after arrives
Mukuru’s products increasingly reflect that approach. In Botswana, the company recently launched a physical Visa debit card linked to its wallet. Customers can spend their wallet balance at retailers and withdraw cash from automated teller machines (ATMs).
The arrangement allows money sent by a relative overseas to become usable immediately, without requiring an additional step before it can be spent. Seco described it as a practical example of Mukuru’s effort to meet customers where they are.
“At Mukuru, we always talk about meeting our customers where they are,” he said.
That includes Mukuru’s agent network, USSD, WhatsApp and, increasingly, digital accounts. USSD, a menu-based mobile protocol that works on basic handsets without an internet connection, keeps those channels usable for customers who never install an app. The company’s partnership with Bank Zero in South Africa is part of this strategy. Mukuru has partnered with Bank Zero to provide the banking infrastructure supporting its new account and card offering.
Customers can receive salaries and other payments, make electronic payments and use cards for everyday transactions, while Mukuru retains ownership of the customer relationship and experience. The arrangement allows Mukuru to provide additional banking functionality without becoming a traditional bank.
Bank Zero supplies the underlying banking infrastructure, while Mukuru contributes its customers, distribution network, technology and financial-services experience. About 500,000 Mukuru customers are being migrated onto Bank Zero’s infrastructure. Together, they contribute to a Bank Zero customer base of more than 700,000 end customers. That migration is still under way, and together with the recently launched Botswana card it represents the nearest observable test of whether the trust built through remittances can carry into everyday banking.
The 20-metre philosophy
Seco said the importance of those figures lies not only in their scale, but also in what they enable. Customers can move from cash to digital financial services without having to begin their financial journey again, a significant consideration in markets where cash and digital money continue to coexist.
“Just because someone transacts in cash should not mean they have access to fewer financial services,” Seco told TechCabal.
For him, success is not measured solely by app downloads or digital card issuance. It also means making the transition between cash and digital value as frictionless as possible.
“Just because someone transacts in cash does not mean they should be excluded from formal financial services,” Seco said. Whether customers use USSD, WhatsApp bots, agent networks or debit cards, Mukuru’s stated aim is to provide services within their existing habits.
That brings the idea back to the 76-year-old woman in Harare. Financial inclusion is often discussed through metrics such as regulatory licences, transaction volumes and application programming interface (API) integrations. For someone collecting monthly support, the practical measure is simpler: the money arrives safely and predictably, without unnecessary travel.
Her journey was 20 metres. For Mukuru, Seco’s vision is that financial innovation should shorten the distance between receiving money and using it.
Source: TechCabal
Related coverage: South Africa’s remittance rules for migrants, Mukuru’s Botswana payments expansion, and Mukuru’s Bank Zero partnership.

