META Stock Faces Oct. 21 Earnings Test as AI Spending Guidance Reaches $145B
Key Takeaways
- •Meta will publish its third-quarter results on Oct. 21, its first report since launching the Muse AI assistant.
- •Analysts expect third-quarter revenue to rise 23% to about $63 billion, with earnings per share projected at $5.94 versus $1.05 a year earlier, driven by advertising.
- •Meta guides annual capital expenditure to $130–$145 billion after spending $50.9 billion in the second quarter, while free cash flow fell to $784 million from $8.5 billion a year earlier.
- •The Muse assistant surpassed 5 million downloads within 22 days of its debut, though momentum has begun to fade, and Meta released Muse Wonder models it says are nearing Anthropic and OpenAI performance.
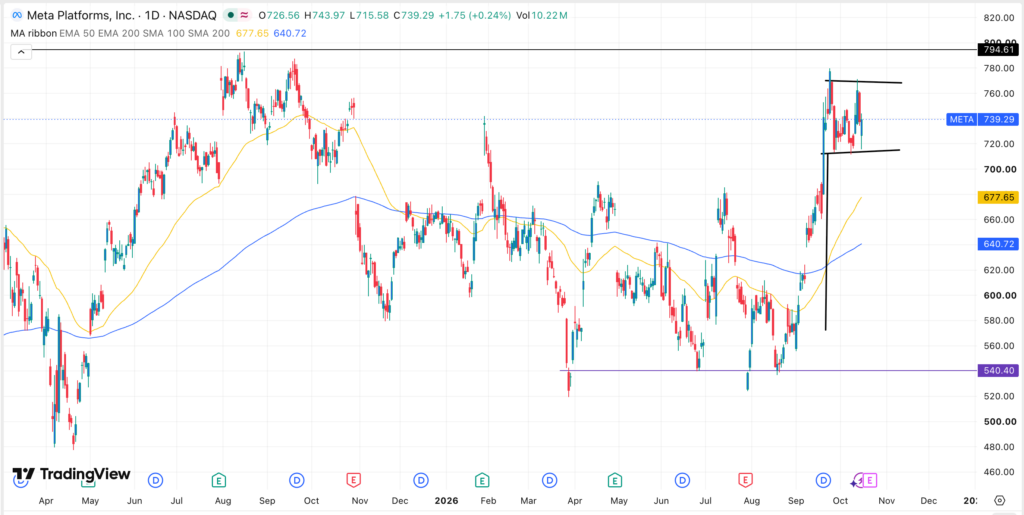
- •Technically, META has formed a bullish flag pattern after rebounding from $520 in April to $780, with a breakout potentially targeting $780 resistance and then $800.
META stock is heading into a pivotal test as Meta Platforms, the parent company of Instagram, WhatsApp, and Facebook, prepares to publish its third-quarter results on Oct. 21. The shares, which have traded in a narrow range over the past few weeks, recently retreated toward $738 as investors assessed the company's rising spending on artificial intelligence.
Attention will center on Muse, the company's AI agent, and on its capital expenditure plans. Meta has continued to expand its AI offerings, most recently with the introduction of the Muse Wonder models, but investors are questioning how quickly those investments can generate additional revenue. The company expects annual capital expenditures of $130 billion to $145 billion, and next week's earnings report will provide another opportunity to assess spending, margins, and cash generation. Any update to that guidance range will be the most direct signal of how long Meta intends to sustain its current pace of AI investment.
Analysts Expect Revenue Growth to Continue
The upcoming release will carry added weight because it is Meta's first set of financial results since the launch of Muse. According to Yahoo Finance data, analysts expect the company's revenue growth to continue into the third quarter, with the average estimate among analysts calling for a 23% jump, driven by its advertising business. If accurate, revenue would climb to $63 billion from $51.2 billion a year earlier. Advertising remains the largest contributor to Meta's revenue and has continued to grow this year.
Earnings are projected to rise sharply as well. The average estimate points to earnings per share of $5.94 in the third quarter, up from $1.05 in the same period last year — a more than fivefold increase. For the full year, analysts expect EPS to come in at $30.8, compared with $23.49 a year earlier.
Meta's most recent results showed the core business performing well. Revenue rose to $60.8 billion in the second quarter from $47.5 billion in the same period a year earlier. The challenge lies on the cost side: expenses climbed to 70% of revenue, the highest level in years, driven by research and development as the company continued work on its AI solutions.
Capital Expenditure and Muse in Focus
Capital expenditure will be among the most closely watched items in the report, as spending has been in a strong upward trend over the past few years. Meta had already spent $50.9 billion in the second quarter, up from the $30 billion it spent across all of last year, and it expects annual capital expenditures to land between $130 billion and $145 billion. At the top of that range, planned spending would be nearly five times the total for all of last year.
That surge has had a substantial impact on free cash flow — the cash a has left after funding operations and investments — which dropped by $784 million in the second quarter from $8.5 billion a year earlier. The direction of that figure will be watched alongside the capex line as a gauge of how much internal cash generation is available to fund the AI build-out.
The other top catalyst for the stock is Muse, the company's recently launched AI assistant. Muse has recorded more than 5 million downloads in the 22 days since its debut a few weeks ago, although that momentum has started to fade. Meta followed the launch with the release of its Muse Wonder and Muse Wonder Full models. In a statement, the company said the two models were created to deliver state-of-the-art performance on personal and professional agentic tasks, and that it believes they are nearing the performance of models from Anthropic and OpenAI — an unusually direct comparison with two of the industry's most prominent AI labs. The new models round out Meta's rapidly expanding AI portfolio. Whether download momentum recovers, and what management says about turning assistant usage into revenue, will be the Muse storyline to track alongside the financials.
Technical Picture
The daily chart shows META stock rebounding from a low of $520 in April this year to a high of $780 last month. The shares have since moved sideways as momentum faded, with investors booking profits following the Muse launch.
A closer look at the chart shows the stock has formed a bullish flag pattern. This pattern occurs after an asset makes a parabolic move and then consolidates, and it often precedes a strong bullish continuation. The stock has also remained above all of its moving averages. Under this setup, the shares are positioned for a likely bullish breakout toward the key resistance level of $780. A move above that level would point to further gains, potentially to $800.
This article is for informational purposes only and does not constitute financial or investment advice.

