JPMorgan Says Bitcoin ETFs Could See More Support Than Gold ETFs
Key Takeaways
- •JPMorgan analysts led by Nikolaos Panigirtzoglou believe Bitcoin could receive more support than gold if ETF investors close bearish hedges while maintaining their underlying fund exposure.
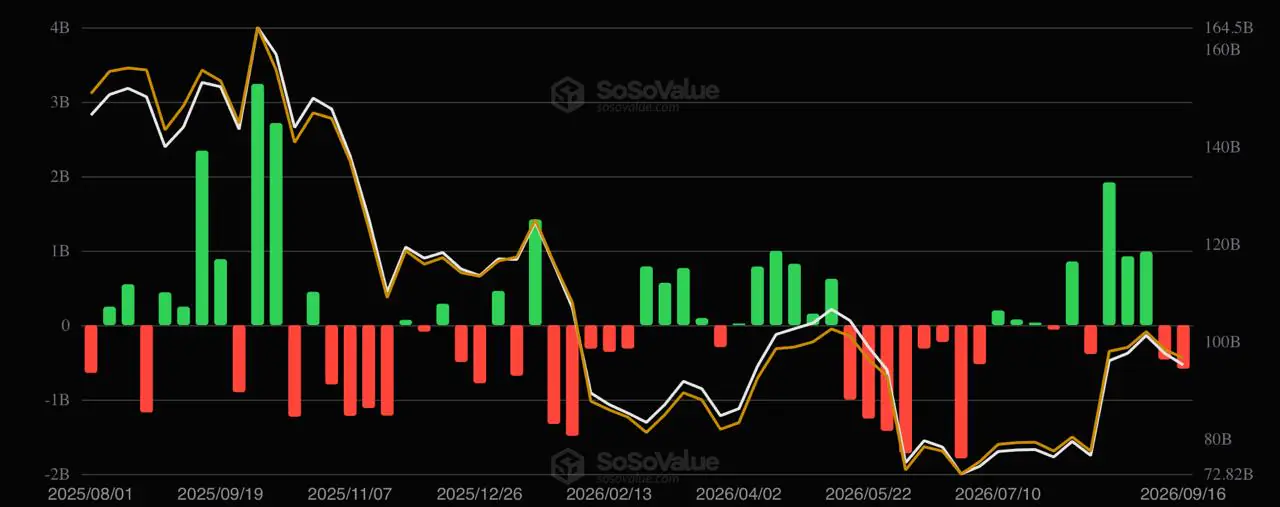
- •SoSoValue weekly data recorded approximately $4.23 billion in net inflows to spot Bitcoin ETFs between the July 31 and September 4 readings, but flows turned negative in the weeks dated September 11 and September 16.
- •A March JPMorgan comparison found that short interest in BlackRock's iShares Bitcoin Trust had risen while short interest in SPDR Gold Shares had declined, and IBIT's put-to-call open-interest ratio exceeded GLD's.
- •Closing short positions requires buying back ETF shares, which can support prices, whereas reducing put option positions does not automatically translate into equivalent ETF purchases.
- •Higher Treasury yields or a stronger dollar could offset favourable ETF positioning, since Bitcoin and gold generate no income and rising yields increase the opportunity cost of holding them.
JPMorgan says Bitcoin could receive more support than gold if exchange-traded fund (ETF) investors unwind bearish hedges while retaining their underlying fund exposure. The argument concerns positioning within the two ETF markets, rather than a forecast that Bitcoin will replace gold in investor portfolios.
Bitcoin ETF inflows returned unevenly
JPMorgan analysts led by Nikolaos Panigirtzoglou said in a note, reported by The Block, that Bitcoin and gold ETFs received inflows after the Federal Reserve’s July 28-29 meeting as the so-called “debasement trade” returned.
Bitcoin data support the idea of a broader August trend, but not an immediate or uninterrupted move. Weekly data from SoSoValue show net inflows of roughly $4.23 billion between the readings dated July 31 and September 4. That total included a $61.53 million outflow in the first reading after the Federal Reserve meeting and another $389.71 million outflow in the week dated August 14.
Demand weakened again afterward. The same series recorded net outflows of $462.73 million for the week dated September 11 and $586.27 million in the latest reading, dated September 16. The Block reported inflows for both Bitcoin and gold ETFs, while the SoSoValue data reviewed here verify the Bitcoin portion of that account.
Investors use the term “debasement trade” when they add limited-supply assets because they are concerned that inflation, rising public debt or a weaker currency could reduce cash’s purchasing power. Gold has traditionally filled that role. Bitcoin is increasingly included in the same trade, although its price continues to move more sharply. Spot ETFs give ordinary brokerage accounts a way to take that kind of exposure, since custody of the underlying Bitcoin or gold sits with the fund rather than the investor.
How unwinding a hedge could support Bitcoin
An investor can hold shares in a spot Bitcoin ETF while limiting potential losses. For example, the investor might buy put options, which increase in value if the ETF declines, or short ETF shares or related futures contracts.
Consider a simplified example in which a fund owns $10 million of Bitcoin ETF shares while shorting $2 million of the same ETF. If the fund closes the short position, it must buy those shares back. That purchase can support the ETF’s price even though the fund’s original $10 million long position has not increased.
Put options work less directly. When investors reduce their put positions, market makers may adjust their own hedges, but that does not automatically result in an equivalent purchase of Bitcoin ETF shares. A reduction in options protection should therefore not be treated as fresh ETF demand.
Why JPMorgan sees a possible Bitcoin advantage
JPMorgan’s reasoning builds on a difference it identified earlier this year. In a March comparison of IBIT and GLD positioning, the bank said short interest in BlackRock’s iShares Bitcoin Trust, known asIT, had risen while short interest in SPDR Gold Shares, or GLD, had declined. The comparison was reported in The Block’s March article. The two products also differ in maturity: US spot Bitcoin ETFs began trading in January 2024, while GLD has been listed since 2004.
The analysts also found that IBIT’s put-to-call open-interest ratio was higher than GLD’s. In practical terms, Bitcoin ETF investors appeared to be using more protection against a decline than investors in the largest gold ETF.
Those figures are not a live reading of every position in either market. They indicate why Bitcoin could have more defensive exposure to unwind if investors become less inclined to protect against the same downside risk. A larger pool of short positions and put options can produce a sharper response when those positions are closed or reduced.
Yields and the dollar remain important
ETF positioning is only one part of the market. Investors may close protective trades while still reducing exposure to risk assets if Treasury yields rise quickly or the dollar strengthens. The broader interest-rate environment therefore remains relevant. Gold and Bitcoin generate no income, so higher yields raise the opportunity cost of holding them relative to cash and short-term Treasury bills.
Bitcoin’s historical reaction to Federal Reserve rate hikes shows that the asset has behaved differently across tightening cycles. At times, investors have treated it as a scarcity hedge. At other times, it has traded more like a higher-risk asset sensitive to liquidity conditions.
Indicators that would support JPMorgan’s view
A single positive day for Bitcoin would not resolve the question. A more persuasive setup would combine steady ETF demand with evidence that investors are using fewer defensive positions.
- Spot Bitcoin ETF flows: Positive flows would indicate that underlying exposure is holding up.
- IBIT short interest: A decline could be consistent with fewer short positions.
- IBIT put-to-call open interest: A lower ratio could indicate less demand for downside insurance.
- Gold ETF flows: Continued demand would show that the move is not simply a rotation out of gold.
- Yields and the dollar: A sharp rise in either could offset favourable ETF positioning.
Short-interest data are reported with a delay and do not reveal why each position was opened. They are more informative when considered alongside ETF flows, options activity and macroeconomic conditions.
Flow totals do not show the entire picture
ETF flow totals can reflect different types of investor behaviour. One fund may be receiving new capital, while another market may simply be seeing existing holders remove protection against a decline. Both developments can initially appear constructive, but they do not convey the same information about investor commitment.
JPMorgan’s argument would gain support only if Bitcoin ETF holdings remained resilient as defensive positions declined. That combination would indicate that investors were not merely trading a short-term rebound but were more willing to retain the exposure with less insurance.
This article is provided for informational purposes only and does not constitute financial or investment advice. ETF flows, short interest and options positioning can change rapidly.

