JPMorgan Projects 10% Annual Bitcoin Returns but Keeps the Asset Out of Its Core Models
Key Takeaways
- •JPMorgan Asset Management's 2027 Long-Term Capital Market Assumptions, published on October 19, projects a 10% compound annual return for Bitcoin, the highest figure in its universe, alongside 55% annualized volatility.
- •Bitcoin has not been added to JPMorgan's main covariance matrices and instead appears in a separate abridged matrix against 12 core U.S.-d assets, a decision the firm attributes to high volatility and unstable correlations.
- •On JPMorgan's own inputs, Bitcoin's Sharpe ratio of approximately 0.32 is essentially level with U.S. large-cap stocks, while gold trails at about 0.21, indicating a risk-adjusted tie with equities.
- •A simplified two-asset optimizer using Bitcoin's 0.33 historical correlation with U.S. large caps would allocate roughly a quarter of the portfolio to Bitcoin, but JPMorgan declines to rely on that correlation, which has historically spiked during market crises such as March 2020 and the 2022 rate-hiking cycle.
- •BlackRock's December 2024 paper recommends sizing Bitcoin at 1–2% of a multi-asset portfolio, capped at 2%, citing the asset's history of 70–80% peak-to-trough sell-offs.
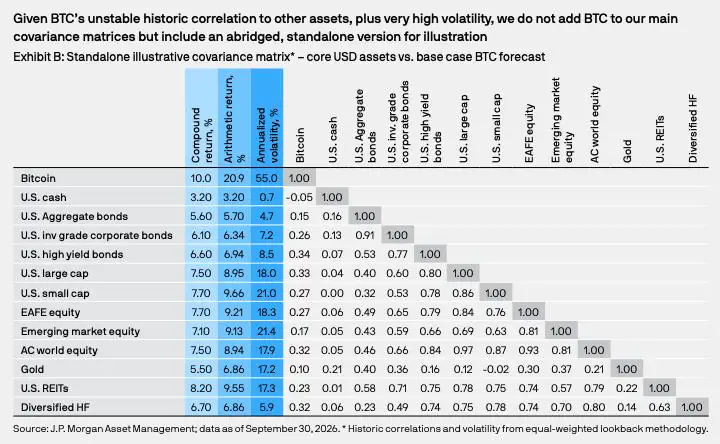
JPMorgan Asset Management's 2027 Long-Term Capital Market Assumptions hands Bitcoin the highest return projection in the firm's universe — a 10% compound annual figure — yet on a risk-adjusted basis, using the bank's own inputs, the asset pays almost exactly what U.S. stocks pay for each unit of risk. Equally telling, JPMorgan has stopped short of modeling Bitcoin alongside its other asset classes, and the reason it gives is where the real argument lies.
What JPMorgan published — and what it held back
The figures appear in the 2027 Long-Term Capital Market Assumptions, released October 19. The annual report sets return, volatility and correlation estimates for more than 200 asset classes over a 10–15 year horizon, and JPMorgan uses them to build its own strategic allocations. They are planning inputs, not calls on where prices go next.
Bitcoin receives a 10% compound annual return assumption and 55% annualized volatility — roughly triple that of U.S. large-cap stocks, which are assigned 7.5%, up 0.8 percentage points from last year's edition, with 18% volatility. Gold gets 5.5% with 17.2% volatility.
The more consequential decision is where those numbers sit. JPMorgan has not yet added Bitcoin to its main covariance matrices, the tables that tell its models how assets move together and therefore how much of each to hold. Bitcoin instead gets a separate, abridged matrix against 12 core U.S.-dollar assets, from cash and bonds to gold and hedge funds. The report blames the volatility and unstable correlations of assets like Bitcoin, and it calls the idea that currency debasement will send investors rushing into crypto "wide of the mark."
This return assumption is also separate from the Bitcoin price targets that JPMorgan's investment-bank strategists have published in past years. It is the asset-management arm's first entry for Bitcoin in the LTCMA.
Bitwise Chief Investment Officer Matt Hougan nevertheless treated the release as a milestone. In a post on X on October 20, he traced Bitcoin's path from institutional dismissal to a line in JPMorgan's return tables and called it the projected "best-performing asset of the next decade." His claim rests on the standalone Bitcoin exhibit, which sets the asset against a short list of peers rather than the full universe of more than 200. Among the figures JPMorgan highlights in its summary, the nearest to Bitcoin's 10% are large-cap private equity at 9.6% and global value-added real estate at 9.3%. Hougan's own long-run case makes room for deep sell-offs on the way up — precisely the volatility that the risk-adjusted math charges for.
Why 10% turns into 20.9%
The Sharpe ratio is the standard measure of reward per unit of risk: expected return above cash, divided by volatility. JPMorgan calculates it with arithmetic returns rather than compound ones, and for a volatile asset the gap between the two is large.
Consider an investment that gains 50% one year and loses 50% the next. Its arithmetic average return is zero, yet $100 ends at $75. The compound figure tracks what investor actually keeps; the arithmetic figure is the simple average of yearly outcomes, and big swings push it higher. At 55% volatility, Bitcoin's 10% compound assumption corresponds to a 20.9% arithmetic return. For U.S. stocks, at 18% volatility, the gap is far narrower: 7.5% becomes 8.95%.
Per unit of risk, a tie with stocks
The compound returns, arithmetic returns, volatility and the 3.2% U.S. cash return come from J.P. Morgan Asset Management's standalone Bitcoin exhibit, as of September 30, 2026. The Sharpe ratios are Coindoo calculations from those rounded inputs, using (arithmetic return − 3.2%) ÷ volatility: Bitcoin, (20.9 − 3.2) ÷ 55 = 0.322; stocks, (8.95 − 3.2) ÷ 18 = 0.319; gold, (6.86 − 3.2) ÷ 17.2 = 0.213.
On those figures, Bitcoin's return lead all but disappears. Its expected return above cash is about three times that of stocks — and so is its volatility — leaving both at 0.32. Gold trails at 0.21, so on JPMorgan's inputs Bitcoin compares better with gold than with stocks.
Sharpe treats volatility as the whole of risk, and Bitcoin's history shows the limits of that. The asset fell roughly 77% from its November 2021 peak to its November 2022 low, while the S\u0026P 500's worst decline in 2022 was about 25%. A ratio built on standard deviation does not show how deep losses go or how long recovery takes.
The case rests on the correlation JPMorgan won't trust
Equal Sharpe ratios do not make Bitcoin redundant. Two assets that pay the same per unit of risk can still improve a portfolio together if they do not move in step. JPMorgan's exhibit puts Bitcoin's historical correlation at 0.33 with U.S. large caps and 0.10 with gold.
Fed into a textbook optimizer, those inputs produce an aggressive answer. In a simplified two-asset mix of Bitcoin and U.S. large caps, a Coindoo calculation finds that the combination with the best Sharpe ratio holds about a quarter of the portfolio in Bitcoin and lifts the portfolio's ratio from 0.32 to roughly 0.39. The entire gain comes from the 0.33 correlation; the higher the correlation, the smaller the gain, and at 1.0 it vanishes.
That is the input JPMorgan declines to rely on. Bitcoin's correlation with stocks has been low on average, but it tends to jump when markets break. In March 2020, Bitcoin lost roughly half its value in two days as equities crashed, and through the 2022 rate-hiking cycle it sold off alongside technology stocks. A diversifier that falls with everything else in a crisis works in calm markets and fails when it is needed. By keeping Bitcoin out of its main matrices, JPMorgan prevents an average correlation from driving allocations in its own models.
From assumption to allocation
Practitioners land far below the optimizer's answer. BlackRock's December 2024 paper on sizing Bitcoin put a reasonable range at 1–2% of a multi-asset portfolio, a range that applies to investors who expect wider adoption and can absorb sudden plunges. BlackRock, which runs the iShares Bitcoin Trust, sized the position by how much it adds to total portfolio risk rather than by expected return, and capped it at 2%, citing the same unstable correlations. The firm's research also includes an estimate of Bitcoin's share of risk in a 60/40 portfolio.
The arithmetic of a drawdown explains the caution. BlackRock notes that Bitcoin has gone through 70–80% peak-to-trough sell-offs. A 1% position that loses 75% costs the portfolio 0.75%; a 5% position costs 3.75%. At one size the same crash is a footnote; at another, it defines the year.
JPMorgan's numbers give investors a way to test Bitcoin, not a weight to hold. The return column puts Bitcoin first. The risk-adjusted column puts it level with stocks. The correlation that would justify owning both is the input JPMorgan says it cannot yet rely on. The signal to watch is whether next year's edition moves Bitcoin into the main matrices. Until then, choosing a portfolio weight takes more than picking the highest number in the return column.
This article is provided for informational purposes only and does not constitute financial or investment advice. Model assumptions and illustrative calculations do not guarantee future performance.

