How to Choose a Crypto Market Maker in 2026: Wintermute, EchoTrade, GSR and Flowdesk Compared
Key Takeaways
- •Wintermute, founded in London in 2017 and registered with the UK FCA, saw its New York affiliate register as a broker-dealer with the SEC and FINRA in 2026, making it suited to large-cap tokens and institutional OTC needs.
- •EchoTrade, founded in 2023, focuses on first and second token launches including Binance Alpha, works on a retainer-only model with no token loans or call options, and is an official liquidity partner of MEXC.
- •GSR combines market making with venture investing and acquired Autonomous and Architech for $57 million in March 2026, holding FCA, Singapore MAS, and US MSB registrations.
- •Flowdesk, founded in Paris in 2020 and backed by investors including BlackRock, Coinbase Ventures, and Ripple, is regulated as a CASP under EU MiCA and holds a Dubai VARA licence across 150+ exchange venues and 1,000+ asset pairs.
- •Exchanges increasingly evaluate tokens after listing, with MEXC flagging any token whose average daily spread stays above 2% for 15 consecutive days under its published monitoring rules.
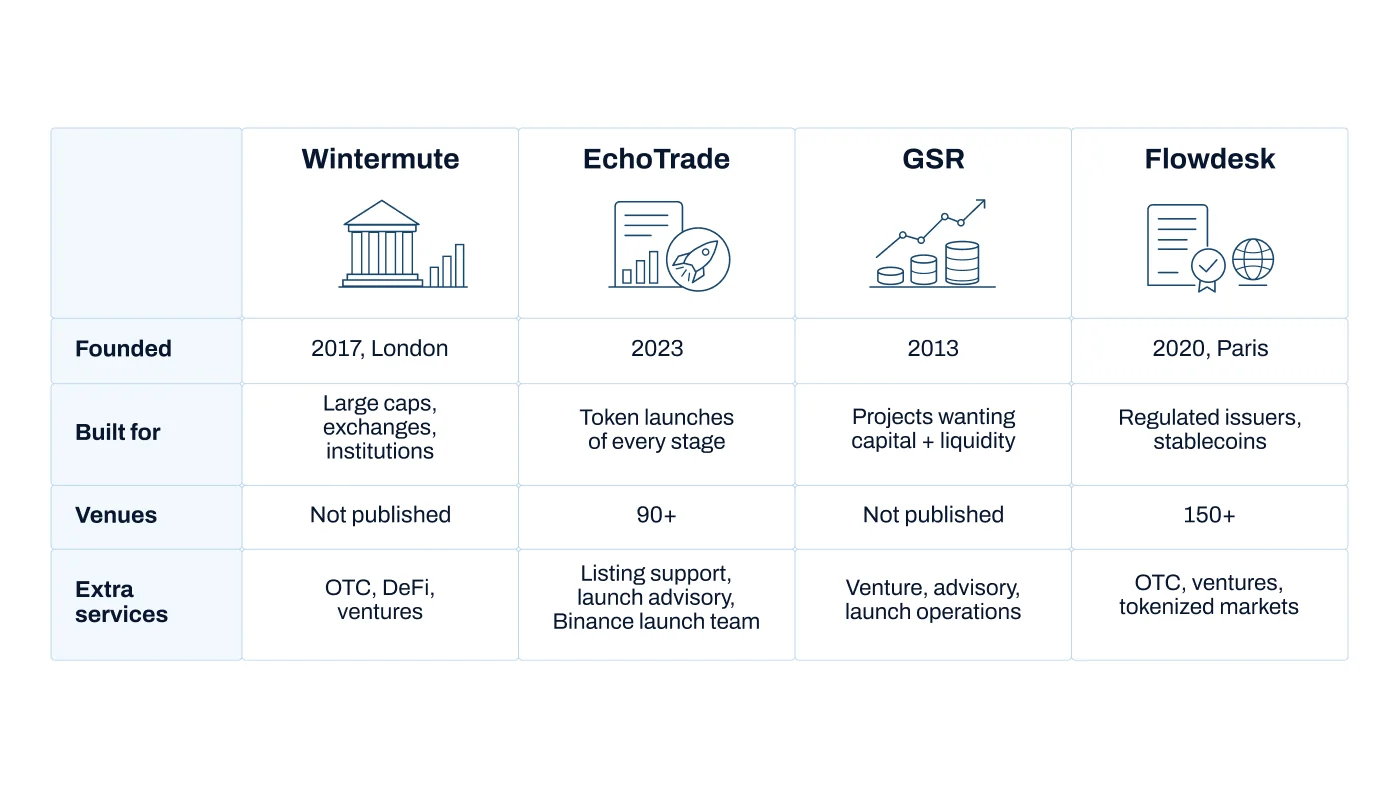
Selecting a crypto market maker in 2026 comes down to matching a firm to a project's stage, its target exchanges, an acceptable fee model and its regulatory obligations. Based on each firm's own published information as of October 2026, large-cap tokens and institutions tend to look at Wintermute; teams preparing first launches, including Binance Alpha, that want full launch advisory and access to a wide partner network look at EchoTrade; projects that want an investor alongside their liquidity look at GSR; and teams that need a MiCA or VARA licence look at Flowdesk.
The decision has become more demanding this year because exchanges now assess a token's market after listing, not only before it. MEXC, for instance, flags a token whose average daily spread remains above 2% for 15 consecutive days under its published monitoring rules. A token can clear the listing review and still receive a warning weeks later if nobody is keeping its order book tight.
All four firms examined below provide market making. Each is built for a different kind of project.
Five Questions to Answer Before Comparing Market Makers
Five answers determine which firms are worth a call:
- Stage. Pre-TGE, newly listed, or an established token with steady volume?
- Venues. Which exchanges is the project on, or applying to, and how many?
- Fee model. A fixed monthly retainer under which the project keeps its tokens, or a token loan with a call option?
- Support. Quoting only, or also help with exchange selection, listings and launch timing?
- Regulation. Do investors, banks or exchanges require a licensed counterparty in a specific jurisdiction?
How Wintermute, EchoTrade, GSR and Flowdesk Compare
The four firms differ chiefly in who they serve and what they offer around the quoting itself. The summary below draws on each firm's own published information as of October 2026.
| Firm | Founded | Regulation | Fee model | Best fit |
|---|---|---|---|---|
| Wintermute | 2017, London | UK FCA; US broker-dealer | Not publicly itemized | Large caps, institutions, OTC |
| EchoTrade | 2023 | Not stated | Retainer only | First and second launches, Binance Alpha |
| GSR | 2013 | UK FCA; Singapore MAS; US MSB | Not publicly itemized | Projects raising capital |
| Flowdesk | 2020, Paris | EU MiCA (CASP); Dubai VARA | Not publicly itemized | Teams needing a regulated counterparty |
How to Judge a Market Maker's Quality
Quality shows up in numbers measured on every exchange, not in a firm's size. Exchanges track four metrics:
- Spread as a percentage of the mid price — the figure on which exchanges set ceilings.
- Depth within 1% and 2% of mid, on both sides — how much can trade near the price before it moves.
- Uptime — the share of trading hours with quotes live inside the agreed spread, including nights and weekends.
- Cross-venue consistency — whether spread and depth hold on every exchange, not only the main one.
Before signing, a team should obtain written commitments covering the spread and depth levels per exchange, the uptime target and how it is measured, how often reports arrive, and what happens if a target is missed. The same checklist can be used after launch by comparing the agreed targets with the reported spread, depth and uptime on each venue.
Retainer or Token Loan: Which Fee Model Fits?
A retainer is a fixed monthly fee, and the project keeps custody of its tokens. A token loan means the desk borrows 0.5% to 2% of supply, usually with a call option, and earns from the spread and the option instead of a cash fee.
The difference is incentive. On a retainer, the desk is paid to hit spread and depth targets. On a loan, part of its earnings depends on where the token price goes. Neither structure is inherently wrong, but founders should know exactly which one they are signing. Of the four firms here, only EchoTrade publishes its model: retainer only, with no token loans or call options.
Wintermute: Best Fit for Large-Cap Tokens and Institutional Needs
Wintermute is an algorithmic trading firm founded in London in 2017. Per its website, it runs OTC trading across spot, options, forwards and CFDs, provides liquidity for tokens on centralized and decentralized venues, and operates a DeFi and venture arm. Its OTC desk quotes hundreds of tokens.
In 2026, its New York affiliate, Wintermute USA LLC, registered as a broker-dealer with the SEC and FINRA, and Wintermute Trading Ltd is registered with the UK FCA.
That scale is the reason to choose Wintermute — and also its limit. A new token is a small account for a desk serving exchanges and funds, so early-stage teams should ask about minimum engagement size first.
- Fee model: not publicly itemized; request written pricing
- Regulation: UK FCA; US broker-dealer
- Best fit: established and large-cap tokens, exchanges, projects with OTC or institutional buyers
- Website: wintermute.com
EchoTrade: Best Fit for First and Second Launches That Need Advisory, Partner Introductions and Listing Support
EchoTrade is a crypto market maker founded in 2023 and built around token launches. It quotes on 90+ centralized and decentralized exchanges for 100+ active projects, has supported 2,000+ token launches, and is an official liquidity partner of MEXC. Its desk of 30+ traders ranks among the strongest teams at launch-focused market makers: crypto.news reported that only around 5% of the traders who apply make it onto the desk.
What separates EchoTrade from the other three is the work around the order book. The firm can help a project build its full launch strategy: which exchanges to apply to and in what order, how the vesting and unlock calendar will meet the market, and which partners to bring in, drawing on a network of 40+ exchanges, launchpads, auditors and agencies. A dedicated team handles Binance launches, from Binance Alpha through to spot and futures listings, and EchoTrade has broken down what a Binance Alpha launch costs.
It works on a retainer only, with no token loans or call options. The project keeps its tokens in its own exchange accounts, and the desk trades through API keys with withdrawals disabled. Onboarding typically starts 4 to 6 weeks before TGE.
- Fee model: retainer only; no token loans, call options or profit share
- Services: market making, listing support, launch advisory, Binance launch team, exchange compliance support, treasury building
- Best fit: first and second launches, Binance Alpha launches, mid-caps expanding to several exchanges, tokens flagged in an exchange compliance review
- Website: echo-trade.io
GSR: Best Fit for Projects That Want an Investor and a Market Maker in One Group
GSR has traded crypto markets since 2013 and describes itself as a capital markets partner: market making and OTC alongside venture investing, advisory and asset management. In March 2026 it acquired Autonomous and Architech for $57 million, adding launch operations for tokenized organizations.
Per its site, GSR Markets UK is registered with the FCA, GSR Markets Pte. Ltd. is licensed as a Major Payment Institution by the Monetary Authority of Singapore, and GSR Digital LLC is a registered money service business in the US.
For a project raising a round, one group handling both capital and liquidity can save time. The investment terms and the market making terms should still be read together before signing either.
- Fee model: not publicly itemized; request written pricing
- Regulation: UK FCA; Singapore MAS; US MSB
- Best fit: projects raising capital or seeking strategic backing, institutional products needing a licensed counterparty
- Website: gsr.io
Flowdesk: Best Fit for Projects That Need a Regulated Counterparty
Flowdesk was founded in Paris in 2020 and calls itself a full-service trading and technology firm. Per its site, it covers 150+ exchange venues and 1,000+ asset pairs, with liquidity services for token issuers, stablecoins and exchanges. Backers listed on its site include BlackRock, Coinbase Ventures and Ripple.
Its licences set it apart. Flowdesk is regulated as a Crypto-Asset Service Provider under MiCA in the EU and holds a VARA licence in Dubai. For a project whose investors, banking partners or exchanges ask for a licensed counterparty, that can decide the choice before price does.
- Fee model: not publicly itemized; request written pricing
- Regulation: EU MiCA (CASP); Dubai VARA
- Best fit: EU and Dubai-based projects, stablecoins and tokenized assets, teams whose partners require MiCA or VARA coverage
- Website: flowdesk.co
Which Market Maker Should You Choose?
Start from the project's situation, not from a firm's size:
- Large-cap token, exchange, or institutional OTC needs: Wintermute
- Preparing a first launch, or launching through Binance Alpha: EchoTrade
- Raising capital and wanting an investor that also provides liquidity: GSR
- Needing a MiCA or VARA-licensed counterparty: Flowdesk
A project can also combine two desks — for example, an institutional desk on its largest venue and a launch-focused desk covering the rest. That works only if each desk owns a clearly defined set of exchanges, so they never quote against each other on the same book.
Frequently Asked Questions
How do you choose a crypto market maker? Start with your stage, your exchanges, the fee model you prefer and any licence your partners require. Then shortlist firms built for that profile and ask each one for spread, depth and uptime commitments per exchange, in writing.
Which market maker is best for a first token launch? A launch-focused desk that also helps with exchange selection, listing requirements and launch timing. Of the four firms reviewed here, EchoTrade is built for first and second launches, including Binance Alpha, and works on a retainer only.
Which market maker should a large-cap token use? Large-cap tokens, exchanges and projects with institutional buyers usually look at desks with OTC and institutional coverage, such as Wintermute or GSR.
What is the difference between a retainer and a token loan? On a retainer, the project pays a fixed monthly fee and keeps its tokens. On a token loan, the desk borrows 0.5% to 2% of supply, usually with a call option, and earns from the spread and the option.
When should a project hire a market maker? Before the listing. Onboarding usually takes 4 to 6 weeks before TGE, because exchanges measure spread and depth from the first trading day.
How much does a crypto market maker cost? On a retainer, typically $2,500 to $10,000 per month depending on the number of exchanges and the depth required. On a token loan, 0.5% to 2% of supply, usually with a call option instead of a cash fee.
Can a market maker guarantee a token's price? No. A legitimate market maker manages spread, depth and uptime. A firm that promises a price level or a volume figure is a red flag.
This article originally appeared on Blockonomi.

