GTBank's 737 App: Easy to Use, but Can It Beat OPay, PiggyVest, Cowrywise and Other Fintechs on Savings?
Key Takeaways
- •GTBank's 737 App targets young Nigerians by combining transfers, savings, loans, virtual cards, and everyday payments within a single application.
- •The app allows phone numbers to serve as account numbers and includes a free virtual Naira Mastercard usable on platforms like Netflix, Spotify, Amazon, and AliExpress.
- •Onboarding was quick for the reviewer, but upgrading from a Tier 1 to a Tier 3 account required a National Identification Number, financial details, and a supporting document, with approval expected within three days.
- •The app's Flex Savings option pays 15% per year, a rate that trails competitors including PiggyVest's SafeLock at up to 18.5% and Ladda's maximum of 20%.
- •The review judged the app promising for everyday banking but noted that GTBank must still demonstrate transfer reliability, withdrawal speed, and responsive customer support to win long-term savers from established platforms.
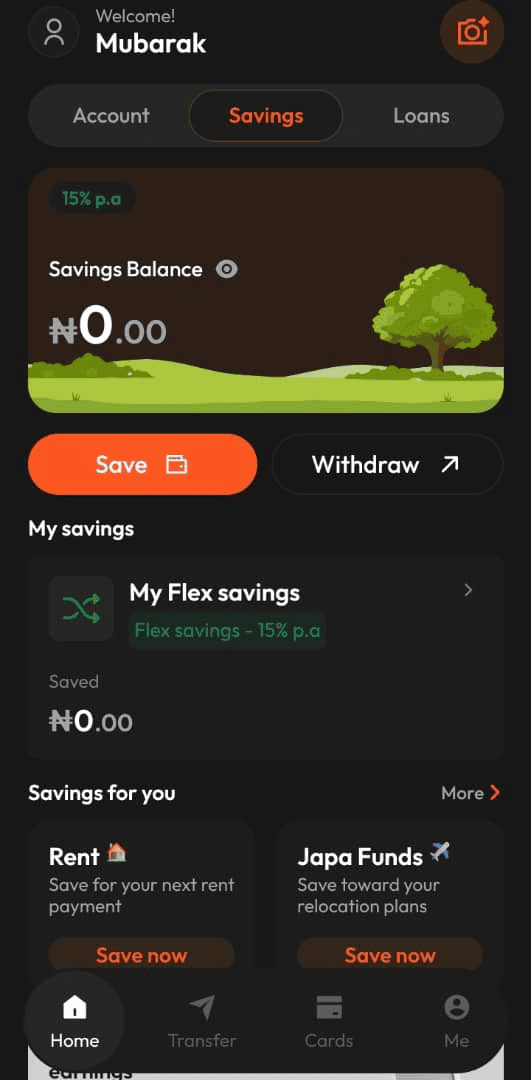
GTBank's new 737 App has made a strong first impression. Opening an account was quick and easy, with no issues during setup. The deeper question, however, is whether the app can convince young Nigerians to move their money from the savings platforms they already trust.
The launch matters because it places a traditional bank in direct competition with the savings apps that have spent years building loyalty among younger customers — and, as the comparisons below show, a smooth sign-up is only the first step in that contest.
A streamlined feature set
The app, available on Google Play, is targeted at young Nigerians and combines transfers, savings, virtual cards, loans, and everyday payments in one place.
One feature that stood out was the navigation. The app organises its main services into three sections — Account, Savings, and Loans — which makes it simple to find what you need without digging through multiple menus. Users can also deploy their phone numbers as account numbers, so there is no need to remember or share a long bank account number when someone wants to send you money. A Scan to Pay feature lets users scan account details instead of typing them out.
Additionally, the 737 App provides a free virtual Naira Mastercard for online payments, which can be used for subscriptions and purchases on sites like Netflix, Spotify, Amazon, and AliExpress. As previously reported, GTBank launched the 737 app to rival OPay, Kuda, MoMo and others with phone-number accounts, free virtual cards and instant loans. These features are especially handy for people who frequently make online payments or want to handle their everyday banking in one place.
Onboarding and tier upgrades
The onboarding experience was positive: quick and simple, without the usual back-and-forth that can make opening a bank account annoying. However, there is a difference between merely opening an account and unlocking higher account limits. I started with a Tier 1 account and tried to upgrade to Tier 3.
The app indicated that I needed to provide my National Identification Number (NIN), some financial details, and a supporting document. My Bank Verification Number (BVN) was already confirmed. One benefit of Tier 3 is unlimited deposits and an account balance once the requirements are met. I submitted the necessary documents and am now waiting for approval within the stipulated three days.
That is the part of the experience still awaiting evaluation. While opening the account was fast, how well the bank handles verification and upgrades will clearly matter to customers.
The savings question
The savings feature presents more of a challenge. My savings dashboard showed an interest rate of 15% per year for the Flex Savings option, which is a decent starting point for people who want to keep their banking and savings with the same bank. At that rate, ₦100,000 would earn about ₦1,250 in one month, bringing the total to ₦101,250, assuming the rate stays the same and before any fees. The app also lets users set savings goals such as Rent and Japa Funds, helping them manage money for specific purposes.
However, 15% is not particularly competitive compared with other savings platforms. PiggyVest offers 16% for its Piggybank, 14% for Target Savings, 12% for Flex Naira, and up to 18.5% for SafeLock, which is designed for money users are comfortable locking away. Flex Naira offers more flexibility but with lower interest, and PiggyVest notes that its rates can change with market conditions.
Ladda promotes interest rates of up to 20% on naira savings across a range of options: Emergency Savings, which lets users withdraw anytime without fees; Regular Savings for locked funds; and Presto, which pays interest upfront for locked money. The 20% figure is a maximum rate, however, and is not guaranteed for every customer or plan.
How the rivals compare
Cowrywise takes a different approach. Instead of offering a fixed rate for all plans, it bases returns on investments such as Treasury bills and government bonds. Customers see the available rate when setting up a plan, and Cowrywise promises that this rate stays fixed until the plan matures, with returns calculated daily.
Then there is OPay, which is known for everyday payments and savings. Its OWealth product provides daily interest while allowing access to funds, and the platform also features Fixed Savings, Target Savings, and SafeBox. OPay does not display a current interest rate for OWealth on its website, so users need to check what is available in the app.
Taken together, the picture is clear: GTBank is stepping into a market where many customers already have several options, some offering better rates or more specialised savings plans. For savers weighing those options, the differences go beyond headline rates: access to funds, lock-up requirements, and how each platform sets its rates all shape how well a plan fits a particular goal.
The verdict
The 737 App has a lot going for it: it is easy to use, account setup was quick, and it combines transfers, virtual cards, savings, and loans in one application.
Still, I would not move my savings into it just yet. There is a big difference between using an app to receive money and using it to save money for the long term. I am comfortable using 737 for everyday banking and receiving transfers, but I prefer to keep my savings on platforms I am already familiar with.
That does not mean anything is wrong with the 737 app. It has only recently launched, and it will take time to see how well it performs as more customers begin using it. Key open questions include how reliable transfers are during peak periods, how quickly withdrawals are processed, how savings interest is credited, and how responsive customer support is when issues arise.
For now, the 737 App shows great potential in Nigeria's digital banking scene, but it will take more than a nice design and a 15% interest rate to compete with platforms that have built trust with savers over many years. GTBank has made a solid first step. The real challenge will be earning lasting trust from customers.

