Flutterwave CEO Olugbenga Agboola Explains Why the Fintech Wants to Become a Bank
Key Takeaways
- •Flutterwave’s banking licence permits it to accept deposits and provide loans within the limits of its microfinance banking category.
- •The company aims to combine payments, deposits, credit, investments, supplier payments, and cross-border transfers on one platform.
- •Flutterwave has deployed stablecoin capabilities to support compliant transfers that may settle faster than conventional correspondent-bank payments.
- •Its lending strategy will initially focus on liquidity, secured financing, and working capital for businesses and fintech companies.
- •The company is evaluating transaction data for future credit products but says borrower assessment and underwriting must come first.
For the past decade, Flutterwave has built its business around a single core function: helping money move between people, businesses, and countries. Now, the Nigerian fintech wants to go further — helping customers store, grow, and borrow money on the same financial infrastructure that processes their payments.
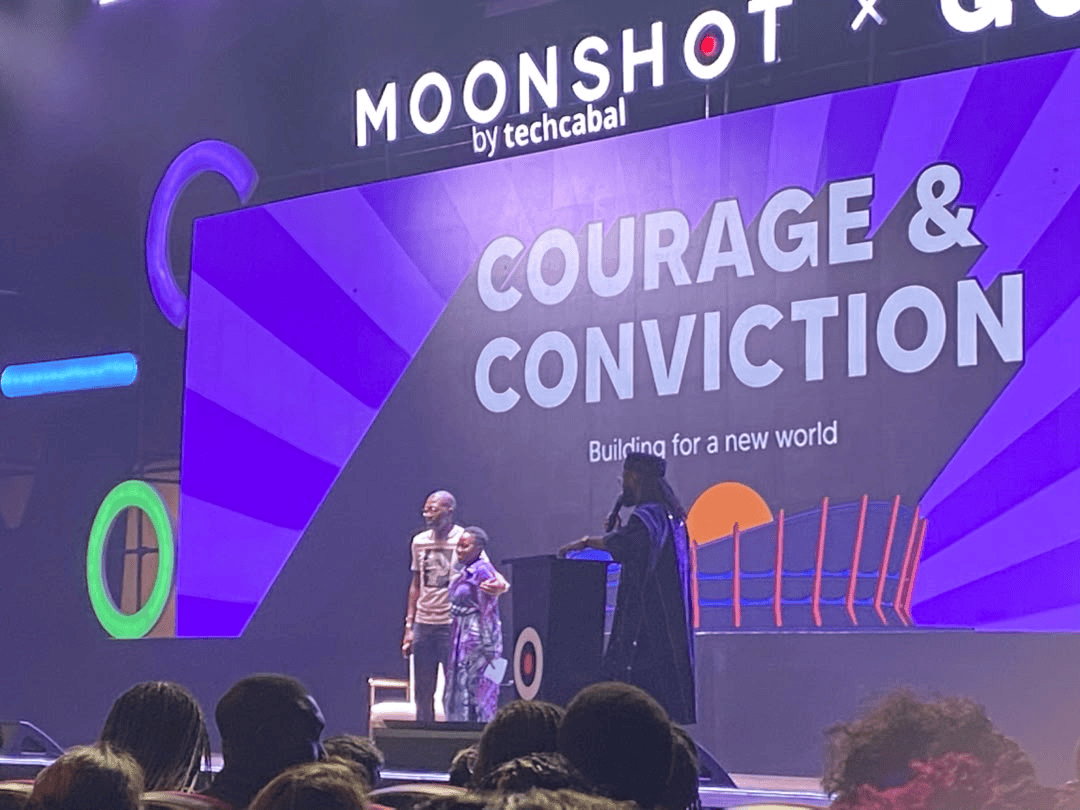
Speaking at Moonshot by TechCabal in Lagos on Wednesday, October 28, Flutterwave CEO Olugbenga "GB" Agboola said the company's next phase centers on building a broader financial operating system, extending beyond payment processing into banking, lending, investments, and stablecoin-powered cross-border transfers.
"If you can trust us with your payment, it's a much easier sell to actually keep the money for you," Agboola said.
The shift follows two milestones: Flutterwave's acquisition of open-banking startup Mono in January — a company whose technology connects to customers' financial accounts across different institutions — and its acquisition of a national microfinance banking licence in April. The licence allows the company to accept deposits and lend directly within the regulatory limits of its banking category, a position payment processors that rely on partner banks do not have.
At the conference, held at the National Theatre under the theme "Courage and Conviction: Building for a New World," Agboola stressed that the decision was not simply about becoming a bank. It was about gaining greater control over the infrastructure that customers depend on.
Why Flutterwave Wants a Bank
Flutterwave has spent the past ten years connecting payment systems across Africa. Countries such as Nigeria, Ghana, and Kenya have each developed their own payment infrastructure, but moving money across their borders remains complicated. Agboola said Flutterwave had made significant progress linking these systems, yet moving money alone is not enough. Businesses also need places to keep their earnings, access to credit, the ability to pay suppliers, and options to invest.
The company's reliance on partner banks has also created a reliability problem. When a partner bank experiences downtime or schedules maintenance, services that depend on it can be disrupted.
"You cannot provide an accurate payment experience if you don't control the entire stack, or at least a big piece of the stack," he said.
The banking licence gives Flutterwave greater control over parts of that infrastructure, but it does not mean the company will stop working with banks. Agboola said Flutterwave would continue partnering with financial institutions while deciding which parts of its operations it needs to control directly. The aim is to reduce disruptions and give customers more financial services through one platform.
Agboola illustrated the plan with the example of a fashion business operating in Accra or Nairobi. Beyond accepting payments, such a business needs to pay suppliers, manage its cash, finance operations, and move money across borders — activities Flutterwave wants to bring together on a single platform. Businesses can already use the company's services to make certain international payments, access investment products, and, through its banking operations, reach deposits and lending.
Agboola also pointed to payments to Chinese suppliers as an example of how the company wants to simplify trade. Nigerian businesses can pay eligible Chinese suppliers in naira through Flutterwave's infrastructure, reducing the need to source dollars for those transactions.
The company is also betting on stablecoins — digital tokens designed to maintain a relatively stable value, often by tracking a currency such as the US dollar. Because these tokens move on shared digital rails, transfers can settle without passing through the chains of correspondent banks that slow conventional cross-border payments. Agboola said Flutterwave had deployed stablecoin capabilities across its business and consumer products to support compliant transfers, describing the technology as an important option for businesses whose suppliers want faster settlement than traditional international bank transfers can offer.
Rather than expand indiscriminately, Flutterwave plans to develop services around specific industries and their needs. Agboola named fashion and e-commerce as areas where the company could build more specialized financial products, including escrow services that help protect buyers and sellers during transactions. Ghana and Kenya, he added, are also important markets for its plans to expand beyond payments into banking-related services.
Lending Brings Opportunity and Risk
Moving into lending could create another source of revenue for Flutterwave, but Agboola described a gradual approach rather than an immediate push into broad consumer lending.
The company currently provides liquidity to payment businesses, including by advancing funds so payouts can happen before the money arrives from another party. It also plans to provide secured and working-capital financing to businesses and fintech companies. Over time, it wants to explore lending to businesses in sectors such as manufacturing, where short-term financing could help companies meet operational needs.
Flutterwave is also studying transaction data to identify unmet demand for credit. Agboola cited payment data in which around 30% of attempted transactions in a particular set of observations failed because of insufficient funds. He said the pattern could point to demand for consumer lending, provided the company can assess borrowers' ability to repay.
However, he acknowledged that turning these observations into lending products requires careful underwriting and risk assessment. A failed payment does not automatically make someone a suitable borrower. How the company builds that underwriting capability will determine whether its lending ambitions stay anchored in business credit or eventually extend to consumers.
Trust Will Matter as Much as Technology
The expansion also raises questions about how Flutterwave will protect customers' money as it takes on more banking responsibilities. Asked what the company had changed internally to earn trust with customer deposits, Agboola initially answered, "Nothing." He then explained that Flutterwave had built its infrastructure around trust from the beginning, but was now working harder to communicate what it does, how its systems operate, and how it supports businesses.
That explanation places greater weight on transparency as Flutterwave moves into services where customers entrust it with money they may need to access at any time.
The company's next phase will depend not only on whether it can connect payments, deposits, credit, and international transfers, but also on whether it can manage the risks that come with those services. Flutterwave wants to become more than the company that moves money between businesses and their customers. Its ambition is to become part of the infrastructure those businesses rely on to operate and grow — and whether it can deliver that promise consistently will determine how far its banking strategy takes it.

