FinCEN Links $12.7 Billion in Suspicious Activity to Crypto Scams Run From Southeast Asian Compounds
Key Takeaways
- •FinCEN tied roughly $12.7 billion in suspicious activity to crypto investment scams based on 33,904 suspicious activity reports filed between September 2023 and December 2025.
- •Scam proceeds were typically converted into stablecoins, almost exclusively USDT, and moved through DeFi protocols or exchanges outside the United States, complicating enforcement.
- •Banks flagged $6.4 billion while crypto money services businesses filed the most reports, showing the detection burden spans both traditional and crypto-native firms.
- •FinCEN found older adults were not disproportionately victimized, with elder exploitation appearing in about 25% of reports versus a 24.4% population share for those 60 and over.
- •FinCEN's Rapid Response Program has interdicted $1.8 billion and recovered just over $1 billion for 5,790 American victims since 2015.
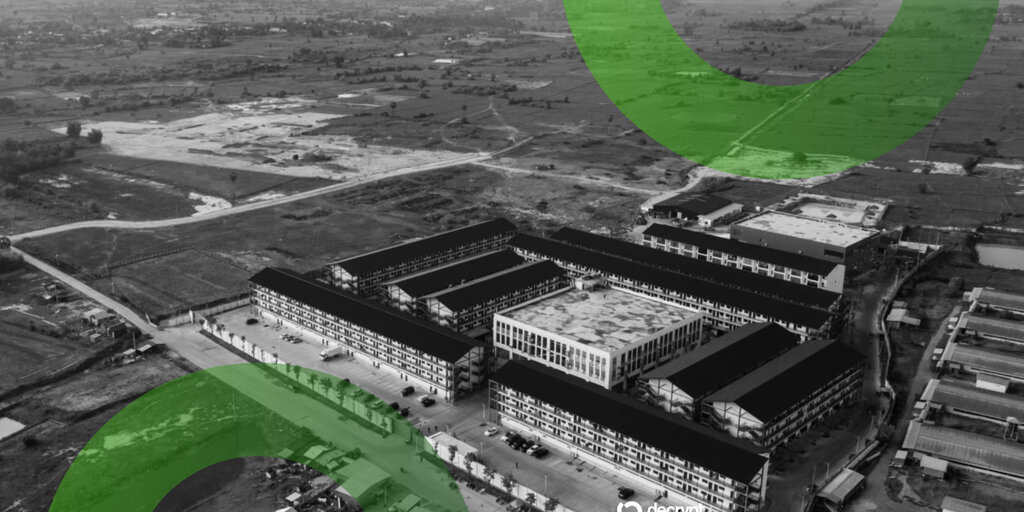
The Treasury Department's Financial Crimes Enforcement Network (FinCEN) has tied roughly $12.7 billion in suspicious financial activity to crypto investment scams run out of Southeast Asian compounds, according to an analysis and an alert published Thursday.
FinCEN analyzed 33,904 suspicious activity reports filed between September 2023 and December 2025. Roughly 1,300 institutions filed the reports, with crypto money services businesses filing most frequently and banks reporting the largest sums.
Today, @FinCENnews published an alert and an analysis of financial activity tied to suspected digital asset investment scams. These scams are sophisticated fraud operations that manipulate victims, who are often American. pic.twitter.com/ZdKRusnL8p — Financial Crimes Enforcement Network (FinCEN) (@FinCENnews) September 3, 2026
Breakdown of filings
Of the 33,904 reports, money services businesses—mostly crypto firms—filed 55% and flagged $5.5 billion. Banks filed 41% and flagged $6.4 billion, while securities firms accounted for the remainder at $784.5 million.
Filings grew by an average of 10.9% per month, and reported sums grew by 18%—from 590 reports worth $485.7 million in October 2023 to 2,482 reports worth $833.5 million in December 2025. FinCEN cautioned that the climb may partly reflect wider adoption of the search term from its 2023 alert, and that the totals can double-count transfers, attempted payments, and filer errors. The scale of the filings also reflects how the detection burden now spans both traditional banks and crypto-native firms, each catching different stages of the same money flow.
How the proceeds moved
Scammers used at least 22 different digital assets, most often Ethereum, USDT, and USDC, and rarely invented their own tokens. Whatever the victim originally bought, blockchain analysis showed proceeds were nearly always swapped into stablecoins—almost exclusively USDT—then pushed through DeFi protocols or exchanges outside the United States. The reliance on established tokens rather than custom tokens, combined with the swap into USDT, reflects how dollar-pegged stablecoins have become a preferred medium for moving illicit proceeds across borders because they can be transferred quickly through non-U.S. venues with few checkpoints. Scammers also reused collection addresses across multiple victims simultaneously, which is how some firms spotted the pattern.
Older Americans not disproportionately victimized
Elder exploitation appeared in about 25% of reports, compared with the 24.4% share of the population aged 60 and over, leading FinCEN to conclude that older adults are neither disproportionately victimized nor disproportionately robbed—a finding that contradicts a common assumption about these scams. The FBI counted $4.8 billion in fraud losses among Americans over 60 in 2024, a figure senators cited in introducing the GUARD Act, a bill to fund blockchain tracing for local police.
Victims spanned all 50 states. Losses were financed through retirement accounts, home equity lines, second mortgages, and personal loans. One woman sent nearly $640,000 from her retirement fund; another lost more than $1 million over six months. The pattern of draining home equity and retirement savings is what makes these schemes, often called "pig butchering" scams because perpetrators fatten victims with attention and small fake gains before taking everything, particularly damaging: the money frequently cannot be re-earned through future work.
FinCEN devoted a section of the report to self-harm, noting that victims are sometimes at risk after discovering the fraud, and pointed them to the 988 Suicide and Crisis Lifeline.
The compounds and enforcement
The compounds sit mostly in Cambodia, Laos, and Burma, staffed by people the United Nations numbers in the hundreds of thousands—many trafficked there through fake job adverts. Interpol has warned that the model is spreading well beyond Southeast Asia, and U.S. authorities have seized more than $25 million tied to such schemes this year.
Since 2015, FinCEN's Rapid Response Program has interdicted $1.8 billion and recovered just over $1 billion for 5,790 American victims. The recovery figures underline the central enforcement challenge the report documents: proceeds move into stablecoins and through non-U.S. venues within hours, so freezing funds depends on institutions flagging and reporting suspicious transfers quickly, while congressional proposals like the GUARD Act aim to extend tracing capability to local police departments.

