Why the Federal Reserve Often Reads Inflation Slowly, Late, and Wrong
Key Takeaways
- •The July Consumer Price Index rose 3.4% year-over-year, down slightly from June's 3.5% but still above the Federal Reserve's 2% target.
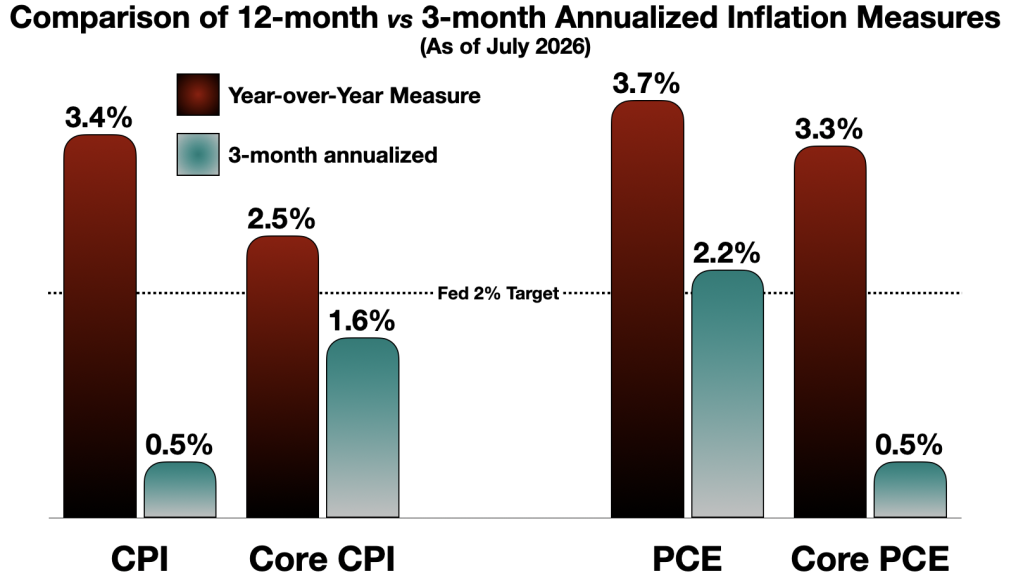
- •The annualized 3-month CPI since May was just 0.49%, and the Cleveland Fed's annualized-quarterly inflation nowcast stands at 1.05%, far below the headline reading.
- •Three regional Fed presidents—Beth Hammack, Neel Kashkari, and Lorie Logan—dissented at the latest FOMC meeting and voted to raise interest rates immediately.
- •Economists including Paul Krugman, Jason Furman, and former Fed officials have endorsed shorter 3-to-6-month averaging windows as better indicators of the inflation trend than 12-month changes.
- •Fed Chair Kevin Warsh has launched task forces to reevaluate how the Fed understands inflation drivers and improve the timeliness of economic signals informing policy decisions.
The Federal Reserve is frequently described as steering the economy by looking in the rearview mirror — setting monetary policy based on where the economy has been rather than where it stands today or where it is heading. The explanation is straightforward: the Fed leans heavily on indicators that summarize the previous 12 months, and those measures can be sluggish in capturing a sharp shift in the current pace of inflation. The stakes are high, because the Fed's dual mandate from Congress charges it with both price stability and maximum employment — and misreading inflation can damage either goal.
Take the Consumer Price Index, which aims to measure "inflation" by tracking changes in consumer prices. The CPI is compiled monthly by the Bureau of Labor Statistics from prices of a basket of goods and services, and its headline reading is almost always quoted as a 12-month change. The July CPI came in at 3.4%, slightly below June's 3.5% — and still far above the Fed's 2% policy target.
On its face, inflation still looks like a serious problem, and some Fed officials are deeply worried. At the latest Federal Open Market Committee meeting, the presidents of three regional Fed branches voted to raise interest rates immediately. Dissents of this kind are relatively rare at the FOMC, where the twelve voting members — the Board of Governors, the New York Fed president, and a rotating set of regional bank presidents — usually align with the chair. "The longer that high inflation persists, the more challenging and costly it can be to bring it back down," said Beth Hammack of Cleveland, adding that "pricing pressures are broadening rather than fading, and consumers are expressing despair over persistently higher prices."
Neel Kashkari of Minneapolis flagged the risk that "high inflation could become entrenched" and projected multiple rate hikes. Lorie Logan of Dallas was similarly pessimistic.
Most Fed-watchers, meanwhile, expect significant monetary tightening in the near future. Chairman Warsh has spoken of the need to continue the fight against high inflation and pledged that the Fed will deliver on its 2% target.
The trouble lies in the numbers themselves. The 3.4% CPI reading is a year-over-year (YoY) comparison, showing how much prices have risen over the past 12 months. The trend of the past three months tells a different, more current story: the 3-month average of the CPI since May, annualized, is just 0.49%.
The Producer Price Index, also released this week, was up 4.7% — alarming on the surface, since producer prices feed into consumer prices, though the pass-through varies widely across industries. Yet on a monthly basis the PPI has been falling rapidly since April and was negative in both June and July, putting the 3-month annualized rate at 1.6%.
Inflation expectations have also cooled markedly since May, according to both market measures — the 5-year Breakeven Inflation forecast, derived from the yield gap between a 5-year nominal Treasury and a comparable 5-year TIPS — and the Cleveland Fed's 1-year inflation expectation model. Both put expected inflation around 2.3%, well below the headline CPI. Expectations matter to policymakers because sustained above-target expectations can feed into wage- and price-setting, making inflation harder to dislodge.
The direction of prices may be reversing faster than the YoY CPI can detect. On some short-run measures, "inflation" may already be at the 2% target. Traders appear to agree: the S&P 500 set a new all-time record the day after the CPI release, with "tame inflation data" cited as the driver. Market consensus on a possible September rate increase flipped from 80% "Yes" last month to roughly 67% "No" today. Even The Wall Street Journal heralded the return of "disinflation."
Is this mere statistical sleight of hand? Not at all. The argument that an annualized quarterly (AQ) measure of inflation may be superior to a YoY measure is a mainstream position among economists and policymakers. Nobel laureate Paul Krugman has endorsed it: "In the past, it may have made sense to look at changes over the last year, but in an economy going through as much turmoil as we've seen recently, that's just too long a lag…many economists are now focusing on either three- or six-month changes."
Jason Furman, who chaired Obama's Council of Economic Advisors, tweeted along the same lines: "headline CPI, the 12-month change in the overall index gets the most public attention…but to understand the inflation trend, it's better to focus on a shorter window (3-6 months)." Former Fed Chair Jerome Powell and Vice-Chair Lael Brainard frequently cited inflation figures based on shorter averaging periods. The Cleveland Fed publishes an "inflation nowcast" whose AQ version of the CPI currently stands at 1.05%. Many academically oriented economists at respected think tanks, or working within the Fed itself, have backed shorter averaging windows. As one Fed economist has written: "Inflation is typically measured over the past year, inherently a slow-moving and backward-looking measure." (Cleveland Fed statement on the July FOMC meeting vote)
The damage to monetary policy is twofold. Heavy reliance on backward-looking data obscures the most consequential moments in the trend — the moments when things change. And that backward focus worsens the lag in responding to those changes, with potentially serious macroeconomic consequences.
Consider the inflation spike of 2021–2023. A charitable reading holds that although the Fed responded slowly, the rate increases that began in mid-2022 succeeded in bringing inflation down.
The same underlying data, viewed through the annualized 3-month lens, paints a very different picture. The inflation trend changed abruptly and dramatically in mid-2022, falling from 10.1% to 1.9% in a single quarter — a structural change. The three-month annualized series reveals a sharp shift in the short-run pace of inflation, while the standard CPI first understated and then overstated that shorter-run measure.
Monetary policy, in other words, appears to have been slow, late, and therefore perhaps unsound. By the time the Fed began raising rates, the inflationary surge was already ending. The fire was out by the time the firemen got the hydrant open.
One might counter that the tightening of late 2022 and early 2023 prevented a resurgence of inflation. But that is not how monetary policy works. Milton Friedman famously observed that monetary policy operates with a "long and variable lag" between cause and effect, action and outcome — loosely estimated at 9 to 24 months. Fed officials have widely endorsed this view in recent years. In his November 2022 press conference, Chairman Powell used the word "lags" 17 times, signaling that in his mind the policy outcome was still in abeyance.
And how much in abeyance? The inflation episode began in 2020/2021. Rate hikes started in March 2022. The policy may only have begun affecting the economy in late 2023 or 2024 — years after the inflationary crisis began, and after inflation had already declined materially.
There is a present danger in failing to learn this lesson. The Fed is in a tightening mood today, yet the annualized 3-month CPI suggests the short-run pace of inflation may be lower than the year-over-year headline indicates. Setting the CPI aside, is there really a case right now for "restraining economic activity," as President Hammack proposes? The labor market has weakened: the July jobs number was negative, and June and May were revised downward by almost half. Labor force participation is declining. Mortgage rates are rising and home sales are falling. Bond yields sit at multi-decade highs. Retail spending dropped in July for the first time in nine months. Wars are raging, geopolitical uncertainty is elevated, and tariffs are in disarray, creating uncertainty for businesses and consumers. Economic uncertainty indices are at levels last seen during the pandemic. Is this really the moment to hit the brakes in response to an obviously flawed inflation measure?
The Fed's latent hawkishness may once again be out of step with the real economy. Kevin Warsh has launched a series of task forces intended, among other things, to reevaluate "how the Federal Reserve understands and responds to the drivers of inflation" and to "improve the quality and timeliness of real economic signals that inform the Federal Reserve's policy judgments." The initiative is laudable and may address the problems outlined here, but it will take time. In the interim, the Fed should pay closer attention to short-term trends suggesting that a significant "inflation regime change" may already be underway.
"Yesterday's news has a way of getting mistaken for what is happening right now," Warsh said in his keynote speech at the Jackson Hole Economic Symposium. "The challenge is to know the difference. In other words, we must interrogate reality to make sure we are not setting forward-looking policy based on stale or inaccurate data."
The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.
This story was originally featured on Fortune.com

