Extended Exchange Review 2026: Broad Perpetual Markets Meet Documentation Gaps
Key Takeaways
- •Extended Exchange provides more than 300 crypto and real-world-asset perpetual and spot markets, with leverage up to 100x and USDC as the base collateral.
- •Its published fee schedule charges 0% maker and 0.025% taker on standard markets, or 0.010% taker on RWA markets, the lowest starting taker cost among the compared venues including Hyperliquid.
- •Current architecture documentation states that funds are self-custodied in smart contracts settling on Arc, Circle's EVM-compatible Layer 1, while API documentation fetched October 29 still refers to Starknet endpoints, Stark keys, and Stark signatures.
- •Deposits and withdrawals support USDC, cirBTC, and ETH across EVM chains including Ethereum, Arbitrum, Base, and Arc, with timing and limits dependent on Rhino.fi bridge liquidity.
- •Advanced order tools such as Chase, Conditional, Scaled, and TWAP are available, but the Chase strategy runs in the browser tab and stops repricing if the tab is closed, creating operational risk.
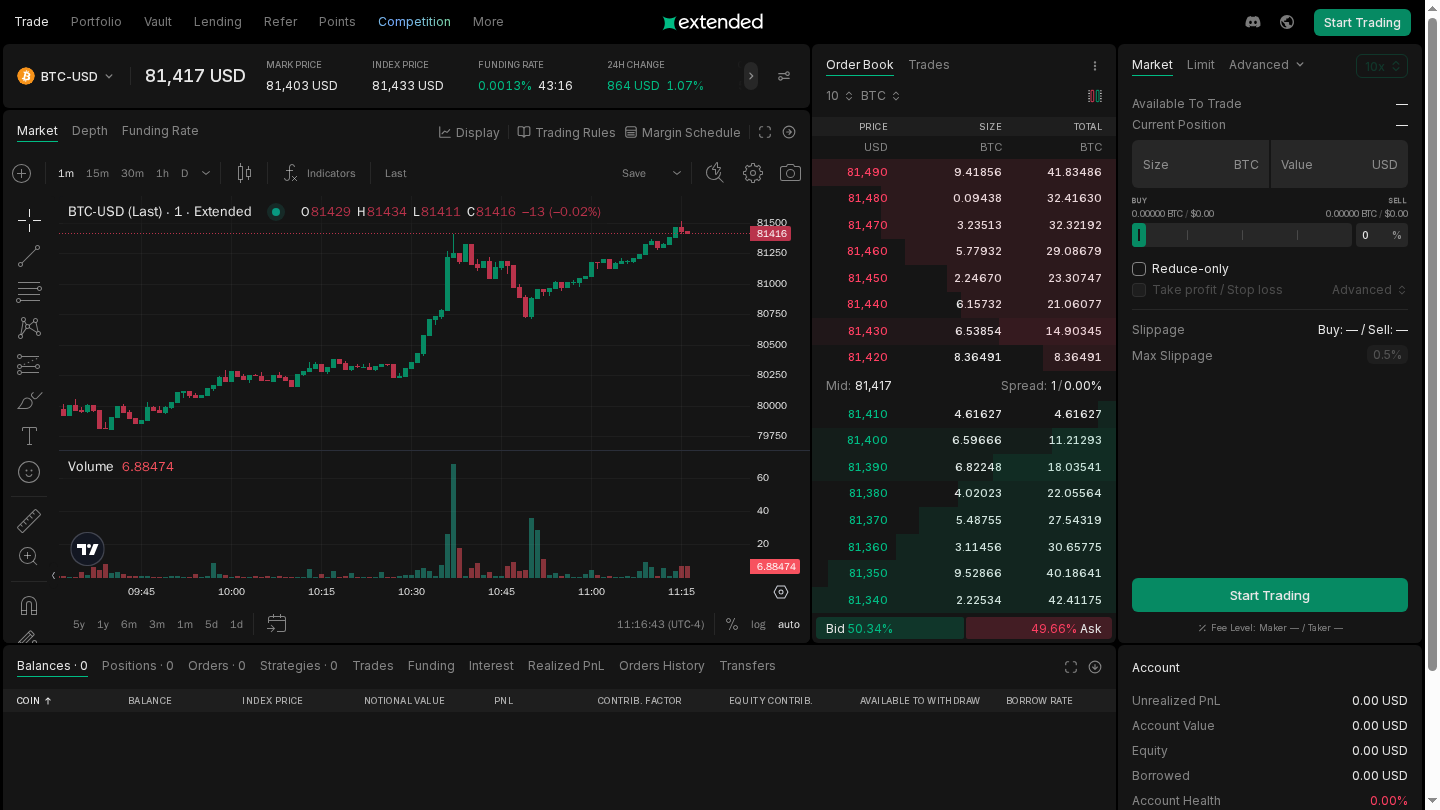
Extended Exchange is a perpetual decentralized exchange (DEX) that combines crypto markets with real-world-asset (RWA) references, including equities, indices, commodities, and foreign exchange. Its public terminal provides an unusually large amount of information before wallet connection. During a walkthrough, it was possible to inspect a BTC-USD chart, live market depth, funding, open interest, market categories, order controls, and account tabs without signing in.
This assessment combines a live public-interface walkthrough recorded on October 29, 2026, with current Extended documentation. The review covers the market selector, charting, order book, order-entry panel, margin information, and account layouts visible before login.
Quick verdict
Extended’s strongest features are its broad market selector, clean chart, order-book and order-ticket layout, flat published fees, and the quantity of data available before login. The terminal appears designed for active derivatives traders rather than beginners. Crypto, RWA, perpetual, and spot filters are available in one selector, while funding, open interest, volume, leverage labels, RFQ markers, and account-risk fields are positioned close to the order ticket.
The interface is approachable, but the product is not simple. The largest issue identified in this review is a documentation transition: the current architecture material describes settlement on Arc, while API documentation fetched on October 29 still refers to Starknet endpoints, Stark keys, Stark signatures, and Starknet settlement.
What is Extended Exchange?
Extended describes itself as a perpetual DEX built by an ex-Revolut team. Its overview says the platform covers more than 300 crypto and RWA markets, supports leverage of up to 100x, uses USDC as base collateral, and is building toward unified margin across perpetuals, spot, lending, and additional products.
Perpetual futures are derivative contracts without an expiry date: positions can remain open indefinitely, while periodic funding payments between long and short holders work to keep the contract price aligned with the underlying index. That mechanism explains why a funding rate appears on every market row and in the account tabs described below, and why the cost of holding a perp position accrues over time rather than only at entry and exit.
The team page identifies a founding group with backgrounds in Revolut crypto, exchange architecture, engineering, and McKinsey. This provides useful information about the operators, but it remains a self-description rather than an independent assessment of governance or operational controls.
The current technical architecture page says user funds are self-custodied in smart contracts and that transactions settle on Arc, Circle’s EVM-compatible Layer 1—Circle being the same company that issues USDC, Extended’s base collateral. It also says collateral-changing events—including trades, funding payments, transfers, liquidations, and ADLs (auto-deleveraging, the forced partial closing of profitable positions used to absorb a liquidation the order book cannot)—trigger on-chain health checks. These controls reduce reliance on a centralized custodian, but code, oracle, bridge, signing, market, and governance risks remain.
Hands-on public trading experience
First load: useful data behind a promotional modal
The first full screen loaded a dark BTC-USD terminal, but a “Final Arc Competition” modal covered the center of the interface. It advertised a pool of $250,000 USDC and 750,000 Xpoints for a competition running from October 6 to November 3. The modal included clear Learn more and Got it actions, although it delayed access to the chart and order book.
After the modal was dismissed, the workspace was easy to parse. The header displayed BTC-USD, mark and index prices, funding, 24-hour change, open interest, and volume. Open interest—the total notional value of contracts currently open, distinct from traded volume—indicates how much capital is committed to a market rather than how quickly it is turning over. The chart offered Market, Depth, and Funding Rate views, along with links to Trading Rules and Margin Schedule. The center-right panel showed live asks and bids, while the order ticket on the right offered Market, Limit, and Advanced tabs.
The observed BTC mark price moved around $81,100, and the order book and statistics refreshed during the capture. Those figures demonstrate a functioning public display but are volatile observations, not current quotes for readers.
Market selector: the strongest part of the public experience
Selecting BTC-USD opened a large market selector with three layers of filtering:
- Product type: All, Perpetual, Spot
- Asset class: All, Crypto, RWA
- Subcategories: All, Pinned, AI, Commodity, DeFi, ETF/Index, Equity, FX, Infra, L1, L2, Meme, Pre-market, Stable
Each row combined the last price, 24-hour change, funding rate, open interest, volume, and a maximum-leverage label. The capture included BTC and ETH at 50x, XAU at 25x, WTI at 10x, NDX at 20x, SPX at 25x, and JP225 at 25x with an RFQ tag. The RFQ label denotes request-for-quote execution, in which a price is generated on demand rather than streamed continuously on an order book.
This mix makes comparisons fast, but the leverage label represents a ceiling or market parameter rather than a recommended setting. The selector’s main trade-off is density. More than 30 instruments were available to scroll through during the walkthrough, and similarly named order-book and RFQ markets can behave differently. The application improves discovery but does not eliminate the need to read each market’s trading rules, oracle source, trading session, and liquidation parameters.
Order ticket and account area
Before login, the ticket exposed Size in BTC, Value in USD, a percentage slider, Reduce-only, slippage information, and Buy and Sell sides. The Take profit / Stop loss row was visible but inactive in the default state. Available to Trade, Current Position, and maker/taker fee level displayed dashes until an account was connected.
The bottom account area included Balances, Positions, Orders, Strategies, Trades, Funding, Interest, Realized PnL, Orders History, and Transfers. Personal values remained zero or blank before login, while the surrounding layout showed how balances and position history are organized.
Trading rules and margin schedule
The BTC-USD Trading Rules panel displayed a 0.0001 BTC minimum trade size, a 0.00001 BTC size increment, a $1 minimum price change, a $3 million maximum market order, a $15 million maximum limit order, a $60 million maximum position value, and 200 open orders. These values can vary by market, making the panel more useful than assuming a single global rule set.
The Margin Schedule made the relationship between position size and leverage explicit. The captured first tier covered positions from $0 to $4 million with 50x maximum leverage, 2% initial margin, and 1% maintenance margin. Higher brackets progressively reduced leverage and increased both margin requirements.
Order types: more capable than the default ticket suggests
The public ticket groups orders under Market, Limit, and Advanced, but the official order-type documentation describes a wider toolkit. Opening the Advanced menu exposed Chase, Conditional, Scaled, and TWAP directly in the ticket. This makes the documented toolkit easier to reach than the three top-level tabs initially suggest.
One implementation detail is important: the documented Chase strategy runs in the browser tab. Closing or refreshing the tab, switching accounts, or disconnecting the wallet pauses repricing while leaving the last limit order live until it fills, is canceled, or expires under the documented conditions. This creates a meaningful operational risk for anyone treating Chase as a server-side autonomous strategy.
Visible controls do not guarantee execution. Market orders can cross available depth, limits can remain open, conditional orders can activate during fast market conditions, and take-profit or stop-loss settings cannot eliminate gap or liquidity risk. Extended provides several ways to express an order, not several ways to guarantee an exit.
Fees and a like-for-like comparison
Extended’s published fee page uses a simple flat schedule. For a $10,000 notional position opened and closed entirely as a standard taker, listed trading fees would be about $5.00. The same round trip on an RWA market would be about $2.00. These illustrations exclude spread, slippage, funding, bridge costs, borrowing, price movement, and any future fee changes.
For a dated comparison, Hyperliquid’s official fee page listed a Tier 0 perpetual base rate of 0.045% taker and 0.015% maker when fetched on October 29. A $10,000 taker open-and-close at that base rate is approximately $9.00 before the same omitted costs. Hyperliquid tiers, staking discounts, growth-mode markets, and rebates can lower effective rates, so this is a base-rate comparison rather than a claim that every Extended trade is cheaper.
Extended also publishes maker rebates based on 30-day market share. Standard rebates range from 0.002% at a minimum 0.5% share to 0.010% at a minimum 5% share; RWA rebates are lower. Rebates accrue automatically and are paid daily only when the prior day’s rebate reaches at least $10. Most retail users should regard these as professional-liquidity incentives rather than assume they will receive a negative effective maker fee.
Extended compared with Hyperliquid, dYdX, and Ostium
Extended competes across two overlapping groups. Hyperliquid and dYdX are order-book perpetual venues with volume-based fee systems, while Ostium targets many of the same RWA categories through a different bid/ask and oracle-driven model. Comparing only headline fees would obscure these structural differences.
In this specific $10,000 base-rate comparison, Extended has the lowest published starting fee, particularly for RWA taker flow. Hyperliquid may become more competitive through tiers and discounts, dYdX depends on its active governance schedule and user volume, and Ostium uses a different cost model that becomes more sensitive to holding time.
Architecture, audits, and the documentation transition
Extended’s own materials describe its security model through several layers. The architecture page describes self-custodied contracts, on-chain risk checks, external oracle conditions for liquidation, and zero-knowledge proof verification, a cryptographic method for attesting that off-chain computations were executed correctly without re-executing them. The audit page says the on-chain logic and contracts have been reviewed by ChainSecurity and through a public audit competition. The API documentation says read-only calls use an API key, while order, transfer, and withdrawal operations also require a Stark signature.
The complication is that these pages do not currently present one perfectly synchronized account. The architecture page, updated October 27, says settlement is on Arc and emphasizes EVM compatibility. The API documentation fetched October 29 still identifies Starknet mainnet endpoints, Stark keys, Stark signatures, and Starknet settlement. This should be treated as a migration-related documentation gap that must be resolved against the live application before funding or integration.
Transitions of this kind have precedent in the sector: dYdX previously operated on StarkWare’s StarkEx technology before moving to its own application-specific chain in 2023, and its documentation, signing flow, and endpoints changed with the move. The practical signal to watch for Extended is when the API documentation’s network references and signing instructions begin to match the Arc architecture page. Until the two sources agree, developers working from existing examples risk integrating against the wrong network, and depositors risk following outdated routing instructions.
Before funding an account or building an integration, users and developers should confirm the live network, contract addresses, wallet type, bridge route, signing domain, and API endpoints in the application and current migration documentation. An older Starknet workflow should not be reused merely because an API example remains online, and an Arc statement should not automatically be assumed to apply to every live endpoint.
An audit is evidence of external review, not a safety certificate. Users should check report scope, commit hashes, unresolved findings, deployed bytecode, upgrade controls, and bridge contracts. Audits reduce uncertainty but do not eliminate smart-contract, oracle, bridge, or operational risk.
Deposits and withdrawals
The deposit and withdrawal documentation lists USDC, cirBTC, and ETH. For EVM-wallet users, it documents routes across combinations of Ethereum, Arbitrum, Base, Arc, BNB Chain, Polygon, and Avalanche. It also warns that timing and limits depend on Rhino.fi bridge liquidity.
This arrangement adds route risk. Bridges have historically been a repeated point of failure in digital-asset infrastructure, which makes the documentation’s own liquidity warning material rather than boilerplate. Users must match the asset, source chain, destination, wallet type, and live bridge instructions. The documentation lists typical processing times ranging from roughly one minute to several hours depending on chain, asset, and size; these are estimates rather than guarantees.
A safer first-funding workflow is to use a small test deposit on the exact route shown in the connected account, wait for it to credit, and then make a small withdrawal to the intended destination before committing meaningful collateral. The live confirmation screen should be treated as the final source for minimums, fees, and route availability.
Regional access and other material risks
The restricted-countries page currently includes the United States, United Kingdom, Canada, China (Hong Kong), Russia, and several other jurisdictions. It also restricts access wherever use would conflict with applicable law. Eligibility should be checked before opening an account or moving collateral.
Other risks remain for eligible users:
- Leverage and liquidation: The selector showed ceilings from 10x to 50x in the captured rows, while the overview advertises leverage of up to 100x. Maximum leverage is a risk limit, not a sensible default.
- RWA session and oracle risk: An equity, index, commodity, or FX reference can have market hours, closures, gaps, and oracle behavior that differ from 24/7 crypto markets.
- RFQ versus order-book execution: An RFQ marker indicates a different execution model. Quote availability and expiry can differ from visible central-limit-order-book depth.
- Funding and borrowing: The displayed funding rate changes. Unified-margin and lending features can add interest and cross-collateral dependencies.
- Bridge risk: Deposits and withdrawals may rely on external bridge liquidity and infrastructure.
- Documentation drift: Network, route, and API instructions can lag behind a migration. Live details should be confirmed before signing.
Who is Extended for?
Extended is best suited to experienced perpetual traders who want crypto and RWA references in one workspace, value an order-book interface, and are willing to read market-specific rules. Market makers may also find the zero published maker fee and volume-share rebate schedule attractive, subject to actual liquidity and eligibility.
It is less suitable for beginners seeking simple spot ownership, anyone who interprets an RWA perpetual as ownership of a stock or commodity, users in restricted jurisdictions, or traders unwilling to manage leverage, funding, liquidation, bridge, and oracle risk. The public interface is approachable, but the product underneath it is not simple.
A safer way to start
Check eligibility first. Read the current restricted-countries page and terms without attempting to route around them.
Identify the exact market model. Confirm whether the instrument is perpetual or spot, whether it is classified as Crypto or RWA, and whether execution uses an order book or RFQ.
Read the Trading Rules and Margin Schedule. Verify leverage, collateral contribution, maintenance margin, oracle, funding, and trading session.
Confirm the live network and route. Reconcile Arc migration information with the connected wallet, contract addresses, bridge, and current API documentation.
Test funding with a small amount. Deposit and withdraw a small sum before increasing collateral.
Use low leverage for the first controlled trade. Do not copy the 50x or 100x marketing ceiling.
Calculate total cost. Include maker/taker fees, spread, slippage, funding, borrowing, and bridge costs—not just the 0.025% headline rate.
Treat advanced orders as tools, not guarantees. Understand Chase’s dependence on the browser tab, take-profit and stop-loss triggers, and RFQ behavior before relying on them.
Verdict
Extended delivers one of the more informative public perp-DEX terminals tested in this review. The interface loaded cleanly through an eligible observation route, exposed real-time market context without login, and made crypto and RWA discovery unusually fast. Its flat fee schedule is competitive at the published base rate, and its documented order toolkit extends well beyond the three default ticket tabs.
The primary issue is not the trading layout but the documentation transition. Current Arc architecture material and Starknet-oriented API documentation need to be reconciled before a user or developer assumes a particular network workflow. Extended is most compelling for experienced traders who value low published fees, RWA breadth, and advanced orders while remaining willing to validate each market, route, and signature flow.
FAQ
Is Extended Exchange a DEX?
Extended describes itself as a self-custodial perpetual DEX. Its current architecture documentation says user funds remain in on-chain contracts and risk checks are enforced on-chain. That description does not eliminate contract, oracle, bridge, or market risk.
What are Extended’s trading fees?
The current published schedule lists 0% maker and 0.025% taker for standard perpetual and spot markets, and 0% maker and 0.010% taker for RWA markets. Effective total cost also includes spread, slippage, funding, borrowing, and bridging.
Does Extended offer stocks and commodities?
The selector includes RWA references such as equity, index, commodity, and FX markets. These are derivative or spot-market instruments defined by the platform. An RWA perpetual is not ownership of the underlying share or commodity.
Is Extended on Arc or Starknet?
The current architecture page says Arc, while the API documentation fetched on October 29 still contains Starknet endpoints and signing instructions. This should be treated as migration-related documentation drift. The live network, contracts, and route should be confirmed before depositing or integrating.
This article is for informational purposes only and does not constitute financial or investment advice. Cryptocurrency and digital-asset markets carry significant risk. Always conduct independent research before making decisions.

