Crypto's Next Growth Phase May Rest on Dollars, Not Bitcoin
Key Takeaways
- •Circle launched a service on September 21 allowing eligible institutional customers to borrow USDC against Bitcoin-backed cirBTC collateral through third-party markets, with Morpho available at launch.
- •Mastercard is expanding regulated stablecoin settlement capabilities, beginning USDC in select markets and adding support for PYUSD, RLUSD and SoFiUSD through network partners in a staged expansion.
- •Adjusted stablecoin transaction volume rose 58% and transaction counts increased 35% in the 12 months through August 31, according to Visa Onchain Analytics.
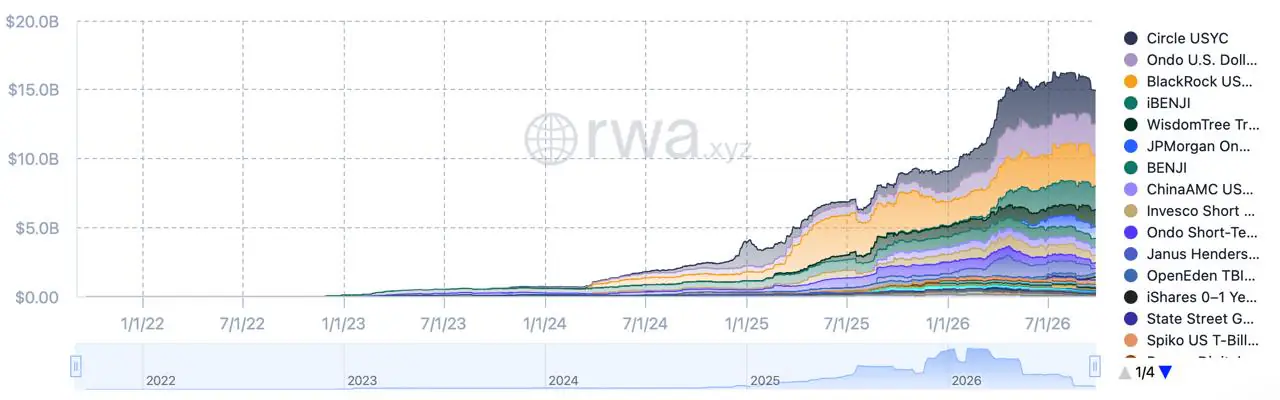
- •Tokenized Treasury products showed about $14.94 billion in distributed value as of September 26, while the SEC's temporary Innovation Exemption opened a conditional route for permissioned trading of certain tokenized U.S. stocks.
- •Dollar-denominated products can deepen onchain infrastructure without creating demand for Bitcoin or other volatile assets, and stablecoins remain exposed to risks around issuer reserves, redemption rights and legal protections.
For most of crypto's history, participation began with a single decision: whether to buy Bitcoin. That entry point is no longer the only one. A company or investor can now step into the same financial system through a dollar balance, a settlement workflow, a loan collateralized with Bitcoin, or a tokenized fund—without first taking a position on BTC's price.
That shift underpins a different model of growth. Dollar-denominated products can bring users, companies and capital onchain through familiar financial tasks. They may deepen the infrastructure surrounding crypto, but they do not, by themselves, create demand for Bitcoin, Ether or any other volatile asset.
Why Onchain Finance Needs a Dollar Working Balance
Bitcoin can function as an investment vehicle, a reserve asset or collateral, yet it makes an awkward default unit for payroll, invoicing and short-term cash management. Its price can move materially before a merchant, borrower or treasury team has completed a transaction. A dollar-pegged token—what the industry calls a stablecoin—addresses a different problem: it keeps the unit of account familiar while moving the transfer and settlement process onto blockchain rails.
Circle's September 21 launch illustrates that division of labor. Under the official announcement, eligible Circle Mint customers can post BTC-backed cirBTC as collateral to borrow USDC through third-party markets, with Morpho available at launch. The borrower keeps exposure to Bitcoin; the dollar token is the liquidity they can use, account for or deploy. Collateralized borrowing itself is a structure traditional finance already knows—raising liquidity against an asset without selling it—so the newer element is the venue rather than the mechanism. It remains an institutional product with eligibility limits—not evidence of mass-market credit adoption—but it shows how the two assets can play distinct roles within a single transaction.
Settlement Rails Move Beyond Crypto Exchanges
Payment networks are testing the same working-balance idea from the settlement side. Mastercard says it is expanding regulated stablecoin settlement capabilities, starting with USDC in select markets and adding support for PYUSD, RLUSD, SoFiUSD and other tokens—issued by PayPal, Ripple and SoFi respectively—through network partners. The practical use case is back-end settlement: participating financial firms can test whether certain obligations can move outside conventional banking cut-off times. Mastercard describes a staged expansion, not a global live rollout, so which tokens, markets and partners are added next will indicate whether the capability graduates from pilot to production.
In practice, an onchain dollar working balance can be used to:
- send or settle a payment;
- hold short-term cash;
- borrow against crypto collateral;
- buy a tokenized financial asset.
Usage data point in the same direction. Visa Onchain Analytics reported that adjusted stablecoin volume climbed 58% while transaction counts rose 35% in the 12 months through August 31. Adjusted measures are more informative than raw blockchain totals because they attempt to filter out activity that can inflate headline figures.
From Dollar Balances to Onchain Markets
A digital dollar becomes more useful when it can settle an investment, not merely wait for the next crypto trade. That is why tokenized Treasuries, funds and certain securities matter to the stablecoin story: they give onchain cash a purpose beyond transfers and crypto-exchange liquidity.
The RWA.xyz tokenized-Treasury dashboard showed about $14.94 billion in distributed value when checked on September 26. The total remains tiny beside the conventional Treasury market, but it is large enough to establish tokenized cash management as a functioning category. The harder test is whether investors can reliably enter and exit those products in secondary markets, rather than only buying new issuance.
The U.S. Securities and Exchange Commission has also opened a narrow route that connects the settlement question with investment products. Its temporary Innovation Exemption allows qualifying venues to seek conditional relief for permissioned trading in certain tokenized U.S. stocks, with the framework open for public comment. Access, custody and shareholder rights remain central conditions; a token that tracks a share price is not automatically the same as owning that share. Coindoo's analysis of the SEC's tokenized-stock route explains why the framework remains a controlled market test.
Where the Link to Crypto-Asset Demand Breaks
The bridge from dollar usage to a broader crypto market is indirect. Dollar products may bring firms onchain; recurring balances may justify better wallets, custody and compliance systems; and deeper infrastructure may make other assets easier to access. The final step still depends on whether users choose to deploy that liquidity into volatile tokens, tokenized securities or lending markets.
That is why stablecoin growth can remain largely inside a dollar loop. A business may use USDC for a weekend payment, while an investor may hold tokenized Treasuries for yield; neither action necessarily increases demand for Bitcoin. The more compelling adoption case would involve users and institutions moving between payments, cash products, collateral and regulated investment markets—not simply holding a larger stablecoin balance.
There is a methodological reason for caution, too. McKinsey has warned that headline stablecoin transaction totals can overstate real economic use, because trading, internal transfers and automated activity are commingled in the data. Higher volume can be meaningful without proving that blockchain payments have become a broad consumer habit.
Even if payment and investment use widens, a separate question remains: what legal claim, redemption right and operational protection does each onchain dollar actually give its holder?
Growth Does Not Remove the New Risks
Moving dollars onchain does not make them risk-free. Stablecoins still depend on issuer reserves, redemption arrangements, legal claims and banking access. Tokenized assets may add transfer restrictions, thin liquidity and rights that differ from those attached to the asset they reference. The Bank for International Settlements has argued that programmable money can improve settlement and collateral movement while leaving difficult questions open around redemption, interoperability, integrity and the role of issuers.
The useful comparison is therefore not “crypto versus banks.” It is whether a particular onchain product offers a clearer, cheaper or more flexible service than the existing alternative—and whether its legal and operational protections are clear before something goes wrong.
What Would Show That the Shift Is Real?
The evidence should amount to more than rising stablecoin market capitalization or a strong Bitcoin candle. A durable change would show up in several places at once:
- Better transaction quality: payment, payroll, settlement and business-transfer activity growing alongside trading flowsn- Production use: card, bank and treasury products moving beyond limited pilots and announcements;
- Secondary liquidity: tokenized Treasury, fund and equity products becoming easier to buy and sell;
- Institutional behavior: companies using onchain dollars for ordinary treasury and collateral operations;
- Clearer protections: workable rules on redemption, custody, disclosures and investor rights.
The Next On-Ramp May Not Look Like Crypto
Bitcoin can remain central to a future expansion without being the product that starts it. The next user may arrive through a corporate settlement tool, a regulated fund, a dollar balance in a wallet, or a loan secured by assets they already own.
If digital dollars become a normal tool for paying, settling, managing cash and investing, crypto's growth will be built on dollars, not Bitcoin. Whether that foundation later supports speculative demand for volatile tokens will depend on risk appetite and individual investment decisions. The decisive test comes earlier: whether an onchain dollar balance turns into repeatable financial activity, rather than simply a larger stablecoin supply.
This article originally appeared on Coindoo.*

