COIN Stock Gains 5% as Morgan Stanley Raises Coinbase Price Target to $258
Key Takeaways
- •Coinbase shares closed 4.30% higher at $179.39 on Oct. 9 after hitting an intraday high of $183.61, as Bitcoin stabilized ahead of the exchange's Oct. 29 third-quarter earnings report.
- •Morgan Stanley raised its Coinbase price target to $258 from $250 in an Oct. 9 earnings preview while retaining its Equal Weight rating, implying roughly 42.6% upside from the quoted midday price.
- •Citizens JMP lowered its Coinbase target from $325 to $280, a $45 reduction, while maintaining its Market Outperform rating, leaving its target $22 above Morgan Stanley's.
- •Coinbase posted $1.22 billion in second-quarter revenue, an 18.5% year-over-year decline, alongside a $359.5 million net loss, with transaction revenue of $599 million as its largest revenue category.
- •The exchange increased its share of crypto trading volume to 10.3% in the second quarter from 9.1% in the first and has expanded into stock and ETF trading, with single-stock futures plans filed but no launch date announced.
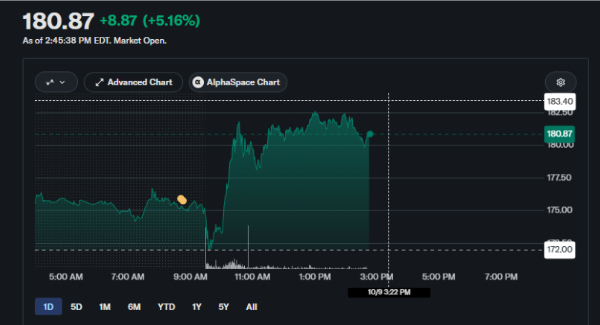
Coinbase Global (NASDAQ: COIN) shares closed sharply higher on Oct. 9 as Bitcoin stabilized and Wall Street analysts updated their forecasts for the crypto exchange ahead of its third-quarter earnings report, expected on Oct. 29. COIN ended the session at $179.39, up 4.30%, after reaching an intraday high of $183.61.
The analyst revisions were mixed. Morgan Stanley raised its Coinbase price target to $258 from $250, while Citizens JMP lowered its forecast to $280 from $325. Such previews are a routine part of earnings season, when analysts adjust models and targets ahead of quarterly reports.
Coinbase Stock Rallies More Than 4%
Coinbase shares traded around $175 during early trading before falling toward $172 around the regular market open. Buyers then pushed the price above $178 during a rapid rebound. COIN crossed $180 later in the morning and continued moving higher around midday.
The advance carried shares toward $182.50 during the early afternoon. Prices then retreated toward $180 before returning to $180.87 by 2:45 p.m. EDT. The stock maintained much of its morning advance even after the midday fluctuations. Trading volume rose sharply during the morning price swing before easing later in the session.
Morgan Stanley Lifts Coinbase Price Target
Morgan Stanley increased its Coinbase stock price target by $8, or 3.2%, in an Oct. 9 earnings preview, up from its earlier $250 target. The investment bank retained its Equal Weight rating — typically an indication that an analyst expects a stock to perform roughly in line with its sector — which it first assigned when initiating coverage in September.
Morgan Stanley raises Coinbase price target to $258 from $250 as part of earnings preview. @coinbase pic.twitter.com/SPLE0cXPpG — MSB Intel (@MSBIntel) October 9, 2026
At the quoted market price of $180.87, the new $258 target stood approximately 42.6% higher. Morgan Stanley revised its target while reviewing brokers, exchanges and other capital markets businesses ahead of their quarterly results.
Citizens JMP also updated its Coinbase forecast on Oct. 9, but moved in the opposite direction. The firm cut its target from $325 to $280, a reduction of $45, while maintaining its Market Outperform rating, a designation that generally signals expected above-market returns — leaving its new target $22 above Morgan Stanley's forecast.
Other analysts published lower price estimates. Goldman Sachs reiterated a Buy rating and a $244 target during the week. Cantor Fitzgerald maintained an Overweight rating with a $212 target in late August. MarketBeat listed 20 Buy ratings, 13 Hold ratings and three Sell ratings, with a reported consensus target of $224.29, though estimates varied across firms. At the Oct. 9 close of $179.39, that consensus figure stood about 25% higher, with the named targets ranging from Cantor Fitzgerald's $212 to Citizens JMP's $280.
Coinbase Earnings and Business Expansion
Coinbase reported $1.22 billion in second-quarter revenue, an 18.5% decline from the previous year, alongside a $359.5 million net loss. Transaction revenue came in at $599 million, with consumer trading contributing $452 million as trading conditions weighed on the quarter's results. Transaction revenue was the company's largest single revenue category — a dependence that helps explain why the stock is closely tied to cryptocurrency market conditions.
Subscription and services revenue reached $555 million, including $292 million from stablecoins. Coinbase reported average USDC balances of $20 billion across its products. The exchange also increased its share of crypto trading volume to10.3%, up from 9.1% in the first quarter. The Oct. 29 report will show whether those gains continued through the third quarter.
The company continued expanding its product range beyond cryptocurrency transactions. Coinbase introduced stock and ETF trading for eligible US users and pursued additional derivatives products, moves that extend its lineup into territory traditionally occupied by brokerage firms. September filings outlined plans for single-stock futures products under US regulatory supervision, though the exchange has not announced a launch date for those contracts.
This article is for informational purposes only and does not constitute financial or investment advice. Analyst targets, earnings estimates and stock prices may change as market conditions evolve.

