CLARITY Act Stalls in Senate as SEC and CFTC Advance Crypto Rules
Key Takeaways
- •The Senate failed to advance the CLARITY Act in a September 15 procedural vote, a setback that is not a final rejection, and no new vote is currently scheduled.
- •The proposed act would establish a federal framework defining when tokens are securities or commodities, dividing SEC and CFTC oversight, and setting registration and consumer-protection requirements.
- •The CFTC's September 24 FAQ update clarified how registrants may use tokenized permitted investments and blockchain-based recordkeeping, applying existing rules without creating binding regulations or expanding eligible investments.
- •The SEC approved a temporary, conditional five-year exemption on September 17 permitting limited trading of tokenized U.S. stocks in permissioned settings, with a public comment request, and its scope does not cover altcoin products or all crypto platforms.
- •Questions of jurisdiction, firm registration, and consumer safeguards remain unresolved and can only be settled by Congress through legislation.
The CLARITY Act has stalled in Congress, but U.S. crypto regulation continues to advance through agency action. The Securities and Exchange Commission (SEC), which oversees securities markets, and the Commodity Futures Trading Commission (CFTC), which regulates derivatives and futures, are applying existing authority to tokenization, recordkeeping, and trading, shaping compliance expectations as institutions assess digital assets, including altcoins. What agencies cannot do is settle the questions of jurisdiction, registration, and consumer safeguards that only Congress can address.
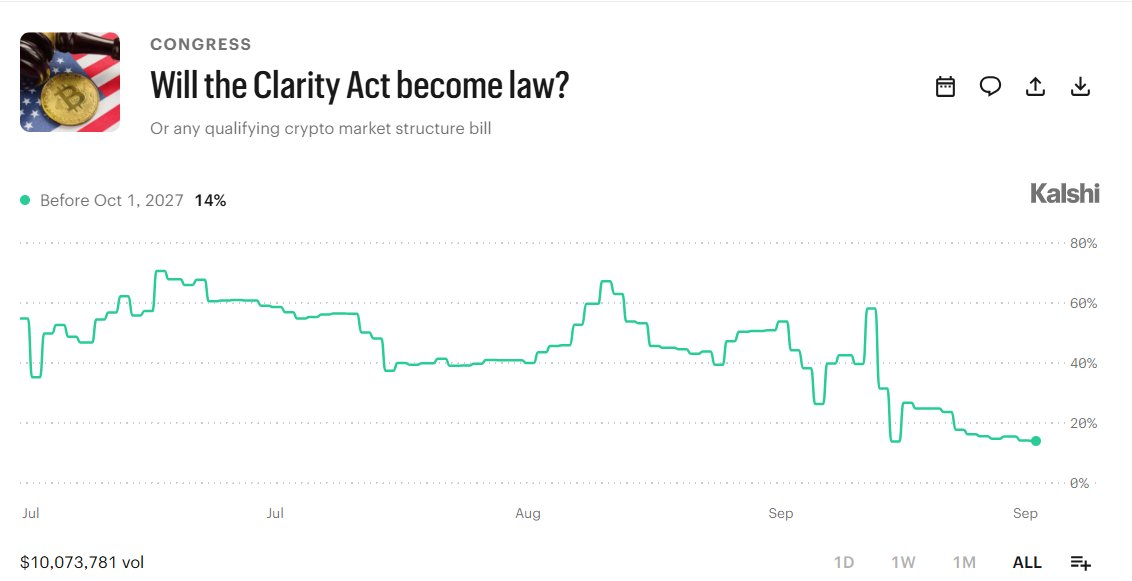
On September 15, the Senate failed to advance the CLARITY Act in a procedural vote — a setback, though not a final rejection. Ahead of the vote, a prediction-market contract put the bill's odds of becoming law in 2026 near 14%, a calendar-year estimate rather than a forecast for the following twelve months. No new vote is currently scheduled.
What the CLARITY Act Would Change
The CLARITY Act would establish a federal market-structure framework for digital assets. It would define when tokens qualify as securities or commodities, divide SEC and CFTC oversight, and set registration and consumer-protection requirements. Clearer categories could reduce jurisdictional disputes and help firms decide how to operate, while giving investors a firmer basis for understanding the duties of the platforms they use.
Those duties matter most when an exchange holds customer assets. Users want to know how firms must safeguard funds, keep records, and respond to breaches or losses. Rules under the act could support consistent compliance across platforms, though they would not guarantee safety, prevent every hack, or shield investors from losses driven by volatility.
A federal framework could also influence institutional participation. Retirement plans, insurers, and asset managers could assess crypto exposure against clearer responsibilities and safeguards, and registration pathways might attract more buyers and sellers, supporting liquidity and price discovery. Institutions would still need to weigh custody arrangements, demand, liquidity, and the risks of volatile assets.
SEC and CFTC Move Ahead While Congress Stalls
The CFTC's September 24 FAQ update illustrates how agencies are proceeding. Staff clarified how registrants may use tokenized forms of investments already permitted for customer funds and addressed blockchain-based systems for keeping and producing required records — questions with compliance implications across derivatives markets. The update does not expand the list of eligible investments or create a new regime; it applies existing requirements to tokenization and distributed ledgers.
The FAQs build on earlier staff guidance concerning tokenized collateral. According to the CFTC, the documents reflect staff views, create no binding rules, and amend no regulations. They can inform compliance planning, but they are narrower than a statute or an agency rule: the guidance concerns registered firms, not a comprehensive definition of digital assets or an allocation of SEC and CFTC jurisdiction.
The SEC has also acted under existing authority. On September 17, it approved a temporary, conditional exemption — set to last five years — for venues trading tokenized U.S. stocks in permissioned settings, as described in the agency's press release. The measure permits limited on-chain trading while the agency considers broader rules; the accompanying request for public comment gives market participants a defined process to track as the five-year window runs. It does not authorize all crypto platforms or approve altcoin products; its scope covers tokenized national-market-system stocks.
Why the Statute Still Matters
These examples show why the CLARITY Act remains relevant even as regulation advances piecemeal. Agencies can address narrower questions and test approaches, but their actions rest on current statutes. Guidance may change, exemptions carry conditions, and agency measures can face court challenges or leadership shifts. Congress could provide more durable rules for asset classifications, venue responsibilities, registration, and investor protections.
Greater legal certainty could help institutions evaluate crypto, but regulation is not a government endorsement. Bitcoin and other cryptocurrencies remain speculative and volatile, and the CLARITY Act would not make those assets safe or eliminate market risk. Stablecoins and distributed-ledger systems may serve payment or settlement uses, particularly when tokens represent assets such as U.S. Treasurys — uses that differ from spending volatile crypto on everyday goods and carry distinct risks.
For now, the CFTC's FAQ update clarifies tokenized permitted investments and blockchain recordkeeping within existing rules, while the SEC's exemption addresses limited trading of tokenized stocks. The unresolved questions are the ones Congress alone can settle: who regulates each market, which firms must register, and what consumer protections users can expect. Until legislation resolves them, the signals to watch are procedural: whether the Senate schedules another vote on the CLARITY Act, how the SEC weighs comment on its tokenized-stock exemption, and whether CFTC staff issue further FAQs on tokenization.
Source: Blockonomi

