CBN Moves to Remove Four 'Brakes' Holding Back Nigeria's Fintech Growth
Key Takeaways
- •The Central Bank of Nigeria fragmented regulation, weak trust, exclusion, and fear of innovation as the four main brakes on the country's fintech industry.
- •The CBN's newly created Innovation Management division, headed by Abiodun Okunola, is tasked with coordinating between regulators so fintechs needing multiple licences, such as from NAICOM or PenCom, face fewer delays.
- •The CBN's 2026 fintech report proposes a Single Regulatory Window that would handle multi-agency compliance in one place, and its implementation is seen as a key test of reform.
- •Okunola estimated that roughly 40 million Nigerians living with disabilities are underserved by financial infrastructure and suggested iris-based verification for customers who cannot provide fingerprints.
- •He described interoperability among Nigeria's more than 430 fintech companies as a strategic priority and pointed to embedded-credit products like travel instalment plans as examples straining existing regulatory categories.
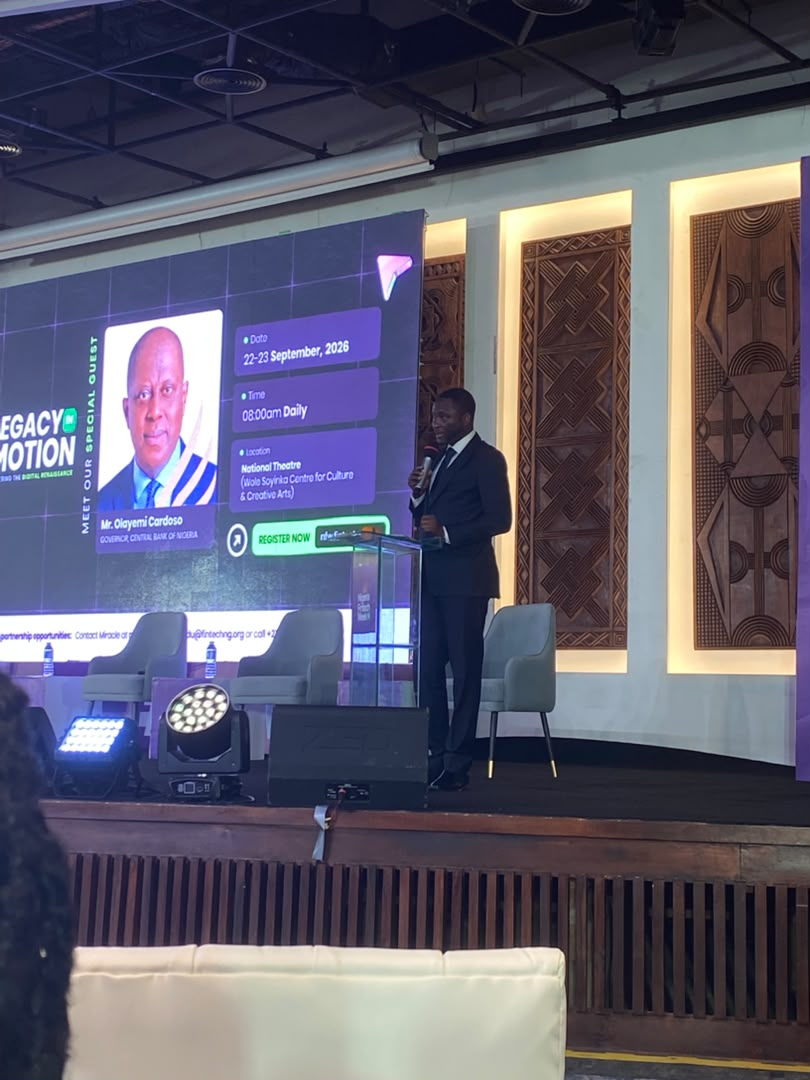
The Central Bank of Nigeria (CBN) is seeking to remove four major "brakes" it says are slowing the country's fintech industry, as new financial products stretch well beyond traditional banking and regulators work to keep pace with innovation.
Abiodun Okunola, speaking on behalf of CBN Governor Olayemi Cardoso at the opening of Nigeria Fintech Week 2026, named fragmentation, trust, exclusion and fear of innovation as the key challenges confronting Nigeria's digital financial system. The event is being held at the Wole Soyinka Centre for Culture and Creative Arts, formerly the National Theatre, and runs from September 22 to 23 under the theme "Legacy in Motion: Powering the Digital Renaissance." Each brake maps to a stage in how financial products actually reach Nigerians: how quickly they are approved, whether customers trust them, who can use them, and how entirely new categories are governed.
His remarks come as Nigerian fintech moves beyond basic payments into artificial intelligence, open finance, embedded finance, digital assets and cross-border payments — all major tracks at this year's event.
"Standing still is not stability; standing still is falling behind," Okunola told the audience. "The challenge isn't whether or not change will come, but whether we will have the courage, foresight, and coordination to steer it."
The First Brake: Fragmented Regulation
Okunola returned repeatedly to an uncomfortable truth: money moves faster than rulebooks. Financial innovation rarely arrives in a shape regulators already have a drawer for.
A fintech might start with payments, then expand into insurance, pensions and lending. Suddenly it is dealing not with one regulator but several, each with its own forms, timelines and definition of "compliance." Products that should take months can stall far longer — not because anyone objects, but because no single desk is built to wave them through.
"This is where CBN has also taken a departure," Okunola said, pointing to the central bank's newly created Innovation Management division, which he heads. The unit's mandate is to get regulators talking to one another so that companies building across those boundaries are not left to referee the conversation themselves.
A single fintech offering insurance alongside its core business, for instance, needs a licence from the CBN and another from NAICOM or PenCom — the National Insurance Commission and the National Pension Commission, which respectively oversee insurance and pensions.
"How do we speak to each other quickly," he asked, "so that because you have to get all these licences, you will not delay the value you are trying to deliver?"
The CBN's own 2026 fintech report suggests the industry has been asking the same question. Fragmentation, drawn-out approvals, ambiguous rules and mounting compliance costs all feature among concerns raised by market participants. The report floats a Single Regulatory Window to handle multi-agency compliance in one place.
The Second Brake: Trust in the Technology
A financial app can look sleek and move money in seconds, but none of that helps if people do not trust it with their cash or personal details.
Okunola described trust as the ground floor of every digital transaction. "Every payment may begin as a transaction, but it succeeds only when it ends in confidence," he said.
People need to believe their money will arrive, their data will stay private, fraud will be stopped or fixed, and complaints will be heard quickly. That job grows harder as artificial intelligence reshapes both financial services and financial crime. Okunola warned that criminals are already using AI to build smarter scams targeting customers and institutions alike. That puts AI on both sides of the ledger for Nigerian fintech — product frontier the industry is now building on, and a fraud vector its defences have to keep up with.
The lesson for fintechs: speed alone will not win customers. Systems that hold people's money must also be secure and dependable.
The Third Brake: Exclusion
Nigeria's fintech industry has spent years broadening access to finance through mobile apps, agent banking and digital payments. For Okunola, however, access is not the same as inclusion. His test case is people living with disabilities — roughly 40 million Nigerians, by his estimate — whom the country's financial infrastructure was never designed to serve.
He offered a blunt example: a blind customer walks into a bank with millions in their account, and the first thing they encounter is poor treatment. "Even if that person has 20 million Naira in their account, they do not treat them well," he said.
Then there are customers whose fingerprints cannot be captured. "Persons who have been affected with leprosy don't have fingerprints anymore," Okunola said, suggesting a switch to irises or other forms of identity verification. His broader point: these gaps are not just social problems — they are markets. "A lot of money to be made there," he said.
The Fourth Brake: Fear of Innovation
The final brake may be the hardest for regulators to admit: fear itself — the worry that technology is moving faster than the rules built to contain it. Regulators walk a fine line. Move too slowly, and useful products never reach the people who need them. Move too quickly, and consumers are exposed to risks nobody has fully worked out yet.
Okunola's answer is that regulation and innovation were never meant to be rivals. "Innovation and regulation should not be treated as opposing forces," he said.
What is needed, he argued, is for regulators to keep pace and keep learning from the industry they oversee. That matters more than ever, because the products now entering the market no longer slot neatly into old categories.
Okunola's examples showed how far fintech has drifted from banking. In embedded finance, non-financial companies sell financial products directly to customers.
"If you go to Air Peace and try to book a ticket, you see where they tell you, 'Do you want to pay small small?'" he said. Wakanow does the same, letting customers pay for trips in instalments.
"Now, think about it: they're offering credit. For us, they are non-bank; they are not licensed to offer credit. How do we regulate?"
That question captures the dilemma regulators now face: financial products keep turning up inside businesses nobody would call a financial institution. The stakes are practical: an instalment button on a travel site is, in the regulator's eyes, a credit product, whatever the company's core business may be. The same trend runs through open banking, digital assets, programmable money and cross-border payments, all on the agenda at Nigeria Fintech Week 2026.
Climate finance could open another market. Okunola pointed to Nigeria's carbon-market plans, under which farmers who preserve forests could earn carbon credits bought by companies elsewhere. "That means that there is going to be a need for fintech solutions that can make those payments possible," he said.
Interoperability as the Next Frontier
Nigeria already has more than 430 fintech companies, according to Nigeria Fintech Week organisers. The next challenge, Okunola argued, is getting them to work together. He called interoperability a strategic priority, saying platforms, institutions and regulators cannot keep operating in isolation.
"When systems connect and communicate securely, transactions become more reliable, the cost of participation declines, competition deepens, and innovation scales more rapidly," he said.
That, he suggested, is what "lifting the brakes" means. The CBN is not asking for regulation to vanish — only for pointless friction to go.
"Our task is not to remove discipline or abandon safeguards; it is to replace unnecessary friction with intelligent guardrails so that innovation can move at the speed of opportunity while remaining anchored in public interest," Okunola said.
Two markers will show whether that shift takes hold in practice: whether the Single Regulatory Window floated in the CBN's 2026 fintech report moves from proposal to a working system, and how much cross-agency coordination the Innovation Management division can turn into faster approvals.
The payments, companies and infrastructure are already in place. What happens next depends on whether regulators can make the system easier to navigate without making it less safe.

