Canada's Big Six Banks Build Tokenized Deposit Rails in Race Over On-Chain Money
Key Takeaways
- •Canada's Big Six banks jointly building Canadian dollar tokenized deposits to investigate whether regulated commercial bank deposits can replace exclusive reliance on cryptocurrencies for blockchain settlement.
- •OSFI stated on September 10 that tokenized deposits are legally no different from conventional deposits, so banks can operate under the existing regulatory framework instead of waiting for new legislation.
- •Tokenized deposits are ordinary bank liabilities represented and transferred on distributed-ledger technology, offering programmability, faster payments, and around-the-clock operation within the regulated banking space.
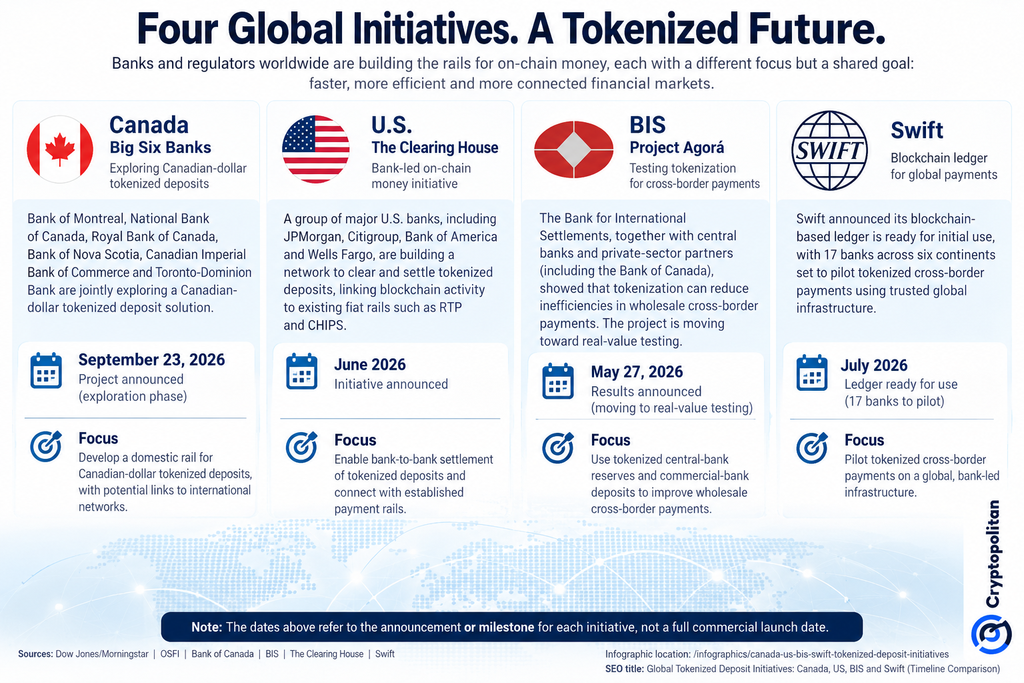
- •Canada's project mirrors parallel initiatives, including BIS Project Agorá, a U.S. bank-led tokenized deposit network operated by The Clearing House, and a SWIFT blockchain ledger trial involving 17 banks.
- •The initiative remains exploratory rather than a launch, with Citi Institute estimating tokenized assets could reach $5.5 trillion by 2030 in its base case.
Canada's six largest banks are jointly building Canadian dollar tokenized deposits, part of a broader worldwide effort to determine which form of money will be used to settle tokenized payments, securities, and real-world assets.
Bank of Montreal, National Bank of Canada, Royal Bank of Canada, Bank of Nova Scotia, Canadian Imperial Bank of Commerce, and Toronto-Dominion Bank are joining forces in the project. Canada's leading lenders are investigating whether regulated commercial bank deposits can replace an exclusive reliance on cryptocurrencies for blockchain settlement.
A bank deposit, represented on a blockchain
As reported by Dow Jones Newswires, the initiative is a first step toward upgrading Canada's domestic payment systems.
Tokenized deposits are essentially ordinary bank deposits, with one difference: they are represented and transferred through distributed-ledger technology (DLT) rather than traditional rails, and they do not constitute a distinct asset class. According to the IMF, these deposits are recorded as bank liabilities that are held, recorded, and transacted on blockchain or other DLT infrastructure.
Their value lies in programmability without leaving the regulated banking space. Banks could raise the efficiency and speed of payments, operate around the clock, and embed instructions in transfers as complex code. The first step is to enable deposit transfers between Canadian financial institutions, with links to other digital-asset networks possible at a later stage.
Why OSFI's ruling gives the project a foundation
The project benefits from regulatory clarity. In a statement released on September 10, the Office of the Superintendent of Financial Institutions (OSFI), the federal regulator that supervises Canada's banks, said tokenized deposits are legally no different from conventional deposits, reiterating its technology-neutral approach to the matter.
"The underlying technology of a financial product or service does not determine its legal nature." — OSFI
The distinction carries significant implications. Because OSFI supervises the Big Six, banks can continue to operate under the existing regulatory framework governing financial institutions instead of waiting for legislators to create a new legal regime covering tokenized deposits. OSFI nevertheless continues to expect regulated entities to comply with applicable regulatory requirements on technology, cyber, and third-party risks.
Canada has already tested some of the basic infrastructure. Project Samara, a Bank of Canada experiment, involved TD, RBC, and Export Development Canada in implementing DLT and a wholesale central-bank digital currency in a tokenized bond transaction. The project concluded that atomic settlement can work in principle, while identifying challenges related to complexity, governance, liquidity, operations, and legal alignment.
The same bet, playing out across four initiatives
Canada is not alone in this approach. In May, the Bank for International Settlements (BIS), the Basel-based institution that serves the world's central banks, reported that Project Agorá had shown tokenization could enhance the efficiency of wholesale cross-border payments through tokenized central-bank reserves combined with deposits held at commercial banks. The project is moving into real-world testing of the concept, and the Bank of Canada is part of it.
In June, major banks in the United States introduced a bank-led initiative. The Clearing House will operate the program, allowing tokenized deposits to be cleared and settled while linking blockchain to existing systems it operates, such as the RTP real-time payments network and the CHIPS clearing system.
"This initiative brings together the innovation of digital finance with the trust, scale, and settlement certainty of established bank payment infrastructure." — Mark Monaco, Bank of America
Cryptopolitan reported that JPMorgan, Citigroup, Bank of America, and Wells Fargo are among the institutions supporting the U.S. network.
In July, SWIFT, the messaging network that connects banks worldwide, stated that its blockchain ledger was ready for a real trial, with 17 banks from six continents prepared to test tokenized cross-border payments.
The four initiatives point in the same direction: regulated bank money is fighting to remain at the center of the financial market as settlement moves on-chain.
Deposits versus stablecoins, and the missing settlement layer
The deeper contest is between different forms of digital money. Tokenized deposits remain commercial-bank liabilities, while stablecoins are separate digital liabilities backed by reserve assets. The question is not simply which technology is faster, but which form of money institutions ultimately trust as the settlement layer for tokenized finance.
The opportunity is large but still early. Citi Institute estimates tokenized assets could reach $5.5 trillion by 2030 in its base case. Binance Research put the value of real-world assets on-chain at about $34.18 billion as of September 15, with only around 0.01% of addressable assets tokenized and roughly 12% of tracked tokenized capital actively used in lending, liquidity, or collateral.
For now, Canada's Big Six are exploring, not launching. The next questions are which technology they choose, whether more institutions join, and how Canada's domestic system eventually connects with the U.S., BIS, and SWIFT initiatives already moving toward live use.

