Busha COO Moyo Sodipo on Institutional Crypto Adoption, Regulation, and Why Crypto Complements Banking
Key Takeaways
- •Busha, founded in 2019, is a pioneer participant in Nigeria's SEC-led Accelerated Regulatory Incubation Programme, which now covers roughly 14 startups.
- •Moyo Sodipo states that digital assets are meant to complement, not replace, traditional finance infrastructure such as NIBSS Instant Payments.
- •Sodipo identifies the lack of harmonised regulatory clarity across the SEC, the Central Bank of Nigeria, and other authorities as the single biggest operational bottleneck for bank-exchange integration.
- •The CBN's restriction on banks servicing crypto operators was only formally relaxed in late 2023, leaving many institutions still awaiting explicit guidance.
- •Busha aims to serve as a regulatory-ready infrastructure layer providing technology, liquidity, and custody so banks and other institutions can offer digital asset services without building their own stacks.
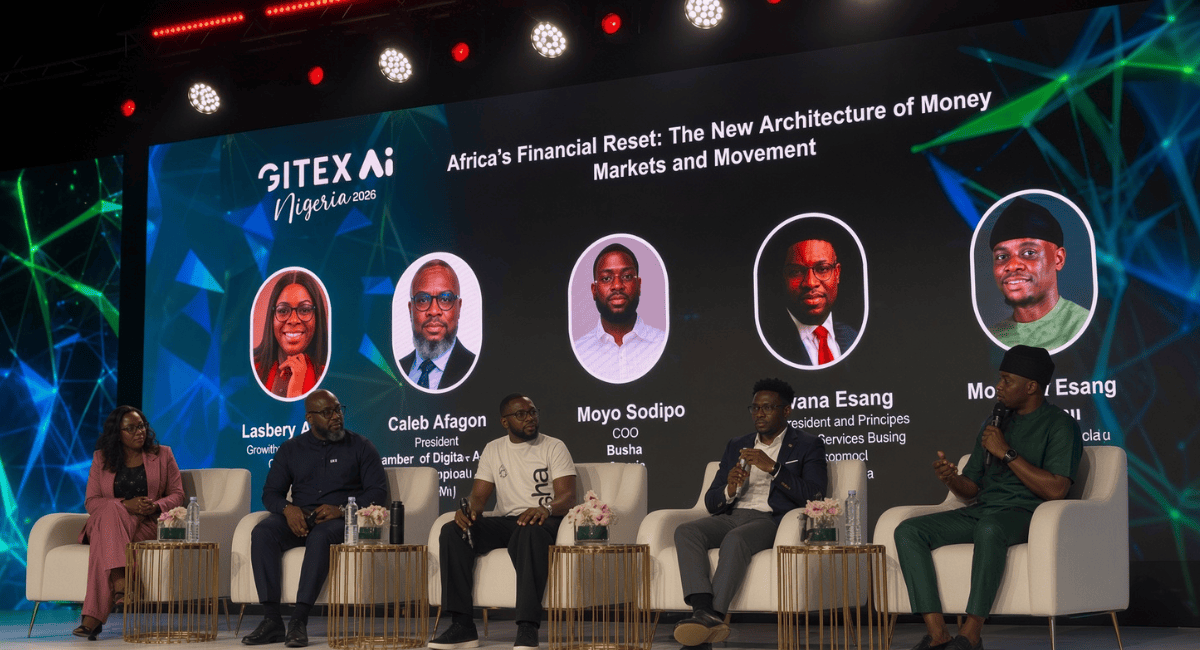
For years, Africa's crypto industry operated in the shadows. It functioned as a high-stakes, speculative arena where retail traders chased volatility while institutional capital watched nervously from the sidelines. That landscape is now shifting rapidly: regulatory sandboxes are replacing regulatory vacuums, and the conversation has moved from anonymous tokens to auditable infrastructure. The shift carries real weight for a continent where cross-border remittances remain costly and a large share of the population is underbanked — conditions that have already made Africa one of the world's fastest-growing regions for stablecoin and peer-to-peer crypto adoption.
At the recently concluded GITEX Nigeria 2026, the friction between legacy finance and digital assets took centre stage. If fiat currency's enduring dominance rests on generational trust rather than technical efficiency, then native digital asset platforms face a colossal challenge in persuading the everyday Nigerian to make the switch.
Moyo Sodipo, Co-founder and Chief Operating Officer of Busha, believes the answer lies in tangible utility and unapologetic compliance. Busha, founded in 2019, has grown into one of Nigeria's better-known licensed digital asset exchanges. As a pioneer within Nigeria's Accelerated Regulatory Incubation Programme (ARIP) — the Securities and Exchange Commission's framework for onboarding digital asset operators under interim supervision — Busha is betting that harmonised regulation is the ultimate catalyst for institutional adoption.
In this exclusive interview with Technext, Sodipo dismantles the notion that crypto aims to replace traditional banking, arguing instead that compliant digital assets are the missing bridge for Africa's economic integration.
Building trust beyond speculation
Q: During the panel session, an executive from Mastercard identified trust as one of the fundamental reasons people still prefer fiat currency over stablecoins or cryptocurrency. If fiat's primary moat is institutional trust rather than technical efficiency, what tangible mechanisms is Busha deploying to win over the conservative 90% of Nigerians who still view crypto rails with suspicion?
Moyo Sodipo: As I mentioned earlier, several centuries ago the medium of exchange was the cowrie shell. People transacted with cowries: you gave me cowries, and I gave you food. That system functioned because society trusted that cowries could subsequently be exchanged elsewhere for a commodity, a service, or equivalent value.
Today, people trust fiat currency because it is the primary instrument they have known and relied upon to settle value over generations. What Busha is doing now is demonstrating that digital assets, stablecoins, and crypto can perform practical functions grounded in everyday reality.
If you want to purchase groceries today, you can do so with digital assets — Busha has enabled that via our Spend feature. If you want to purchase airtime, you can do that using digital assets as well. The more physical outlets, merchants, and online platforms accept payments backed by digital assets, the more consumer trust will naturally compound.
It comes down to delivering practical, real-world utility. Beyond that, it requires sustained education across the board: educating the community, the public, active users, and regulators alike. When you demystify the technology, trust accrues over time.
Crucially, trust scales when adoption is driven by peer validation. It is not simply about an exchange telling people to adopt a product; it is about your brother telling you he just bought his coffee using digital assets. For us, the mandate is twofold: expanding tangible utility where digital assets solve immediate problems, and educating stakeholders on how to navigate the ecosystem safely.
Regulation as a trust anchor, not a barrier
Q: Before the Accelerated Regulatory Incubation Programme expanded to encompass around 14 startups in the SEC sandbox, Busha stood out among the pioneer cohort. Now that the regulatory landscape is solidifying, how has operating within a formal compliance framework influenced your unit economics and product velocity? Does adhering strictly to regulatory parameters risk pricing out the everyday retail traders who initially built your volumes?
Moyo Sodipo: No. Regulation does not price out the initial retail user base. What regulation actually achieves is that it anchors trust. It gives retail users and, more importantly, institutional players the confidence to participate on the platform.
Institutions want to know who the entities building the future of money are. They want to know who is deploying this technology to move value across borders and sectors. Crucially, they want to know who is supervising them to ensure operational integrity.
Regulation introduces standardisation, clarity, and credibility. When traditional financial actors observe regulatory oversight, their risk appetite shifts. The only way institutional capital integrates with this ecosystem is when regulated commercial banks feel legally safeguarded to partner with digital asset and stablecoin platforms.
Once that integration takes root, genuine commercial use cases expand dramatically. Fast-Moving Consumer Goods conglomerates, insurance underwriters, and stockbroking firms will actively explore how digital asset infrastructure can be embedded into their proprietary offerings. That is how the asset class enters the mainstream.
Today, a customer deposits capital in a commercial bank with confidence simply because the institution is licensed and supervised by the Central Bank. Our pioneer status within the regulatory framework signals to users outside our core early-adopter demographic that their capital is secure. They know Busha is governed by the Securities and Exchange Commission, which means their assets will not vanish overnight. Custody is accountable, and withdrawals are guaranteed.
On crypto not replacing the traditional banking rails
Q: Busha has rolled out dedicated merchant and payment features, but how much non-speculative commerce is genuinely moving through these rails as of today? Furthermore, what breaks first if you attempt to replace a conventional domestic payment rail like NIBSS Instant Payments with on-chain settlement for day-to-day retail transactions?
Moyo Sodipo: I always maintain that digital assets did not emerge to displace traditional finance; they exist to complement it. We are not looking to dismantle or replace NIBSS. We are designed to interface with NIBSS, complement its reach, and create an interoperable bridge where traditional finance and digital assets operate side by side. It is a notable framing in a market where NIBSS Instant Payments processes billions of transactions annually and remains the backbone of everyday digital commerce in Nigeria.
Consider the emergence of email. When electronic mail launched, traditional postal authorities feared it would render them completely obsolete. Instead, postal agencies evolved and communication channels diversified. If you need to transmit a simple one-page letter today, you do not rely on postal couriers; you send an email.
Digital assets offer an analogous leap in efficiency. Imagine arriving in a foreign country where you hold no local bank account but must transfer or settle value immediately. The broader world is transitioning to frictionless digital payments via systems like Apple Pay or Google Pay, while carrying large volumes of foreign physical cash across borders is obsolete and inefficient. With regulated digital assets, you can effortlessly settle into local stablecoins accepted in that jurisdiction.
Furthermore, blockchain rails provide an immutable audit trail. In legacy banking, accessing deep transactional records often demands formal bureaucratic requests to financial institutions. With on-chain settlement, transparency and reconciliation are instantaneous and publicly verifiable. It introduces heightened integrity and auditability to financial records rather than breaking existing infrastructure.
Busha's long-term competitive moat
Q: As payment aggregators and traditional fintechs begin embedding stablecoin settlement rails directly into their proprietary backends, where does Busha's long-term competitive moat lie?
Moyo Sodipo: Busha's objective is to serve as the foundational architecture and underlying infrastructure layer. We intend to be the primary engine that traditional financial institutions rely on whenever they interface with the digital asset economy.
I maintain accounts across conventional commercial banks because both ecosystems are complementary. When commercial banks, insurance houses, and asset managers determine that their retail and corporate clients require access to digital assets and stablecoin rails, they will not need to build that complex stack from scratch. Developing proprietary blockchain infrastructure outside one's core competence carries substantial operational and compliance risk.
Instead, institutions will partner with specialised, compliant operators. Busha provides the regulatory-ready technology stack, liquidity, and custodial infrastructure, enabling traditional partners to extend seamless digital asset capabilities to their end-users in real time.
Regulation: the single biggest bottleneck
Q: A truly borderless financial network requires friction-free interoperability between domestic bank accounts and digital asset ledgers. From your vantage point as co-founder of Busha, what is the single biggest operational bottleneck currently preventing traditional Nigerian banks and licensed digital asset exchanges from operating as seamless partners rather than wary counterparts?
Moyo Sodipo: One word: regulation.
We have not yet achieved comprehensive, harmonised regulatory clarity across all oversight bodies. At present, the ecosystem is navigating multiple sandboxes across the SEC, the Central Bank of Nigeria, and related regulatory authorities. Until these frameworks converge into a unified, mature standard, the systemic synergy you referenced will remain constrained. The caution is understandable in a market where the CBN previously restricted banks from servicing crypto operators — a stance only formally relaxed in late 2023, leaving many institutions still waiting for explicit, durable guidance.
As things stand, commercial banks frequently hold back, requiring formal no-objection letters or exhaustive circulars directly from the CBN before committing to deep integrations. Similarly, institutional market makers demand absolute clarity from the SEC. While progressive steps are occurring, execution is currently limited to the few institutions willing to embrace measured risk.
The primary hurdle remains transitional licensing. Many traditional players still view ARIP status as an interim sandbox rather than a full operating licence. The moment regulators establish an unambiguous, consolidated licensing regime, traditional financial institutions will gain the operational confidence to deploy digital asset solutions across their entire consumer base.
It mirrors the initial rollout of the GSM telecommunications revolution in Nigeria. During the early days, mobile phones were scarce and infrastructure was nascent. Today, the technology has matured to the point where our devices handle high-bandwidth data, mobile banking, and real-time video communication. The crypto sector is traversing that same trajectory. What will unlock the next era of scale is absolute regulatory certainty.
Does Nigeria have a decade?
Q: When you draw the GSM comparison, it raises a question of timing: achieving ubiquity in Nigerian telecom took over a decade. Given how rapidly the global blockchain landscape moves, does Nigeria really have a decade to bridge that divide with the rest of the world?
Moyo Sodipo: We are further along than it appears. Busha commenced operations roughly eight years ago, which means we are already approaching a decade of operational maturity within this market.
Reflect on how far the narrative has moved across those eight years. When we began, the public and regulatory discourse focused almost entirely on speculative crypto trading. Today, the conversation has matured toward regulated digital assets, programmable infrastructure, and stablecoins. That conceptual shift has opened doors that were previously shut.
Our terminology and operational standards have evolved to align with institutional and regulatory expectations. The focus is no longer on anonymous, speculative networks; it is on transparent, audit-ready financial architecture.
We are actively collaborating with regulatory authorities, opening our compliance and transaction monitoring processes to rigorous scrutiny, and ensuring robust safeguards prevent illicit flows across our rails. That institutional maturity is already compressing the adoption timeline. How quickly the SEC's sandbox graduates into full licences — and how readily commercial banks respond — will be the key developments to watch as the sector attempts to convert regulatory progress into mainstream institutional integration.
