Bitcoin Treasury Companies in 2026: Key Statistics, mNAV Dynamics, and Rising Risks
Key Takeaways
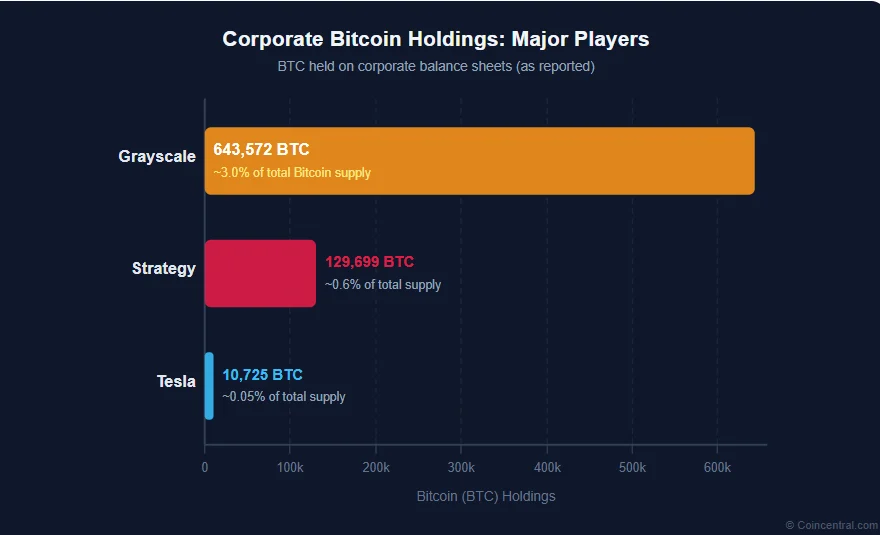
- •Grayscale, Strategy, and Tesla are the largest corporate Bitcoin holders, with approximately 643,572 BTC, 129,699 BTC, and 10,725 BTC respectively.
- •The model depends on an mNAV premium above 1x, which lets companies issue shares and increase the amount of Bitcoin backing each existing share.
- •Strategy's mNAV premium fell from nearly 4x in late 2024 to roughly 1x by 2026, and Bitcoin treasury firms shed an estimated $62 billion in value during the rout.
- •Analysts identify four principal risks: dilution without benefit, forced selling from convertible debt and preferred dividends, systemic selling pressure that could spiral into Bitcoin's price, and the lack of any underlying operating business.
- •Large players like Strategy are expected to weather the downturn, while smaller, heavily indebted latecomers face genuine pressure, and EU regulators are moving toward clearer disclosures under MiCA.
Bitcoin treasury companies are publicly traded firms whose principal asset is Bitcoin itself. Rather than earning revenue from products or services, these companies accumulate and hold large amounts of BTC, giving stock-market investors a route to Bitcoin exposure without directly touching crypto venues.
The blueprint traces back to Michael Saylor, the founder of MicroStrategy — since rebranded as Strategy. Beginning in 2020, Saylor started shifting his company's cash reserves into Bitcoin, arguing that BTC is the strongest long-term store of value available to corporations. Others followed suit. By the mid-2020s, dozens of publicly listed businesses worldwide were carrying Bitcoin on their balance sheets, and the model had gone global.
How the Model Works: Understanding the mNAV Premium
The concept at the heart of the Bitcoin treasury model is the mNAV, or modified Net Asset Value. In plain terms, it measures how much investors are willing to pay for a company's stock relative to the value of the Bitcoin the company actually holds.
When investor appetite runs high, the stock trades above the open-market value of the Bitcoin behind it. A company holding $1 billion worth of Bitcoin might command a market capitalization of $3 billion — an mNAV of 3x. Readers familiar with traditional markets will recognize the dynamic: closed-end funds have long traded at premiums or discounts to the net value of their underlying holdings, and mNAV applies a similar lens to companies whose principal asset is Bitcoin.
That premium is the engine driving the entire model. As long as it stays above 1x, the company can issue new shares and use the proceeds to buy still more Bitcoin. In theory, each round of buying increases the amount of BTC backing each share, rewarding existing shareholders.
The arithmetic works like this: if a company issues 10% more shares while trading at an mNAV of 3x, it raises three times the book value of its existing Bitcoin and can deploy that capital into additional purchases. Shareholders end up owning more BTC per share than before. During the bull market years, this loop worked brilliantly. The difficulty emerges when the market stops moving upward.
The Major Players: Who Holds What
A handful of companies account for the overwhelming majority of corporate Bitcoin holdings. The three most prominent are Grayscale, Strategy (formerly MicroStrategy), and Tesla.
Grayscale operates primarily as a crypto asset manager, offering publicly traded investment products tied to its crypto holdings. It currently holds approximately 643,572 BTC — around 3% of the total Bitcoin supply that will ever be mined — making it by far the largest single corporate holder of Bitcoin.
Strategy pursues a more aggressive playbook. Under Michael Saylor, the company funds its Bitcoin purchases through both equity offerings and debt, including convertible notes. It holds approximately 129,699 BTC, or roughly 0.6% of total supply.
Tesla's position is far smaller. The electric vehicle maker purchased approximately $1.5 billion worth of Bitcoin in early 2021, then sold a large portion of that holding in 2022. It now holds around 10,725 BTC — a foothold in the space without the aggressive accumulation strategy employed by others.
Approximate corporate Bitcoin holdings:
| Company | BTC Holdings (approx.) | Share of Total Supply |
|---|---|---|
| Grayscale | 643,572 | ~3% |
| Strategy (formerly MicroStrategy) | 129,699 | ~0.6% |
| Tesla | 10,725 | — |
The scale gap between the three is extreme: Grayscale holds more than four times as much Bitcoin as Strategy, while Tesla's holding is a fraction of Strategy's position.
The Rise: How the Model Gained Momentum
Between 2023 and 2024, the Bitcoin treasury model gathered serious momentum. Bitcoin's price climbed sharply, propelled by the approval of spot Bitcoin ETFs in the United States, growing institutional interest, and anticipation of the April 2024 halving event.
As Bitcoin's price rose, so did the mNAV premiums commanded by companies such as Strategy. At its peak in late 2024, Strategy traded at nearly four times the value of its Bitcoin holdings — a premium that made repeated share issuances and BTC purchases highly effective.
The playbook spread well beyond the United States. Companies in Japan, Canada, Europe, and the United Kingdom began copying it. Some were established businesses that pivoted toward Bitcoin accumulation; others were built from the ground up specifically to hold BTC.
By late 2024, the Bitcoin treasury company had become a recognized class of investment vehicle. Analysts described it as offering investors regulated access to Bitcoin-linked returns, layered with professional management. The excitement was real — and so were the risks building beneath it.
The 2026 Turning Point: When the Premium Disappeared
A model engineered for rising markets becomes far more fragile when prices stagnate or fall. That is precisely what played out through 2025 and into 2026.
Bitcoin's price stopped climbing at the pace investors had grown accustomed to. As enthusiasm cooled, mNAV premiums across treasury companies shrank steadily. Strategy's mNAV, which had touched nearly 4x in late 2024, declined through 2025 in a straight and consistent line. By 2026, it had fallen to close to 1x. The scale of the retrenchment was substantial: Bloomberg Intelligence analysis of the period described Bitcoin treasury firms shedding $62 billion in value as the crypto rout deepened.
Some smaller Bitcoin treasury companies began trading below the value of the Bitcoin on their books — effectively a negative premium on the management layer sitting atop the assets.
The shift matters because the entire model rests on the premium. Once it vanishes, the math of share issuance flips from positive to neutral — or worse, negative.
The Four Main Risks Analysts Are Watching
When the premium disappears, a set of risks that remained largely invisible during the bull market phase comes into focus Analysts have identified four main areas of concern.
Risk 1: Dilution Without Benefit
During the growth phase, issuing new shares to buy Bitcoin worked because the mNAV premium ensured each round of purchasing added more BTC per existing share. Once the premium falls to 1x or below, that arithmetic breaks down.
Issuing shares at or near book value hands away ownership without bringing in proportionally more Bitcoin. Shareholders end up owning a larger company with the same — or fewer — BTC per share. The strategy stops being accretive, yet many companies persist because they need cash to service debt.
Risk 2: The Threat of Forced Selling
Many Bitcoin treasury companies borrowed to fund their purchases — often through convertible notes, loans that can convert into shares at a fixed price — and issued preferred shares that require regular dividend payments.
These obligations persist regardless of what Bitcoin's price is doing. When Bitcoin falls and mNAV drops below 1, meeting those payments becomes harder. In a worst-case scenario, a company may be forced to liquidate part of its Bitcoin reserves to raise cash.
Analysts note that smaller treasury companies face this risk most acutely. They generally have less liquidity and fewer avenues for emergency capital than a large operation like Strategy.
Risk 3: Systemic Risk to the Broader Market
The model has spread across dozens of companies, all holding Bitcoin as their primary asset. A drop in Bitcoin's price hits every one of them simultaneously.
If multiple firms are forced to sell at once to cover debt or dividend obligations, the selling pressure lands on Bitcoin itself. Lower prices then push mNAV ratios down further, amplifying the pressure still more. Analysts describe this as a potential negative spiral: falling prices trigger forced selling, which pushes prices lower, which forces further selling.
This kind of systemic risk is unusual in equity markets. Few industries tie every major player to the same single underlying asset in this way.
Risk 4: No Underlying Business
Critics — including Wall Street analysts — point to a structural weakness unique to this model. Most Bitcoin treasury companies generate no revenue or profit from actual business operations.
Their entire value rests on two pillars: the price of Bitcoin, and investor confidence in the management team. If either weakens, there is no operating business to fall back on. That distinguishes them fundamentally from even the most volatile technology companies, which at minimum retain some form of recurring revenue, product, or intellectual property.
Debt, Dividends, and Dilution: The Numbers Behind the Risk
The capital structure of Bitcoin treasury companies is central to how these risks play out in practice. Many used a combination of financial instruments to fund purchases during the growth phase.
Convertible notes are a popular choice. These loans carry lower interest rates than conventional debt but embed complex terms around conversion triggers and refinancing deadlines. Preferred shares are another common tool: preferred shareholders receive fixed dividends before common shareholders receive anything. In a rising market, that is manageable; in a flat or falling one, it becomes a constant cash drain.
When Bitcoin's price is declining and mNAV sits at or below 1x, a company faces pressure from several directions at once — asset values falling, cheap fundraising closing off, and debt and dividend payments still due.
The arithmetic explains why the premium matters so much. At an mNAV of 4x, issuing 10% more shares adds roughly 27% more BTC per share for existing holders. At 1x, the same action adds nothing. At 0.8x, it nudges BTC per share slightly backwards.
For anyone tracking the sector, convertible note maturity dates and preferred dividend schedules are among the concrete calendar items to watch, since they mark the points at which fundraising pressure can convert into forced sales.
What Investors Need to Know
Buying shares in a Bitcoin treasury company is not the same as buying Bitcoin — a distinction some retail investors may not fully appreciate. Spot Bitcoin ETFs, approved in the United States, hold Bitcoin directly and trade on exchanges like conventional stocks; treasury company shares, by contrast, wrap Bitcoin exposure inside a corporate and capital structure.
Owning Bitcoin directly means exposure to a single variable: the price of BTC. Owning shares in a treasury company layers several additional risks on top. These include management risk — whether the team makes sound decisions on timing and capital — capital structure risk tied to how much debt the company carries and how it is structured, and access risk, meaning whether the company can raise fresh money when market conditions tighten.
A concrete example illustrates the difference. Two investors each put $10,000 into Bitcoin — one directly, one through Strategy shares. If Bitcoin rises 30%, the direct holder sees close to a 30% gain. The Strategy shareholder might see more, or significantly less, depending on mNAV movement, share dilution, and which debt obligations are maturing.
For many investors, the premium they paid for during 2023 and 2024 has become a source of risk rather than extra return. Those who bought at 3x or 4x mNAV and now face a 1x valuation are sitting on a gap that Bitcoin's own price gains would need to close before they break even.
The Regulatory Picture: EU and Beyond
In markets regulated by the European Union, the Bitcoin treasury model raises specific questions around transparency and investor protection. Regulators are drawing sharper lines between owning a crypto asset directly and owning shares in a company that holds that asset — two things that are legally and financially very different, even if the surface-level Bitcoin exposure appears similar.
The EU's Markets in Crypto-Assets regulation, known as MiCA, began phasing in from 2024 onward. While MiCA focuses primarily on crypto issuers and service providers, the growth of Bitcoin-heavy corporate vehicles has prompted regulators to examine more closely how these products are presented to everyday investors.
The core concern is that retail buyers may believe they are getting clean Bitcoin exposure when they are in fact buying a complex package of corporate, financial, and market risks. As the sector grows, European regulators — and counterparts elsewhere — are likely to push for clearer disclosures and stronger investor education requirements.
Can the Biggest Players Survive?
For the largest Bitcoin treasury companies, the answer is almost certainly yes — at least over the medium term. Strategy holds a very large Bitcoin position and has stated publicly that it will not sell under normal conditions. Its scale provides a long runway: even if Bitcoin's price declines or stays flat for an extended period, the company has enough financial flexibility to meet its obligations without being forced to liquidate. Analysts have said the company can “survive a long winter.”
Smaller companies occupy very different ground. Those that entered late, accumulated Bitcoin at elevated prices, and took on heavy debt to do so now face genuine pressure. Without deep reserves or reliable access to capital markets, conditions that are manageable Strategy can prove fatal for a smaller firm.
The companies best positioned to weather the current period are those that accumulated Bitcoin early, kept debt levels moderate, and did not build their entire business model around the assumption that the mNAV premium would last forever.
Looking Ahead: The Model's Two Faces
The Bitcoin treasury company model is not going away. The largest players are too well established, and holding Bitcoin as a corporate asset has become a recognized financial strategy. But 2026 has made clear that the model has two very distinct phases.
In a rising market, it functions exactly as designed: companies accumulate Bitcoin cheaply, premium-fueled share issuances add BTC per share, and investors benefit from both Bitcoin price appreciation and mNAV expansion. When markets stop rising, the dynamic reverses. The same tools that accelerated accumulation — leverage, share issuance, preferred dividends — become sources of pressure and risk.
The story of Bitcoin treasury companies thus far is that of a strategy that brilliantly amplifies gains on the way up, and just as clearly amplifies risk on the way down. For investors and regulators alike, understanding both sides of that equation is now essential.
Sources
- Grayscale Investments: corporate Bitcoin holdings disclosures
- Strategy (formerly MicroStrategy): investor relations filings and Bitcoin Tracker
- Tesla, Inc.: SEC filings disclosing digital asset holdings
- European Securities and Markets Authority (ESMA): MiCA implementation guidance, 2024
- Bloomberg Intelligence: Bitcoin treasury company analysis, 2025–2026
- Wall Street analyst research on corporate Bitcoin treasury models (multiple firms, 2025–2026)
- Original report: CoinCentral

