Bitcoin Derivatives Exposure Rebuilds as Traders Seek Downside Insurance
Key Takeaways
- •Total bitcoin futures open interest has recovered to nearly $60 billion, up from the mid-$40 billion range in June and July, though it remains well below the late-2025 peak of roughly $90-100 billion.
- •Bitcoin options open interest surpassed $50 billion this week, its highest level since late 2025 and roughly double the $25 billion recorded in late June.
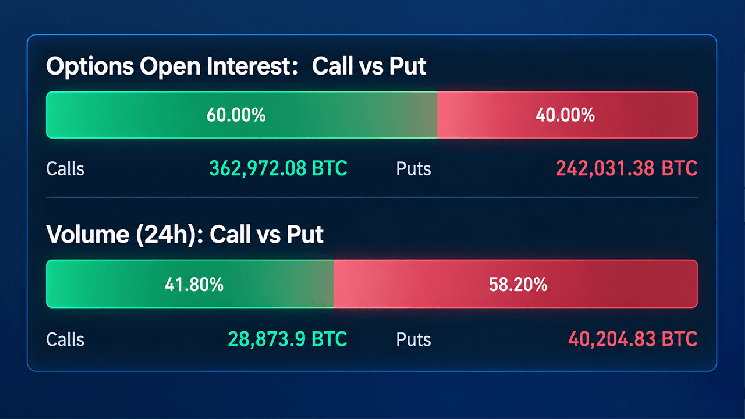
- •Calls represent 59-60% of existing options open interest while puts account for 58.2% of 24-hour volume, showing traders hold a call-heavy book but are actively seeking downside protection.
- •About $16 billion in bitcoin options are set to expire on Sept. 25, with max-pain levels near $76,000 on Deribit and OKX and around $80,000 on Binance, below the $84,416 spot price.
- •Short liquidations topped $250 million on Sept. 21, the month's largest such event, while annualized funding rates across major venues generally cluster between 1% and 4%, meaning longs are paying shorts.
Bitcoin's derivatives market is rebuilding rapidly, with futures and options exposure climbing even as the asset trades around $84,000 per unit as of 2 p.m. EST on Sept. 23, 2026. Beneath that headline number, a notable split has emerged ahead of a large options expiry on Friday: calls dominate existing positions, puts dominate fresh trading volume, and futures open interest is gathering momentum. Max-pain levels for major upcoming expiration dates are scattered across a wide range, from $60,000 to $86,000. Open interest and options positioning are among the most closely watched gauges of leverage in crypto markets, which is why this divergence is drawing attention.
Futures Open Interest Climbs Back Toward $60 Billion
Total bitcoin futures open interest has climbed back toward $60 billion, according to Coinglass.com statistics, after spending much of June and July in the mid-$40 billion range. Open interest tracks the total value of contracts still outstanding rather than one-day turnover, so a rising figure reflects rebuilt leverage, not merely heavier trading. That remains well below the roughly $90 billion to nearly $100 billion peak recorded in late 2025, but the rebound since August shows traders putting leverage back to work as bitcoin pushed into the mid-$80,000 range.
Among the top derivatives venues, Binance carries $11.72 billion in futures open interest, followed by CME at $9.83 billion, Bybit at $5.79 billion, MEXC at $5.30 billion and Gate at $5.21 billion. The decentralized perpetuals exchange Hyperliquid holds $3.53 billion, while OKX accounts for $3.27 billion. Those 11 listed venues alone represent more than $49 billion in open $BTC positions.
There is a catch: leverage has recently been trimmed almost everywhere. Binance open interest fell 7.13% over 24 hours, MEXC dropped 9.28%, Hyperliquid lost 12.33% and Bitunix was hit with a 20.73% decline. CME slipped just 1.15%, while KuCoin was one of the few gainers, rising 3.08%. The pullback came after $BTC peaked above $87,000 per coin the previous day; it has since lost 2.2% on the day.
Funding Stays Positive as Short Positions Absorb Losses
Funding rates offer another clue. These are periodic payments exchanged between perpetual futures traders to keep contract prices tethered to spot; positive funding means longs pay shorts. Across Binance, Bybit, Deribit, Hyperliquid and OKX, recent annualized funding is predominantly positive, generally clustering between roughly 1% and 4%. Deribit, crypto's largest options exchange, has printed several larger spikes, including readings north of 5% in late September — longs are paying for the privilege of holding their positions.
Liquidations tell the other half of the story. A liquidation is the forced closure of a leveraged position once losses exhaust its margin, the mechanism through which sharp price swings can sweep through crowded books. Sept. 21 produced the biggest short liquidation event, with more than $250 million wiped out, dwarfing that day's long liquidations. Another roughly $130 million short flush appeared around Sept. 18. Earlier in September, the dynamic was reversed, with about $150 million in long positions erased on Sept. 3.
Options Open Interest Jumps Above $50 Billion
The options market is where the contrast is sharpest. According to Coinglass metrics, total bitcoin options open interest has pushed above $50 billion this week, its highest visible level since late 2025 and sharply higher than the roughly $25 billion recorded around late June.
Existing positioning leans significantly toward calls. As of press time, calls represent 59% to 60% of open interest, totaling 362,972.08 $BTC, against 242,031.38 $BTC in puts. Fresh flow leans the other way: puts account for 58.2% of 24-hour volume, or 40,204.83 $BTC, compared with 28,873.9 $BTC in calls. The distinction matters because open interest is the accumulated stock of contracts while volume is the day's flow — calls convey the right to buy at a set strike price and are typically used to express upside views, while puts convey the right to sell and serve as the standard instrument for downside protection. In other words, traders have built a call-heavy book while recent trading shows considerably more demand for downside protection.
Traders have also set long-dated targets for October, a month often referred to as 'Uptober' due to bitcoin's historically positive percentage performance. Deribit's largest open-interest position is the Oct. 30 $95,000 call at 23,274.9 $BTC, followed by the $90,000 call at 15,589.7 $BTC and the $100,000 call at 12,849.6 $BTC. Yet the most heavily traded contract shown is Thursday's $80,000 put — bullish ambition meeting the insurance policy.
Close to $16 billion in options is set to expire on Sept. 25, the next major milestone on the derivatives calendar.
CME Positioning and Max Pain Put $76,000 in Focus
The institutional derivatives platform CME tells a quieter story. Its bitcoin options open interest remains far beneath the late-2025 highs, when stacked positions approached $300 million and expiration-based open interest topped 70,000 contracts. Current CME positioning is spread across several expiration windows, with the largest visible portions concentrated within roughly one to four months rather than in far-dated contracts.
Then there is max pain — the price at which the greatest value of expiring options would finish worthless. For the Sept. 25 expiry, Deribit and OKX both sit near $76,000, while Binance is around $80,000. Against bitcoin's $84,416 spot price, that leaves a sizable gap just as options activity heats up, and it is one of the reference points traders follow into Friday's settlement.
Farther out, the map becomes messier. Deribit max pain runs near $86,000 for Sept. 26 before sliding toward $60,000 by June 2027; OKX ranges from roughly $85,000 to $72,000–$75,000 across later expirations, while Binance eventually touches $70,000.
With calls ruling the accumulated stockpile and puts ruling today's trading traffic, bitcoin derivatives traders appear to be positioning for higher prices while simultaneously paying for protection against a decline.
This article is based on reporting originally published on Bitcoin.com News.

