Airtel's Mastercard-Backed Virtual Card to Challenge Safaricom's Grip on Kenya's Online Payments
Key Takeaways
- •Airtel Mobile Commerce N.V., the fintech arm of Airtel Africa, is readying a Mastercard-backed Virtual Card Number for Kenya that will link Airtel Money wallets to international merchants such as Amazon and Netflix without requiring a bank account.
- •The new card will compete with Safaricom's M-PESA GlobalPay, a virtual Visa card launched in 2022 that can draw on the Fuliza overdraft, while Airtel's prepaid product requires customers to load funds before spending.
- •Data from the Communications Authority of Kenya shows M-PESA's mobile money share falling to 88.8% in June 2026 from nearly 95% in 2023, as Airtel Money's share climbed to 11.1%.
- •Safaricom's global payments operation generated KES 4.76 billion ($37.2 million) in the financial year ended March 2026, up 22.3% year on year, underscoring the revenue potential of international online spending.
- •Airtel has issued more than 875,000 virtual cards in Uganda, Zambia, and Tanzania since 2025 and plans to expand the service to Kenya, the Democratic Republic of Congo, and Gabon, though it has yet to publish its Kenyan fee schedule and launch timing.
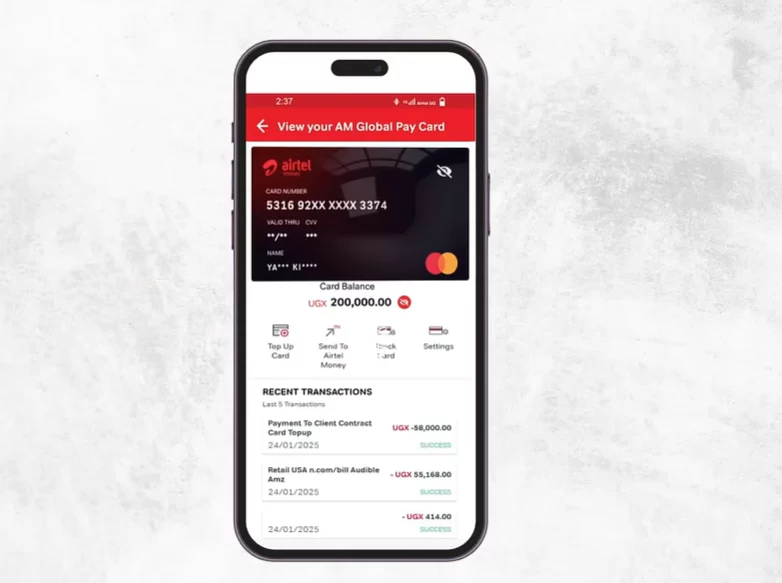
Airtel Mobile Commerce N.V., the Netherlands-based fintech arm of Airtel Africa, is preparing to launch a virtual payment card in Kenya, opening a new front in its contest with Safaricom over international online spending.
The product, a Virtual Card Number (VCN) developed in partnership with Mastercard, will integrate with Airtel Money wallets and enable customers to pay for services on global platforms such as Amazon and Netflix without holding a traditional bank account. Unlike a physical card, a VCN exists only as card details for online use, which is what allows a mobile wallet to transact with merchants and subscription platforms that bill through card networks.
The launch positions Airtel Money Global Pay in direct competition with M-PESA GlobalPay, the virtual Visa card Safaricom introduced in 2022, and pairs the mobile money rivalry with the long-running competition between Mastercard and Visa, the two largest card networks. Airtel is entering a market where Safaricom holds an established lead, built on an M-PESA service that has operated in Kenya since 2007, but the contest extends beyond the payment networks behind the cards. It also concerns how customers fund transactions, manage online spending, and access credit when their wallet balances run low.
The M-PESA GlobalPay card can draw on Fuliza, an overdraft facility that lets eligible customers complete online payments when their M-PESA balance is insufficient. Airtel Money's prepaid card lacks this feature, requiring customers to fund it before making a purchase.
Data from the Communications Authority of Kenya shows M-PESA's mobile money market share slipped to 88.8% in June 2026, down from nearly 95% in 2023. Airtel Money's share rose to 11.1% over the same period. The figures point to a gradual shift in the competitive balance, although Safaricom's lead remains substantial.
Global commerce offers a new revenue stream
Kenya's growing use of digital services gives both operators a reason to compete for international payments. Streaming subscriptions, software services, and overseas e-commerce platforms allow mobile money providers to reach spending that might otherwise flow through bank cards.
Netflix, which entered Africa in 2016, is one example of how international digital services have become part of everyday spending. Virtual cards let customers without bank accounts pay these merchants via mobile money, extending wallets' reach beyond domestic transfers and merchant payments.
For operators facing pressure on domestic payment charges, cross-border transactions also offer a way to earn revenue from international commerce. Foreign currency conversion and merchant payments can generate income beyond the core business of moving money between local accounts.
Safaricom's global payments operation, which includes cross-border transfers, virtual cards, and app store billing, generated KES 4.76 billion ($37.2 million) in the financial year ended March 2026, up 22.3% from the previous year. M-PESA generated KES 182.7 billion (323.1 billion) in transaction value across 46.4 billion transactions.
The figures show why even a relatively small slice of M-PESA's business matters. Global payments can contribute to revenue growth without requiring Safaricom to win a comparable share of Kenya's domestic mobile money market. For Airtel, the opportunity is to capture a portion of that spending as more customers use its wallet for online purchases.
Across 14 African markets, Airtel's mobile money operation generated $1.3 billion in revenue, up from $747 million. The company has issued more than 875,000 virtual cards in Uganda, Zambia, and Tanzania since 2025, and plans to introduce the service in Kenya, the Democratic Republic of Congo, and Gabon.
Credit and security separate the cards
The two products take different approaches to funding online payments. M-PESA GlobalPay links to the customer's M-PESA wallet. Airtel's VCN model, in contrast, requires customers to transfer funds from their main Airtel Money wallet to the virtual card before making a purchase.
The setup lets Airtel customers ring-fence money for online purchases, keeping the rest of their wallet balance separate from card transactions. It also gives them greater control over subscription payments and their online spending.
Customers still need to protect their account credentials and monitor transactions. The extent of protection also depends on the controls available to freeze or manage the card, dispute unauthorized payments, and prevent further charges.
Safaricom's original virtual Visa card design used a card verification value (CVV) that customers generated through the M-PESA app after entering their PIN. Each code lasted 30 minutes and could be used only once, limiting the window in which it could be exploited if exposed.
Safaricom announced the overdraft option for GlobalPay in 2026, allowing eligible customers to complete online payments when their wallet balance is insufficient. The feature can help prevent subscription payments from failing, but it also means automated charges may draw on credit, leaving customers with an overdraft to repay.
Airtel's prepaid model does not offer an equivalent overdraft facility, so customers must hold sufficient funds on the virtual card to complete a purchase. That may be less convenient, but it also prevents the card from extending spending through an equivalent credit line.
A challenger still faces a scale problem
Safaricom's large customer base gives GlobalPay an established audience, while familiarity with M-PESA can make customers less inclined to switch payment methods. Airtel's card could appeal to customers who already use Airtel Money and want a direct route to international merchants. Its regional rollout also gives the company experience to draw on as it enters the Kenyan market.
Customers will need to compare foreign exchange charges, transaction limits, acceptance rates, dispute handling, and the ease of managing card details. Airtel's pricing will be particularly important, because a lower-cost card could attract price-sensitive users, while unclear fees could blunt the appeal of its prepaid design.
Airtel has yet to disclose all the details Kenyan customers will need to assess the service, including its foreign exchange charges. Safaricom's GlobalPay applies a foreign exchange markup, making the total cost of a purchase a relevant point of comparison. Airtel publishes its full fee schedule and confirms its launch timing, the comparison between the two cards rests on features rather than total cost.
The launch will not erase Safaricom's lead in mobile money. Still, it will give Airtel another way to compete for customer spending, this time at the online checkout rather than through domestic transfers.

