AI Chip Market Statistics 2026: NVIDIA Leads as AMD, Broadcom and Custom Chips Expand
Key Takeaways
- •NVIDIA reported $75.2 billion in Q1 fiscal 2027 data center revenue, up 92% year over year, and guided Q2 revenue to $91.0 billion assuming no China data center compute revenue.
- •AMD's Q2 2026 data center revenue rose 107% to $6.7 billion with $2.1 billion in operating income, while Broadcom's Q2 fiscal 2026 AI semiconductor revenue climbed 143% to $10.8 billion on a book-to-bill ratio of about 2.8 to 1.
- •Global chip sales reached a record $791.7 billion in 2025, up 25.6%, and MarketsandMarkets projects the AI chip market will grow from $203.24 billion in 2025 to $564.87 billion by 2032 at a 15.7% compound annual rate.
- •TSMC's CEO said demand for advanced processes was roughly three times the company's production capacity, and HBM memory supply is not expected to ease until new cleanrooms open in early 2027.
- •Presenc AI estimates NVIDIA holds 80% to 85% of data center AI accelerator revenue in 2026, down from about 92% in 2023, as custom cloud chips and inference workloads shift toward alternative hardware.
The AI chip market expanded rapidly in 2026, and a small group of companies now captures most of the revenue. NVIDIA still leads by a wide margin, while AMD, Broadcom and the large cloud operators are taking a growing share of the spending.
This report draws on four sources — Presenc AI, SQ Magazine, MarketsandMarkets and Zylos. Each measures the market in its own way, so some figures do not align. The source and time period are identified for every number.
Each company also reports on its own fiscal calendar. The figures for NVIDIA, AMD and Broadcom cover different quarters, so they should not be added together.
Key figures at a glance:
- NVIDIA data center revenue, Q1 fiscal 2027: $75.2 billion, up 92% year over year
- AMD data center revenue, Q2 2026: $6.7 billion, up 107%
- Broadcom AI semiconductor revenue, Q2 fiscal 2026:10.8 billion, up 143%
- Global chip sales in 2025: $791.7 billion, up 25.6%
- AI chip market forecast for 2032: $564.87 billion
Global Chip Sales Set the Backdrop
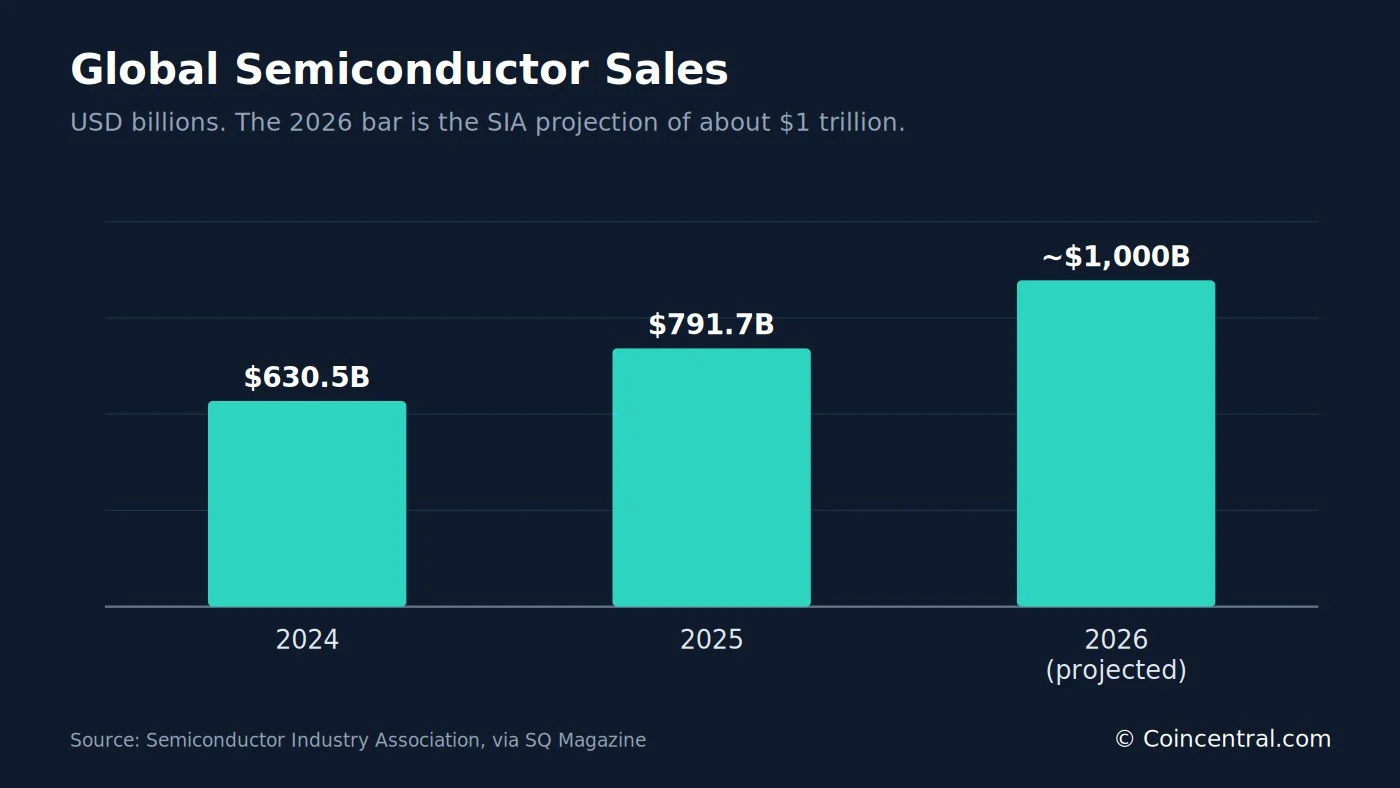
The Semiconductor Industry Association (SIA) reported global chip sales of $791.7 billion in 2025, up 25.6% from $630.5 billion in 2024 and a record for a full year. SIA projects sales of roughly $1 trillion in 2026.
Fourth-quarter 2025 sales alone came to $236.6 billion — 37.1% above the fourth quarter of 2024 and 13.6% above the third quarter of 2025.
Logic chips, the category that includes AI accelerators, grew 39.9% to $301.9 billion in 2025 and are now the largest product category by sales. Memory products grew 34.8% to $223.1 billion.
Logic outgrew the wider industry, which SQ Magazine reads as a sign that AI accelerators absorbed most of the added spending.
By region, Asia Pacific All Others grew 45.0% in 2025, the fastest of the five regions SIA tracks. Sales in the Americas rose 30.5%.
Source: Semiconductor Industry Association, February 6, 2026, via SQ Magazine. Implied 2024 values for logic, memory and the quarter are derived from the reported growth rates.
AI Chip Market Size and Forecast to 2032
A MarketsandMarkets report released August 24, 2026 puts the global AI chip market at $203.24 billion in 2025 and projects $564.87 billion by 2032, a compound annual growth rate of 15.7% that would leave the market about 2.8 times its 2025 size.
The figure uses a broader definition than a count of accelerators alone, covering compute, memory and network products. For that reason it should not be compared directly with the SIA total for all chips.
North America is the largest region, with an estimated 36.4% share in 2025. Asia Pacific is expected to grow fastest, and China is expected to post the highest growth rate of any single country in the region.
By function, inference held the largest share and is expected to grow fastest. Generative AI is expected to lead by technology. Network products are expected to grow 26.7% a year, the fastest of any offering.
Source: MarketsandMarkets, August 24, 2026.
The report also lists limits on growth, including high power consumption, higher cooling costs, a shortage of skilled workers and supply chain problems. Limited material supply and production capacity can delay deliveries and raise costs.
NVIDIA: Data Center Revenue and Guidance
NVIDIA reported first-quarter fiscal 2027 results on May 20, 2026. Total revenue was a record $81.6 billion, up 85% from a year earlier and 20% from the prior quarter.
Data center revenue was $75.2 billion, up 92% year over year. Compute brought in $60.4 billion, up 77%, and networking reached $14.8 billion, up 199%.
Edge Computing, NVIDIA's other new platform, posted $6.4 billion, up 29%. SQ Magazine notes that the new split between Data Center and Edge Computing is the first major change in segment reporting since 2019.
GAAP gross margin was 74.9%, compared with 60.5% a year earlier. NVIDIA also returned about $20.0 billion to shareholders through buybacks and dividends during the quarter.
Source: NVIDIA Q1 FY27 press release, May 20, 2026, via SQ Magazine.
For the second quarter of fiscal 2027, NVIDIA guided revenue to $91.0 billion, plus or minus 2%. The outlook assumes no data center compute revenue from China.
NVIDIA also told shareholders it can see more than $1 trillion in Blackwell and Rubin revenue from the start of 2025 through 2027. SQ Magazine points out that this is management's own view, not a signed order book.
On products, Presenc AI lists the H100 and H200 as mature, and the B200 and GB200 NVL72 as ramping with limited supply at the top end. Zylos reports that the Rubin platform entered full production in early 2026, with partner products due in the second half. NVIDIA says Rubin cuts inference token cost by a factor of 10 compared with Blackwell.
AMD: Instinct GPUs and a Growing Data Center Business
AMD reported second-quarter 2026 results on August 4, 2026. Revenue was a record $11.5 billion, up 50% from $7.7 billion a year earlier.
Data center revenue was $6.7 billion, up 107% from $3.2 billion, making up 58% of company revenue. AMD credits demand for its EPYC processors and Instinct GPUs.
Data center operating income was $2.1 billion. A year earlier, the segment lost $155 million at the operating level.
Source: AMD Q2 2026 earnings release, August 4, 2026, via SQ Magazine.
Presenc AI estimates AMD holds about 5% to 7% of data center AI accelerator revenue in 2026, up from about 2% in 2024. It names Microsoft and Meta as the largest buyers of the MI300X and MI325X.
Zylos reports that the MI400 series launches in 2026, led by the MI455X. AMD's Helios rack holds up to 72 of those GPUs. In October 2025, AMD announced a deal with OpenAI for 6 gigawatts of GPUs, with the first 1-gigawatt site using MI450 chips starting in 2026.
Broadcom: Custom Chips for Cloud Companies
Broadcom designs custom AI chips, often called XPUs, for large cloud and AI firms. On June 3, 2026, it reported Q2 fiscal 2026 AI semiconductor revenue of $10.8 billion, up 143% year over year.
Total semiconductor solutions revenue was $15 billion, up 79%. Company revenue was $22.2 billion, up 48%.
Broadcom has six core custom chip customers, including Google, Anthropic, Meta and OpenAI. Networking made up almost 40% of AI revenue in the quarter.
AI bookings were above $30 billion against $10.8 billion shipped, a book-to-bill ratio of about 2.8 to 1 — any ratio above 1 means orders are arriving faster than chips ship.
Source: Broadcom Q2 FY26 earnings, June 3, 2026, via SQ Magazine.
Broadcom expects Q3 AI revenue to reach $16.0 billion. It forecasts $56 billion in AI chip revenue for fiscal 2026 and more than $100 billion for fiscal 2027. Zylos adds that Broadcom and Marvell are winning large contracts from OpenAI, Meta and Google.
AI Chip Market Share by Vendor
Market share depends on how it is measured. Presenc AI estimates NVIDIA holds 80% to 85% of data center AI accelerator revenue in 2026, down from about 92% in 2023.
SQ Magazine takes different approach, comparing three reported revenue lines: NVIDIA data center at 81%, Broadcom AI semiconductors at 12% and AMD data center at 7% of the combined total. SQ Magazine warns that the periods and scope differ, so this is not a true market share.
No company publishes a market share for merchant AI chips. Custom chips from Google, Amazon and Meta sit outside GPU share data, and Broadcom's customer base captures part of that activity.
Source: Presenc AI, May 2026. Estimates built from company disclosures and analyst reports. Google TPU share is measured by deployed compute, so the rows do not sum cleanly.
Presenc AI names three forces shaping the market. NVIDIA's CUDA software keeps many workloads on its chips. Large cloud firms build their own silicon to cut costs. Inference work also moves to other hardware more easily than training does — one reason alternatives to NVIDIA gain ground there first.
Inference, Custom Chips and a Shifting Mix
Zylos estimates that inference now accounts for about two-thirds of AI compute in 2026, up from about one-third in 2023 and half in 2025. It puts the market for inference-focused chips at more than $50 billion.
Zylos also expects cloud providers' in-house ASICs to grow 44.6% in 2026, against 16.1% for GPUs, and projects ASIC share of the inference market rising from 15% in 2024 to 40% in 2026.
The inference chip field is also consolidating. Zylos reports that NVIDIA acquired Groq for $20 billion and Intel acquired SambaNova. Cerebras completed its IPO in early 2026.
Google's TPU line is a large part of the custom chip story. Zylos expects about 1.6 million TPU v6 shipments in 2026 and reports that Anthropic plans to use up to one million TPUs, bringing more than a gigawatt of capacity online in 2026.
Source: Zylos, AI Chip Hardware Acceleration Trends 2026. These are estimates and projections.
Zylos adds a cost point. On-premises systems can become cheaper than cloud once cloud costs reach 60% to 70% of an equivalent on-premises setup, which applies mainly to steady, high-volume inference work.
TSMC and the Foundry Bottleneck
Most advanced AI accelerators are made in Taiwan by TSMC. In the first quarter of 2026, TSMC reported revenue of $35.90 billion, up 40.6% from a year earlier. Gross margin was 66.2%, up from 62.3% in the fourth quarter of 2025.
High-performance computing made up 61% of revenue, the largest of its six platforms. Advanced nodes — 7nm and below — were 74% of wafer revenue.
TSMC expects capital spending of $52 billion to $56 billion in 2026. Its CEO said in November 2025 that demand for advanced processes was about three times what the company could produce.
Source: TSMC Q1 2026 earnings, April 16, 2026, via SQ Magazine.
Presenc AI also tracks TSMC's 2nm allocation as a topic to watch. AMD's MI400 and MI500 lines are planned on that process, according to Zylos.
HBM Memory: The Other Supply Limit
High bandwidth memory (HBM) is the second supply constraint for AI chips. SK hynix said in its Q2 2026 results that customer demand is higher than its supply, and it has signed long-term supply deals with about 10 customers.
Micron explains the problem in its own filing: HBM needs more wafers and more cleanroom space than standard DRAM to produce the same number of bits. SK hynix expects relief after its Yongin Phase 1 cleanroom opens in early 2027.
Zylos describes HBM4 as the key part of the next chip generation. It offers over 2 TB/s per stack, about 60% faster than HBM3e, and is about 40% more power efficient. SK hynix and Micron plan volume production in 2026, and Samsung moved its first output up to February 2026. SK hynix also showed a 16-layer, 48GB HBM4 stack at CES 2026.
Source: Zylos, AI Chip Hardware Acceleration Trends 2026.
No memory maker publishes an HBM demand growth rate or a date when supply catches up. The timing of new cleanrooms in 2027 is the main marker.
Edge AI and Automotive Chips
Not all AI chips sit in data centers. Presenc AI sizes the on-device AI chip market at about $25 billion to $35 billion in 2026. Apple is the largest single vendor, with Qualcomm, Intel and AMD also competing.
Apple's M4 chip has a 16-core Neural Engine rated at up to 38 trillion operations per second, and AMD's Ryzen AI 400 series offers up to 60 NPU TOPS. These ratings are not measured the same way across vendors, so they cannot be ranked directly.
Cars are another growth area. Global Market Insights estimated the autonomous-driving chip market at $24.22 billion in 2024, projects $29.73 billion in 2025 and $191.07 billion by 2034, a 23% CAGR.
NVIDIA's DRIVE AGX Orin and DRIVE Thor platforms offer up to 2,000 TOPS. Mobileye's EyeQ chips are in more than 100 million vehicles.
CHIPS Act Funding and Export Controls
The CHIPS and Science Act was signed on August 9, 2022 and created a $52 billion investment in US chipmaking. As of August 2026, more than $36 billion has been announced.
Intel reached agreement on up to $7.86 billion in direct funding for projects in Arizona, New Mexico, Ohio and Oregon. TSMC Arizona received up to $6.6 billion, plus the right to draw up to $5 billion in loans.
SQ Magazine notes that the awards lean toward leading-edge logic plants. Packaging and memory steps, which also limit accelerator output, receive less direct support.
Source: NIST CHIPS Program Office; Intel Newsroom; TSMC Form 20-F, via SQ Magazine.
Export rules also affect the market. On April 9, 2025, the US government told NVIDIA that it needs a license to export H20 chips to China. NVIDIA took a $4.5 billion charge in the first quarter of fiscal 2026. The charge was small in the fourth quarter of fiscal 2026 and zero in the first quarter of fiscal 2027. NVIDIA's guidance now assumes no China data center compute revenue. Presenc AI says vendors such as Huawei Ascend hold about 2% to 3% of the market, mostly in China.
What the Numbers Show
The data points to fast growth with a clear leader. NVIDIA reported $75.2 billion in data center revenue in one quarter, AMD reported $6.7 billion and Broadcom reported $10.8 billion in AI chip revenue. Each figure covers a different period, so they describe separate results.
The wider market is also large. Global chip sales hit $791.7 billion in 2025, and MarketsandMarkets expects the AI chip market to reach $564.87 billion by 2032.
Supply remains the main constraint. TSMC wafers and HBM memory both fall short of demand, and new memory capacity arrives in 2027. Export rules add more uncertainty, especially for sales to China.
Near-term markers already on the calendar give readers fixed points to track: NVIDIA's Q2 FY27 revenue guidance of $91.0 billion, Broadcom's expected $16.0 billion in Q3 AI revenue, Rubin-based partner products due in the second half of 2026, the AMD MI400 launch, and SK hynix's Yongin Phase 1 cleanroom opening in early 2027.
Market share estimates vary by source, and many figures are estimates. Readers should check the period and scope behind each number before comparing them.
Sources
- AI Chip Market Share 2026 (Presenc AI)
- AI Chip Statistics 2026: Data Center Revenue, Vendor Share and Supply (SQ Magazine)
- AI Chip Market to Reach USD 564.87 Billion by 2032, Growing at 15.7% CAGR, Says MarketsandMarkets
- AI Chip Hardware Acceleration Trends 2026 (Zylos)
This article first appeared on Blockonomi.

