Stablecoins Set to Dethrone Traditional Bank Rails as Africa's New Money Architecture, Panellists Say
Key Takeaways
- •Panel participants selected stablecoins over card and bank networks for future intra-African invoice settlement.
- •Stablecoin transactions are being promoted for their lower costs, faster processing and transparent blockchain records.
- •Consumer trust and the traditional banking sector’s ability to adapt remain significant barriers to wider adoption.
- •Regulators face pressure to create flexible, coordinated rules that cover issuers, exchanges and cross-border transactions.
- •Nigeria is using regulatory sandboxes and developing a stablecoin framework to assess digital-asset payment flows.
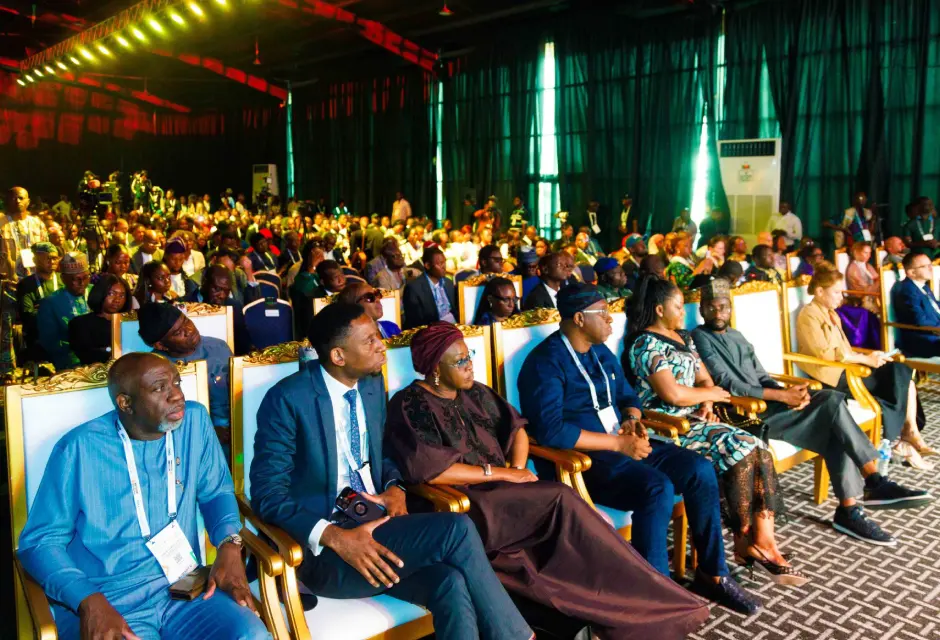
LAGOS — At the GITEX Nigeria event in Lagos on Thursday, a panel of African fintech leaders delivered a striking verdict on the future of cross-border payments: every panellist on stage rejected traditional bank networks and chose stablecoins as the rail on which African businesses will settle invoices five years from now.
The question came from TechCabal's Temitayo Jaiyeola, who put it directly to industry leaders during a panel session titled "Africa's Financial Reset: The New Architecture of Money, Markets and Movement" on the event's Main Stage: five years from now, when two African businesses in different countries settle an invoice on a single rail, will they use card networks, bank rails, or stablecoins? The unanimous answer was stablecoins.
The consensus reflects a deeper structural shift. Physical borders slicing across the African continent have always been formidable trade barriers, yet the financial borders have proven even more rigid. For decades, moving money from a trader in Accra to a supplier in Lagos has involved an exhausting labyrinth of correspondent banks, exorbitant fees, and punishing delays. The continent's financial architecture was built to keep capital siloed — and that architecture is now collapsing with the arrival of stablecoins.
In its place, new middleware is rising that does not rely on the legacy clearing systems which have historically choked intra-African commerce. The shift is not a theoretical forecast. It is the immediate reality for millions of users and businesses adopting digital assets as their primary instrument of monetary value.
Speed and Cost Drive the Pivot
According to Lasbery Oludimu, VP of Global Operations and MD at Yellow Card, the pivot toward digital assets is an organic response to market friction. Oludimu argued that the speed and low cost of stablecoin transactions make them the undeniable choice for businesses.
Yellow Card has already positioned itself at the vanguard of this shift. Recent industry reports highlight that the company is building foundational cross-border payment infrastructure, leveraging tools such as Fireblocks' Wallets-as-a-Service to secure multi-party computation wallets at scale. This allows corporate treasuries to navigate foreign exchange risks and bypass inefficient legacy systems.
Moyo Sodipo, Co-founder and COO of Busha, echoed the sentiment and mapped out a near future in which a Nigerian trader could convert a naira-pegged stablecoin, such as the cNGN, directly into a South African rand stablecoin. The transaction would settle entirely on the blockchain, providing a transparent end-to-end audit trail that regulators can easily monitor.
Sodipo noted that stablecoins are already functioning as monetary value today. Users on platforms like Busha can buy airtime or groceries at retail outlets using digital assets, cementing their utility in daily life.
The Trust Deficit and Traditional Gatekeepers
If stablecoins offer a superior technological solution, why does the average consumer still default to fiat currency? Unwana Esang, Vice President and Principal Consultant for Services Business Development at Mastercard, offered a blunt diagnosis: it is fundamentally a trust issue. Until that trust is established, even the most elegant payment solutions will fail to scale.
To address the gap, global entities are investing heavily in cybersecurity and infrastructure stress-testing. But Esang directed his sharpest critique at traditional financial institutions, warning that legacy banks are still operating with an incumbent mindset and acting as gatekeepers rather than ecosystem partners. This reluctance to adapt means traditional finance is steadily losing ground to non-traditional players that are more agile and responsive to market needs. A massive mindset shift, he argued, is required for traditional operators to remain relevant.
Regulating a Moving Vehicle
The rapid adoption of digital assets places regulators in a difficult position. Caleb Afaglo, President of the Chamber of Digital Asset and Blockchain Innovations Ghana, characterized the current regulatory moment as an attempt to regulate a moving vehicle. Policy enacted through rigid, multi-year statutory acts inevitably fails the moment it is printed — technology iterates daily, while parliaments meet intermittently.
Afaglo advocates for omnibus legislative frameworks that empower central banks and securities commissions to deploy dynamic, living guidelines. Initiatives such as the African Continental Free Trade Area (AfCFTA) and the Pan-African Payment and Settlement System (PAPSS) were drafted to foster unified commerce, but they risk falling back into the same fiat bottlenecks if they fail to harmonize digital asset frameworks. If a trader in Accra cannot freely exchange value with a merchant in Lagos because national policies diverge wildly, Africa will simply duplicate the inefficiencies of fiat bureaucracy on top of digital tokens.
Nigeria's Regulatory Recalibration
Nigeria is currently setting a precedent for the rest of the continent. The Central Bank of Nigeria has progressively shifted its stance on digital assets, and the Payments System Vision 2025 specifically noted the need for a regulatory framework for stablecoins.
Oludimu praised Nigerian regulators for focusing on the actual functionality of stablecoins as a means of payment rather than treating them purely as speculative tokens. By initiating regulatory sandboxes, the CBN is attempting to understand how cross-border stablecoin flows impact national monetary policy before imposing blanket restrictions.
Sodipo added that responsible operators have long anticipated this regulatory scrutiny. From its inception in 2018, Busha implemented bank-grade Know Your Customer protocols — long before any formal mandate existed. This proactive compliance ensures that when regulators finally arrive at the table, operators are ready to demonstrate a secure, transparent environment.
The Road Ahead
The panellists' consensus is that the transition to a digital, borderless financial architecture is inevitable, but reaching full maturity will require deliberate action. The ecosystem needs harmonized standards across the African free trade zone so that digital value can move as seamlessly as data.
The practical test will be whether countries can align rules for stablecoin issuers, exchanges and cross-border transactions without weakening consumer protections or oversight. Those unresolved questions — alongside the trust concerns raised on the panel — will determine how far the technology moves beyond individual platforms and into routine regional commerce.
Asked to summarize the future of the space in a single word, the panellists offered a clear roadmap: Oludimu called for collaboration, Afaglo demanded unity, Sodipo highlighted adoption, and Esang concluded with interoperability.
Source: TechNext24
