U.S. Debt Outlook Darkens as Treasury Yields Surge to Highest Levels in Two Decades
Key Takeaways
- •The 10-year Treasury yield surged to 5.23% on Friday, its highest level since 2007, while the 30-year yield reached 5.49%, a level last seen in 2004.
- •Current yields have already exceeded the CBO's February projections, which anticipated a 10-year yield of only 4.1% this year.
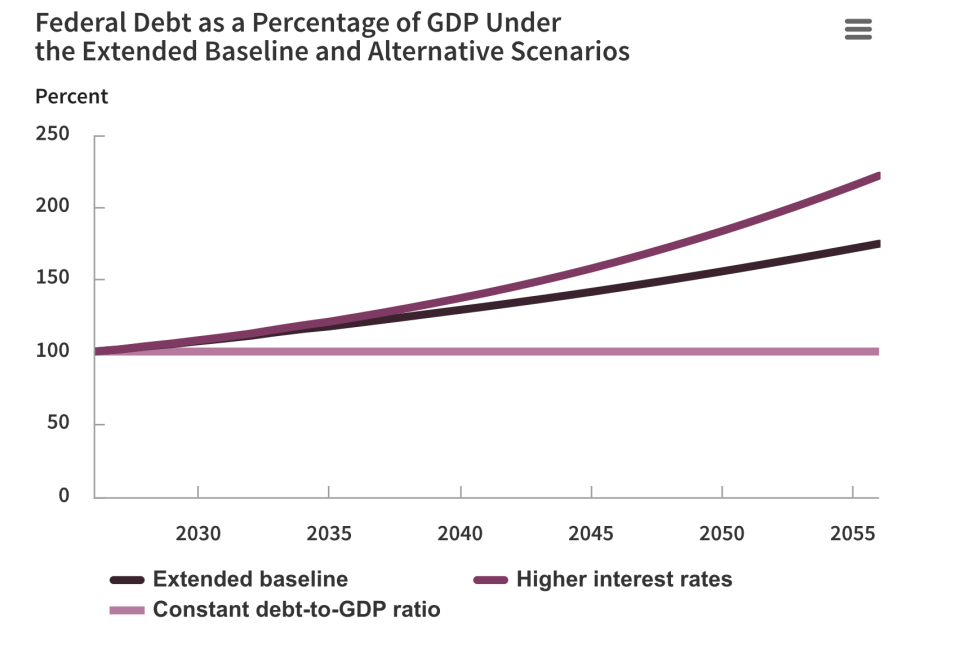
- •At the request of Sen. Jeff Merkley, the CBO examined a hypothetical scenario with interest rates 1 percentage point above baseline, projecting publicly held debt would reach 222% of GDP by 2056, up from 101% today.
- •Under that scenario, the total deficit would balloon to 14% of GDP by 2056, with annual interest expenses already at $1 trillion and the budget deficit on pace for $2 trillion this year.
- •The CBO said economic growth would run 0.1 percentage point below baseline under the higher-rate scenario, and macroeconomic effects would push interest rates and debt above even those figures.
Soaring Treasury yields are drawing alarm on Capitol Hill, as their steep climb in recent months deepens the gloom surrounding the outlook for U.S. debt.
The 10-year Treasury yield surged to 5.23% on Friday, its highest level since 2007 and more than a full percentage point above where it stood just before the Iran war began. The 30-year yield, meanwhile, reached 5.49%, a level last seen in 2004.
Several forces are driving the move: oil prices lifted by the Middle East conflict, AI hyperscalers spending hundreds of billions of dollars a year, an economy running hot, and a national debt that now stands at $40 trillion. Yields have already blown past the long-term outlook of the Congressional Budget Office (CBO), Congress's nonpartisan budget analyst. In its most recent forecasts, issued in February, the CBO projected the 10-year yield at 4.1% this year, 4.2% in 2027, 4.3% from 2028 to 2031, and 4.4% from 2032 to 2036. Those projections look quaint today, and the gap between them and market reality has become a running gauge of how fast the government's borrowing costs are outrunning official forecasts.
Beyond setting the pace for other borrowing costs, from mortgages and auto loans to corporate debt, yields determine how much the Treasury Department must pay in interest on the national debt — a figure that can accelerate as rates climb. Annual interest expenses already total $1 trillion, and the budget deficit is on pace to reach $2 trillion this year, with no sign of any political willingness to rein them in.
The abrupt spike in yields prompted Sen. Jeff Merkley, the ranking Democrat on the Senate Budget Committee, to ask the CBO for fresh numbers. In a letter replying to the senator, CBO Director Phillip Swagel examined a scenario — a hypothetical exercise rather than a forecast — in which interest rates rise until they stand 1 percentage point above the baseline.
Before incorporating macroeconomic effects, the CBO estimated that the primary deficit — which excludes net outlays for interest — would be 0.4 percentage point larger by 2056 than under the baseline view. The total deficit, however, would be 4.9 percentage points larger, indicating how much of an additional burden interest expenses will become. The total deficit would balloon to 14% of GDP, up from the 5.8% expected this fiscal year and the 3.8% average from 1976 to 2025.
Publicly held debt, meanwhile, would explode to 222% of GDP by 2056 under the scenario in which interest rates rise by 1 point. That is up from 101% of GDP today, and 47 percentage points higher than the CBO's current baseline forecast for 2056.
As the debt soars, the CBO said, the U.S. economy will slow and will not be able to keep up with the pace of borrowing, as capital is funneled into Treasury bonds rather than more productive uses. GDP growth will be 0.1 percentage point below its baseline, dampening hopes that the United States can grow its way out of the debt. Treasury Secretary Scott Bessent has said that is possible if growth hits 3%.
The CBO also suggested its numbers under this scenario would be even worse after accounting for effects on the broader economy. “The resulting increase in debt as a percentage of GDP increases interest rates on Treasury securities even further,” Swagel added. “Thus, macroeconomic effects push interest rates above the initial boost that was built into the scenario.”
For purposes of comparison, the CBO presented another, albeit fantastical, scenario in which the debt-to-GDP ratio somehow stays flat at its current level of 101%. In this utopia of fiscal prudence and frugality, the primary deficit would be 2 percentage points smaller than the CBO's baseline by 2056, the total deficit 5.6 percentage points smaller, publicly held debt 74 percentage points smaller. And while GDP growth would be only 0.05 percentage point higher than the CBO's baseline, that does not account for additional macroeconomic spillover effects.
“The increased GDP growth encourages more investment, increasing the amount of capital available to workers,” Swagel wrote. “That higher capital stock raises the marginal product of labor, encouraging more labor, which results in further GDP growth.”
This story was originally featured on Fortune.com.

