Treasury Yields Hover Near 24-Year High as Pimco Warns 6% Is Feasible
Key Takeaways
- •The 10-year Treasury yield traded near 5.29%, its highest level since April 2002, and Pimco's Dan Ivascyn said a 6% yield, last seen in 2000, is feasible.
- •Ivascyn pointed to higher oil prices, ongoing inflation, and increased US debt as drivers, cautioning that leveraged hedge funds unwinding losing positions could accelerate the selloff.
- •Russell Investments attributed more than 70% of the yield increase since the end of February to higher real rates and a widening real term premium.
- •Freddie Mac reported the 30-year fixed mortgage rate climbed to 7.40% on October 8, up from 7.28% the prior week and 6.30% in 2025.
- •The $22 billion 30-year Treasury auction on October 8 cleared at a 5.618% yield with a bid-to-cover ratio of 2.54, though strong demand does not prevent elevated borrowing costs from pressuring stocks, corporate credit, and cryptocurrencies.
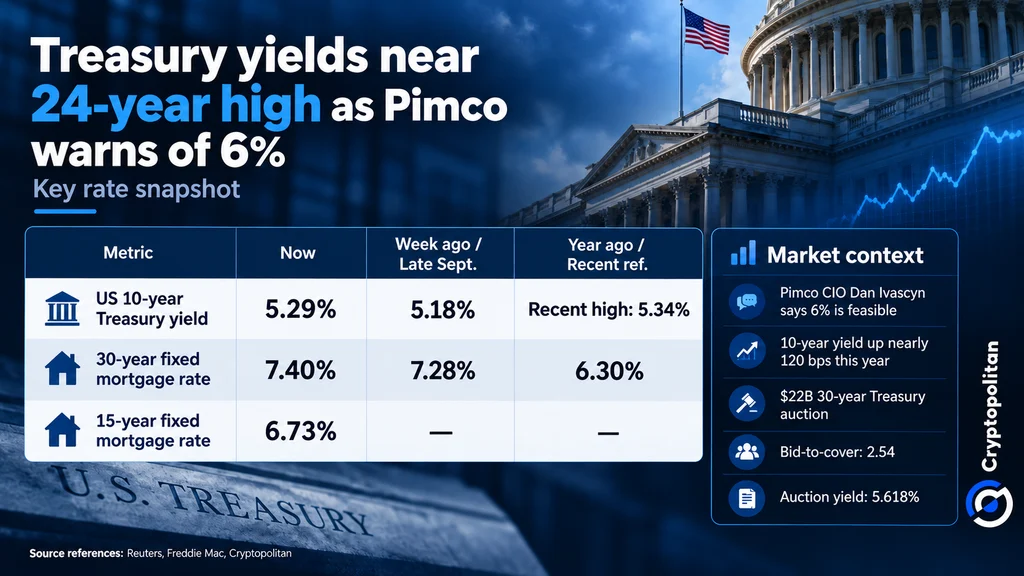
The US 10-year Treasury yield hovered near 5.29% on Friday, just below its recent peak of 5.34%, according to Federal Reserve data. The benchmark rate last traded at these levels in April 2002, when it reached 5.36% on April 2.
Dan Ivascyn, chief investment officer at bond manager Pimco, said a 6% yield is a possibility — a level the benchmark has not touched since 2000, as Reuters noted — a prospect that raises fears of high borrowing costs for stocks and corporate credit across the globe.
Why Pimco calls 6% “feasible”
Ivascyn described another sharp jump in yields as “feasible,” while cautioning that leveraged hedge funds could accelerate the selloff as they unwind losing positions. As reported by Reuters, his arguments center on higher oil prices, ongoing inflation, and the increased debt faced by the United States.
The 10-year yield has climbed by roughly 120 basis points (1.2 percentage points) this year, with the July-to-September period marking the largest quarterly increase of this century. Ivascyn cautioned that a rise above 5.5% might spur “some decent weakness in risk markets, both credit and equity.” Cryptocurrencies may also experience difficulties, given investors’ tendency to rotate toward higher-yielding Treasuries.
More than 70% of the move is real rates
The Federal Reserve is not solely responsible for rising yields: unlike the short-term rates the Fed sets directly, the 10-year is priced by market trading. According to Russell Investments, more than 70% of the increase since the end of February has been attributed to higher real rates — yields adjusted for inflation — and the widening of the real term premium, the extra compensation investors demand for holding longer-dated debt.
In a review published in September, the Bank for International Settlements reported that investors continue to buy riskier assets, including emerging-market investments, despite increasing yields. The International Monetary Fund, however, cautioned that sudden changes in market sentiment could lead to an outflow of capital from weakened economies.
The plumbing is flashing warning signs
Several market mechanics could worsen the bond selloff. An analysis by Reuters revealed that investors who acquired long-term bonds sold by AI firms are now selling Treasury futures to protect themselves from climbing interest rates. Goldman Sachs predicts that hyperscalers would borrow $420 billion in debt next year, which may add further pressure.
Investors are also becoming increasingly wary about holding long-term government bonds. The difference between 10-year and 30-year Treasury yields has climbed to around 37 basis points, indicating that investors feel they need more compensation for the risks associated with such long-term investments.
Mortgage markets can make the situation worse. Rising interest rates mean homeowners will be less inclined to refinance, prolonging the time that mortgage-backed securities remain outstanding. Investors react by selling Treasury futures to hedge their risk, which increases the pressure on bond prices — and, because yields move inversely to prices, drives yields higher still.
Anxiety is also reflected in the options markets. The price of protecting against a 200 basis point increase in interest rates has risen to its highest level since March 2023. With several forces putting the market under pressure at the same time, even a small market movement could cause a chain reaction.
Households already feel it at 7.40%
Higher mortgage rates are making home ownership even harder for Americans. Freddie Mac reported that the 30-year fixed mortgage rate climbed to 7.40% on October 8, compared with 7.28% the week prior, whereas the rate stood at 6.30% in 2025. The 15-year rate, meanwhile, rose to 6.73%.
The increase confirms the trend reported by Cryptopolitan in September, when rising Treasury yields pushed mortgage rates higher.
What strong demand can and cannot fix
Investors still showed up for the $22 billion 30-year Treasury bond auction on October 8, as Reuters reported. The auction’s clearing yield was 5.618%, and it drew a bid-to-cover ratio of 2.54 — roughly $2.54 in orders for every dollar of bonds on offer, a standard gauge of auction demand.
Even so, ample interest in bonds does not mean borrowing will be cheap, as buyers are looking for higher returns. If yields linger around 6%, pressure would fall not only on Treasury bonds, despite their strong demand, but also on stocks, corporate credit, and cryptocurrencies.

