Yen's Appreciation Potential May Be Running Out as BoJ Tightening Already Priced In
Key Takeaways
- •Markets price in roughly 45 basis points of BoJ rate increases by year-end, with the policy rate expected to approach a neutral 2% within twelve months.
- •A 50-basis-point September hike followed by back-to-back increases is considered unlikely given weak Japanese consumption and government influence over policy pacing.
- •Speculation that the GPIF, which manages about USD2 trillion, could increase domestic asset holdings has supported the yen, but any official announcement may not come until late October.
- •The 155 level is the key technical support for USD/JPY, and consolidation around it is seen as more likely than an immediate move to the 150-152 range.
- •Further material yen appreciation would require either a hawkish BoJ surprise or a significant change in domestic investment flows.
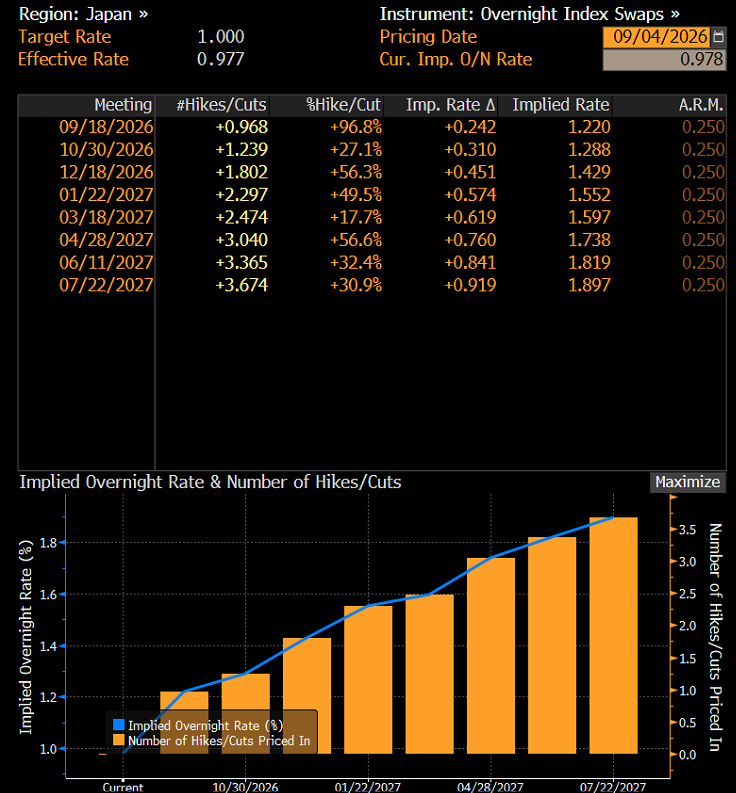
The yen has seen another week of sharp fluctuations, but the scale of monetary tightening currently expected from the Bank of Japan suggests that much of the positive news has already been reflected in the currency's valuation. Markets now price in around 45 basis points of rate increases by the end of the year, and over the next twelve months the policy rate is expected to approach 2%, which is widely regarded as a neutral level. A 50-basis-point September hike followed by back-to-back increases remains unlikely, while potential changes to the GPIF's asset allocation have also supported the yen. The 155 area may act as key support for USD/JPY.
Aggressive BoJ tightening already priced in
A further sustained decline in USD/JPY would probably require expectations to shift towards an even more aggressive BoJ tightening cycle. An extremely hawkish scenario would involve a 50-basis-point increase in September, followed by additional moves in October and December. This would bring the policy rate to 2% before year-end, representing a total tightening of 100 basis points.
Such a scenario appears unlikely. Japanese consumption remains weak, limiting the economy's ability to absorb a rapid increase in borrowing costs. The government also retains significant influence over the direction of economic policy, which could encourage the BoJ to proceed more gradually. The probability of a 50-basis-point move in September followed by consecutive rate hikes therefore remains low.
This gradualism matters beyond Japan. Because the yen has long served as a low-yield funding currency for global carry trades, expectations about the pace of BoJ normalisation have implications for positioning well beyond USD/JPY itself.
GPIF speculation supports the currency
The yen has also benefited from speculation that Japan's Government Pension Investment Fund could increase the share of domestic assets in its portfolio. The GPIF manages approximately USD2 trillion, and any shift towards Japanese securities could generate additional demand for domestic assets, indirectly supporting the currency. The fund, one of the world's largest institutional investors, currently splits its portfolio across domestic and foreign bonds and equities, making any rebalancing of its benchmark weights a market-moving event.
These expectations have not yet been confirmed. Any formal announcement may come only in late October, meaning the market could face a prolonged wait before receiving a clear signal. Without confirmation, speculation surrounding the GPIF may provide increasingly limited support for the yen.
USD/JPY may stabilise near 155.00
The main obstacle to further yen appreciation is that both expected BoJ rate increases and a potential change in the GPIF's investment strategy appear to be largely priced in. The 155 level remains an important support area for USD/JPY. In the short term, consolidation around this level may therefore be more likely than an immediate move towards the 150–152 range.
The positioning of speculative investors also points to more limited appreciation potential. Short positions in the yen are not as large as they were two years ago. Consequently, the closing of bearish positions is unlikely to produce a rally comparable with those seen during previous episodes of rapid yen appreciation.
A new catalyst is needed
The medium-term outlook for the yen remains constructive as the Bank of Japan continues to normalise monetary policy. Following its recent appreciation, however, the currency may require a fresh catalyst to extend its gains.
Unless the BoJ signals a more aggressive path of rate increases or the GPIF confirms a higher allocation to domestic assets, USD/JPY may enter a period of consolidation around 155. A further material strengthening of the yen would require either a hawkish surprise from the central bank or a significant change in domestic investment flows.
USD/JPY technical analysis
In late July, USD/JPY broke below its medium-term ascending channel. The move was triggered by intervention and the effects of coordinated action by Japan and the United States. The pair subsequently staged an upward correction towards the 160 area before coming under renewed selling pressure and falling back to 155.
The 155 level is now the key technical support and, for the time being, buyers are successfully defending it. A period of consolidation or another rebound could therefore develop from this area. However, a break below 155 cannot be ruled out. If confirmed, it could open the way towards 152, where the lows recorded in late January and February 2026 are located.
Opinions are the authors'; not necessarily that of OANDA Business Information & Services, Inc. or any of its affiliates, subsidiaries, officers or directors. The provided publication is for informational and educational purposes only.
Source: OANDA MarketPulse
