US Gold Reserves Worth $1 Trillion at Market Rates—But Repricing the Hoard 'Would Backfire in a Big Way,' Analyst Says
Key Takeaways
- •The U.S. Treasury's roughly 261.5 million ounces of gold, the world's largest reserve, are carried on government books at just over $11 billion because Congress set the official price at $42.22 per ounce in 1973.
- •At current market prices near $4,000 per ounce, the same stockpile would be worth about $1 trillion, but unlocking that value would require an act of Congress.
- •Treasury Secretary Scott Bessent said in July that the Fort Knox gold was 'present and accounted for' and worth over $1 trillion at market value, though the administration has stated that repricing gold is not under serious consideration.
- •Fidelity's Jurrien Timmer argued that repricing gold would likely backfire by weakening the dollar, fueling inflation, and pushing the Treasury term premium even higher.
- •A Federal Reserve economist's note found that Germany, Italy, Lebanon, Curacao and St. Maarten, and South Africa have revalued their gold reserves over the past 30 years, but such proceeds improve fiscal positions only at the margin and do not resolve structural debt challenges, with gross U.S. debt now at $40 trillion.
With the federal budget deficit running at $2 trillion and debt-interest costs topping $1 trillion a year, Washington may be tempted to hunt for extra cash under the sofa cushions. That urgency has intensified in recent months as Treasury yields have soared to their highest levels in more than 20 years, piling further pressure onto interest expenses.
The Treasury Department has already turned to unconventional measures to take the heat off yields, including buybacks of more long-dated debt and an intervention to prop up the yen that allowed Japan to avoid selling its Treasuries. Given such surprises, speculation has grown around even more far-out tactics—and one idea resurfaces from time to time: pricing the Treasury's immense gold holdings at market rates.
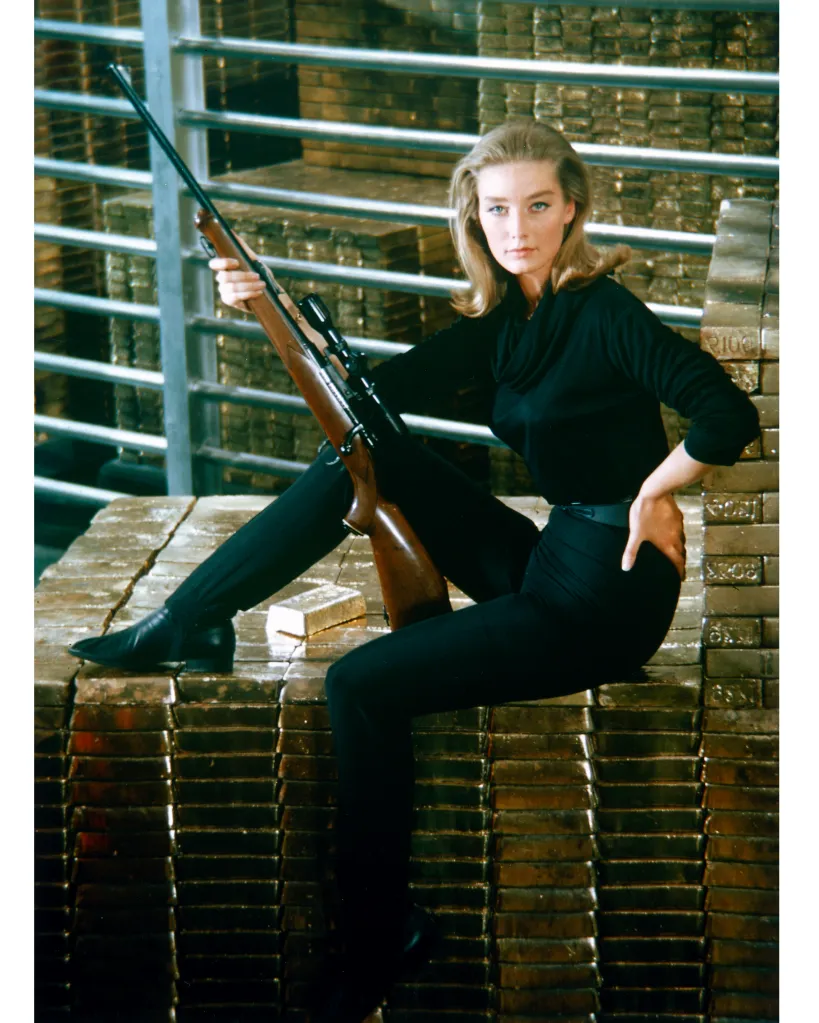
The U.S. holds the world's largest gold reserves, totaling about 261.5 million ounces—more than double the stockpile of No. 2 Germany. But the official price of that hoard was set by Congress in 1973 at $42.22 per ounce—a remnant of the era when the dollar was still tied to gold—and it has not changed since. As a result, the entire cache sits on the government's books at just over $11 billion. Valued at gold's current price of around $4,000 per ounce, however, it would be worth $1 trillion. And because that valuation is fixed by statute rather than marked to market, the gap between book value and real-world value widens on its own whenever gold rallies—a paper windfall that stays locked on the books unless Congress changes the number.
Comments by Treasury Secretary Scott Bessent last year that the government would "monetize the asset side of the U.S. balance sheet" and create a sovereign wealth fund fueled talk that repricing gold could be part of the plan, though the administration later said the idea is not under serious consideration. Even so, scrutiny of America's gold reserves keeps popping up. A recent bill in Congress to establish a strategic bitcoin reserve, for instance, proposed repricing U.S. gold holdings. And last year, President Donald Trump questioned whether the gold held at the Fort Knox U.S. Army base was actually there. (The Treasury's gold is also stored in Denver, at the New York Fed, and in West Point, NY.)
In July of this year, Bessent reignited theories about the metal, saying that the cache at Fort Knox was all "present and accounted for"—before casually adding that "the U.S. has the largest pile of gold in the world, over a trillion dollars at current market value."
That comment prompted Jurrien Timmer, director of global macro at Fidelity Investments, to start thinking about "what other tricks the Treasury Department might have up its sleeve to try to bring down the cost of funding."
In a post on X on Friday, Timmer tackled the "old meme" of the Treasury repricing its gold to market rates—a move that would theoretically hand the federal government another $1 trillion to spend without having to issue more debt.
"Far-fetched? Of course, but these days I have learned to never be shocked by anything anymore. Notwithstanding that an action like this would require congressional approval, my guess is that if the Treasury were attempt do this, it would backfire in a big way," Timmer warned.
For one thing, he predicted, the U.S. dollar would take a hit—presumably because a sudden influx of $1 trillion would stoke more inflation, which is already heating up. For the world's primary reserve currency, even a perceived erosion of value is a sensitive matter for policymakers. Timmer also cautioned that the "term premium" in Treasury yields would rise even higher. Rates have shot up in recent months for a combination of reasons, including expectations for Fed rate hikes, robust economic growth, and persistent inflation. The term premium—the extra return investors demand to cover the risk of holding debt over the long term—has climbed as well, with those risks ranging from geopolitical turmoil to a fiscal crisis or an economic downturn.
While such a step may seem unlikely in the U.S., other countries have revalued their gold reserves over the last 30 years. A note from a Federal Reserve economist last August pointed out that Germany, Italy, Lebanon, Curacao and St. Maarten, and South Africa have all done so. In Italy and in Curacao and St. Maarten, the central banks used the proceeds; in South Africa, Lebanon, and Germany, the central governments reaped the windfall.
But when it comes to reducing a country's debt burden, the Fed note added, gold revaluation isn't enough—particularly as gross U.S. debt has soared to $40 trillion, with no end in sight to $2 trillion annual budget deficits.
"Central governments have drawn on revaluation proceeds to retire existing debts, often in exceptional fiscal circumstances," the Fed note added. "While reducing the debt stock using revaluation proceeds improves the fiscal situation at the margin, drawing on revaluation proceeds may not address larger structural challenges."
For now, altering the $42.22 official price would require an act of Congress—a higher bar than the debt buybacks and currency interventions the Treasury has already pulled off—and the administration has kept the idea at arm's length. As long as elevated yields and $2 trillion deficits keep the pressure on, though, the trillion-dollar question of what to do with America's gold is likely to keep resurfacing.
This story was originally featured on Fortune.com.

